


EN
StoneCo Stock Outlook After Guidance Withdrawal Could Be A Game Changer For StoneCo (STNE)
- StoneCo reported its third quarter 2026 results and discussed product simplification, client retention efforts, a cautious stance on credit, and the withdrawal of its 2027 financial guidance due to macro uncertainty.
- The focus on government backed credit with guarantees and a more focused product set indicates that StoneCo is trading some growth optionality for what management describes as healthier risk adjusted returns.
- We will now explore how StoneCo's renewed focus on product simplification and client retention could reshape the broader investment narrative.
Scan beyond StoneCo and pressure test this cautious credit, quality first playbook against a curated list of 31 resilient stocks with low risk scores that may handle volatility in a similar way.
StoneCo Investment Narrative Recap
For an investor to stay with StoneCo, the belief usually rests on the shift toward a full service financial platform for Brazilian merchants where payments, banking, and credit sit in one merchant relationship. The analyst consensus Narrative on Simply Wall St assumes that earnings may decline over the next few years, so execution quality matters more than headline growth. The recent focus on product simplification and retention fits that lens by trying to stabilise the franchise.
Right now, the near term swing factor is how transaction volumes and credit quality behave while StoneCo stays cautious on new lending. A more selective approach to credit could ease cost of risk, but it may also leave Total Payment Volume and credit balances less responsive if demand improves. The biggest operational risk remains that modest TPV growth and elevated credit losses persist together, which would make it harder to translate simplification into better earnings resilience.
The most relevant development for this discussion is StoneCo’s decision to prioritise government backed working capital credit with guarantees and to withdraw its 2027 targets in light of higher volatility. That shift speaks directly to the risk side of the banking and credit narrative, because it leans toward collateralised and guaranteed exposures rather than broad based unsecured expansion.
Analysts in the consensus Narrative on Simply Wall St previously framed the growing BRL 3.8b credit book as a key earnings lever, assuming risk adjusted returns remain acceptable. With the new, tighter stance on credit, the story becomes more about protecting net margins and capital than about rapid asset growth. For you, the question is whether a steadier, slower credit engine still supports the broader full service entrepreneur bank thesis, given softer TPV growth and high cost of risk flagged in the earlier narrative.
StoneCo's narrative projects R$17.1b revenue and R$2.7b earnings by 2029. This implies 8.0% yearly revenue growth and an earnings decrease of R$0.8b from R$3.5b today.
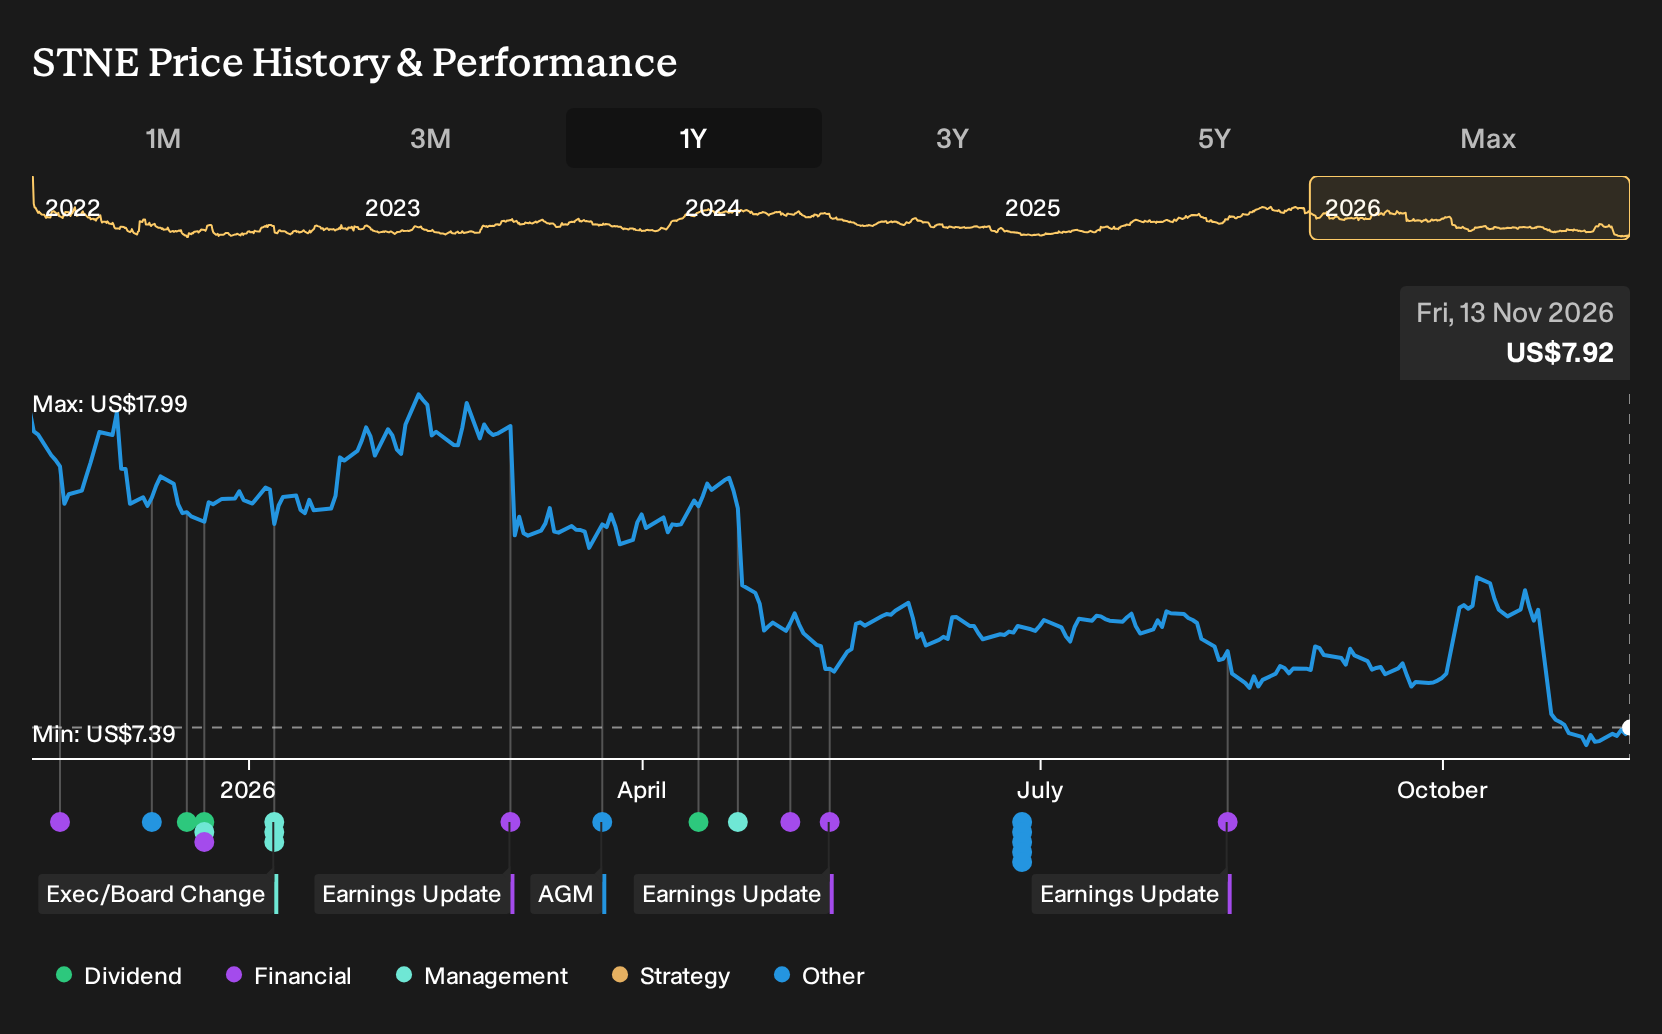
Uncover why StoneCo's fair value indicates a 75% potential upside to its current price, a gap that could narrow quickly.
Exploring Other Perspectives
One alternate view leans hard into StoneCo’s credit engine as a catalyst. The most optimistic analysts were pencilling in R$20.1b of revenue and R$3.5b of earnings by 2029, assuming government backed and secured lending could scale efficiently. You can treat that as a higher octane narrative that might shift after this latest update.
Explore 4 other StoneCo fair value estimates, including one that suggests as much as 527% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your StoneCo research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for StoneCo. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate StoneCo's overall financial health at a glance.
Looking for more investment ideas beyond StoneCo?
If the StoneCo story has sharpened your thinking about risk, return, and business quality, use that same framework to scan a wider universe of opportunities with the Simply Wall St Screener.
- If capital protection sits high on your list, start with a 31 resilient stocks with low risk scores that may appeal if you want businesses with steadier risk profiles.
- For readers hunting for quality at a reasonable price, filter for companies trading below their estimated worth using our 32 high quality undervalued stocks that already clear some key fundamental checks.
- Income focused investors who care about consistency can zero in on yield plus balance sheet strength by reviewing a curated set of 6 dividend fortresses that might suit a more cash flow oriented approach.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com