


EN
What Arrow Electronics Bulls Got Right Before A 78% Jump
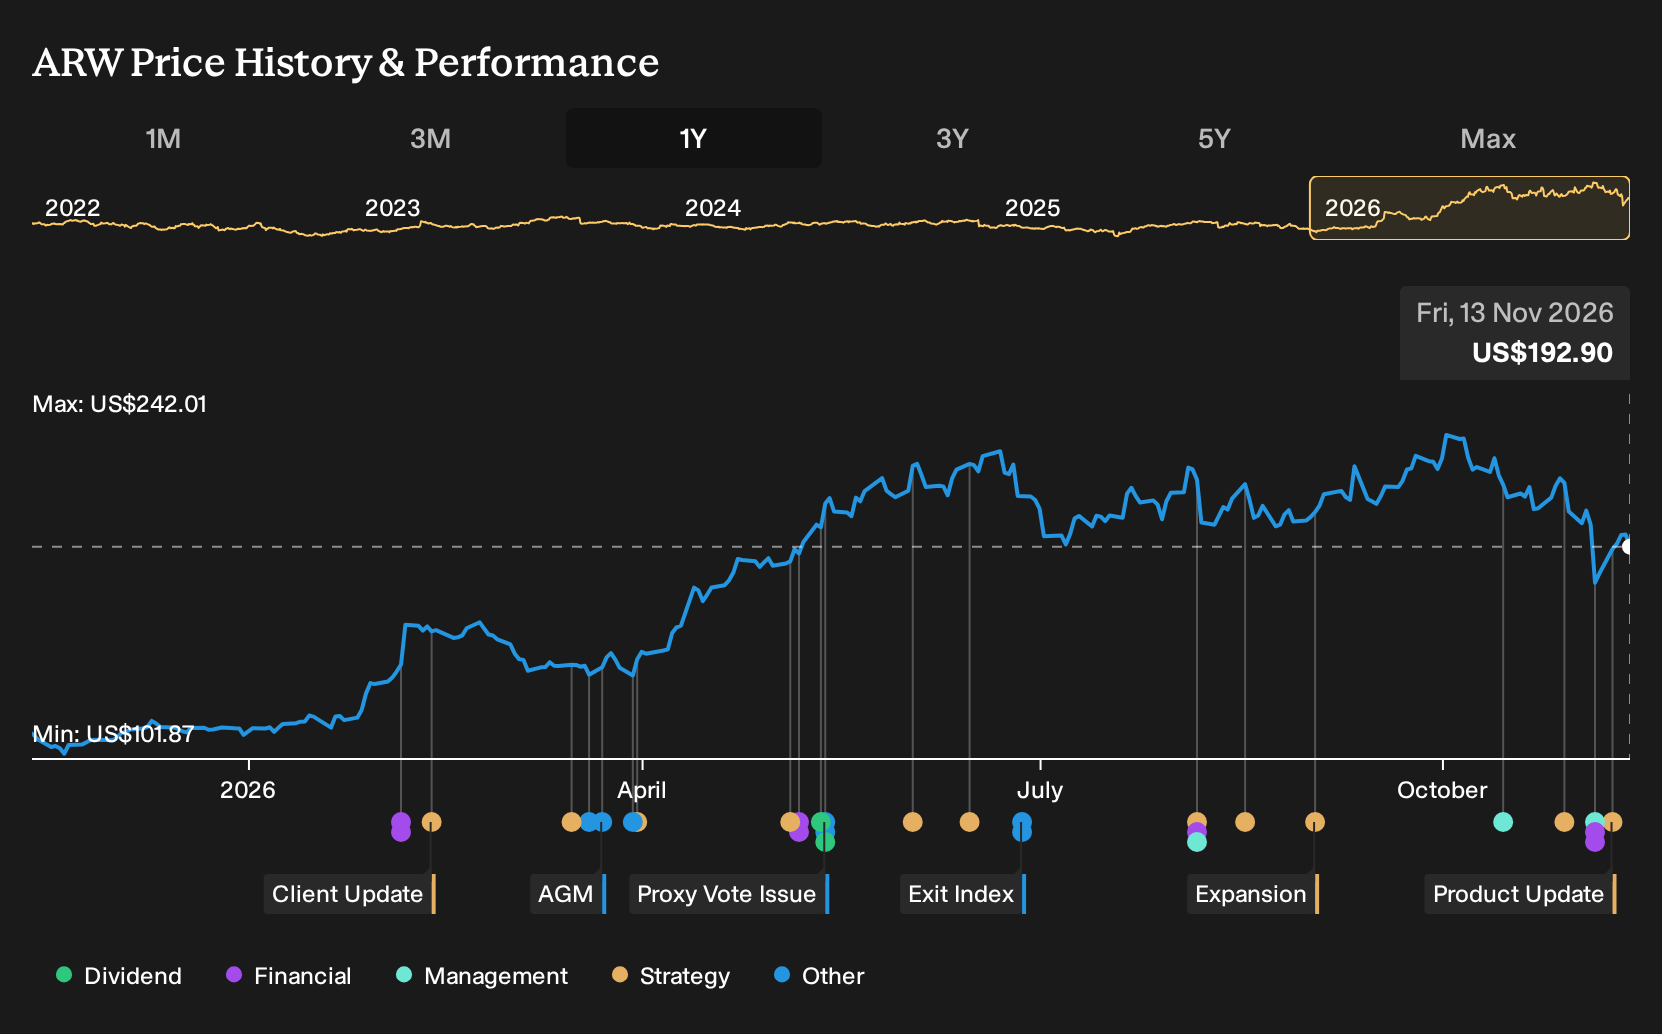
If you only skimmed the early 2025 debate about Arrow Electronics, with one side worrying about semiconductor corrections and another eyeing margin upside, the past year’s payoff might look almost unreal. Investors who held Arrow Electronics over the past year are up 78.3%, including dividends. If you had been deciding on 13 November 2025, with revenue pressures and inventory risks on full display, what information really justified taking that ride?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
This theme extends beyond Arrow Electronics. See which of 53 AI infrastructure stocks may still merit a closer look.
The Two Stories Arrow Electronics Investors Had To Choose Between
The shares cost US$110 at the start of the period, so you were deciding whether Arrow Electronics was modestly mispriced or set for a tougher stretch.
The bullish narrative saw Fair Value at US$117, about 6% above the start price. It leaned on electrification and connected infrastructure demand supporting electronics content across industrial, transportation, and aerospace customers.
The bearish view put Fair Value closer to US$98, around 11% below the start price. It focused on semiconductor industry corrections and high inventory levels that could strain revenue, earnings, and cash flow.
What The Arrow Electronics Results Actually Tested
Arrow Electronics then reported Q3 2026 revenue of US$10.7b and net income of US$318.4m, compared with US$7.7b and US$109.2m a year earlier. Net margin moved from 1.4% to 3.0%. This aligned more closely with the bullish story about higher-margin services, while still leaving semiconductor cyclicality and inventory worries from the cautious case as open questions. Overall, the evidence cut both ways.
The key assumption investors needed to watch was margin resilience. For any similar distributor, it may be useful to track how net margin and the mix of value-added services evolve across several quarters relative to what the original thesis anticipated.
What Arrow Electronics' Rally Already Prices In
After a 78.3% gain over the past year, Arrow Electronics now trades at US$193. The bullish analyst narrative on Simply Wall St still places its fair value above the current price, tying that view to scaled services, AI data center work, and cloud platforms layered on top of distribution.
On this reading, a buyer today is effectively assuming that higher margin supply chain and engineering agreements, plus recurring software and cloud usage, will keep compounding faster than the market currently credits.
"Arrow Electronics is scaling higher margin supply chain services for large hyperscalers, including programs where Arrow designs, builds and tests AI data center infrastructure and manages consigned inventory, AR and AP flows. This could keep lifting operating margins and earnings quality as more multi year agreements are signed."
One Narrative disagrees with today's price. → See where this Narrative says Arrow Electronics should trade
How Could You Get There Earlier?
The story behind this run has already been told. The next one could be taking shape somewhere else. Where could you start looking before it becomes the headline?
- Company 1 - 36% below our estimate - builds electrical and communications systems for massive hyperscale data center projects.
- Company 2 - 39% below our estimate - expands an app-driven coffee network using delivery, promotions and rapid new locations.
- Company 3 - 46% below our estimate - grows technology-focused small business lending while adding digital checking and payment tools.
That is three of the list. See all 32 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com