


EN
Axsome Therapeutics (AXSM) Stock May Be Undervalued Following Strong Revenue Growth
Axsome Therapeutics has turned into a very different stock over the past few years, and the latest share move puts fresh focus on what investors are really paying for. With the price now reflecting years of anticipation around its neurology portfolio, the open question is whether the current valuation is adequately backed by the company’s sales.
- Over the past 5 years the stock has gained about 295.8%, which puts a lot of past optimism into today’s market value and makes the link between price and underlying revenue more important than ever.
- Management is leaning heavily on Auvelity and a broader neuroscience pipeline to support future product sales. This can influence how much investors are willing to pay for each dollar of current and expected revenue.
- Your read on Axsome Therapeutics is one view; the desks covering it have another. See what analysts think Axsome Therapeutics's shares could be worth.
For investors, the debate is whether Axsome Therapeutics’ recent share price reflects a level of sales that can reasonably justify today’s valuation multiples.
If you are weighing Axsome Therapeutics mainly through the lens of its sales, it can help to compare it with a wider field that meets clear criteria using 32 high quality undervalued stocks.
Does Axsome Therapeutics Look Undervalued on Sales?
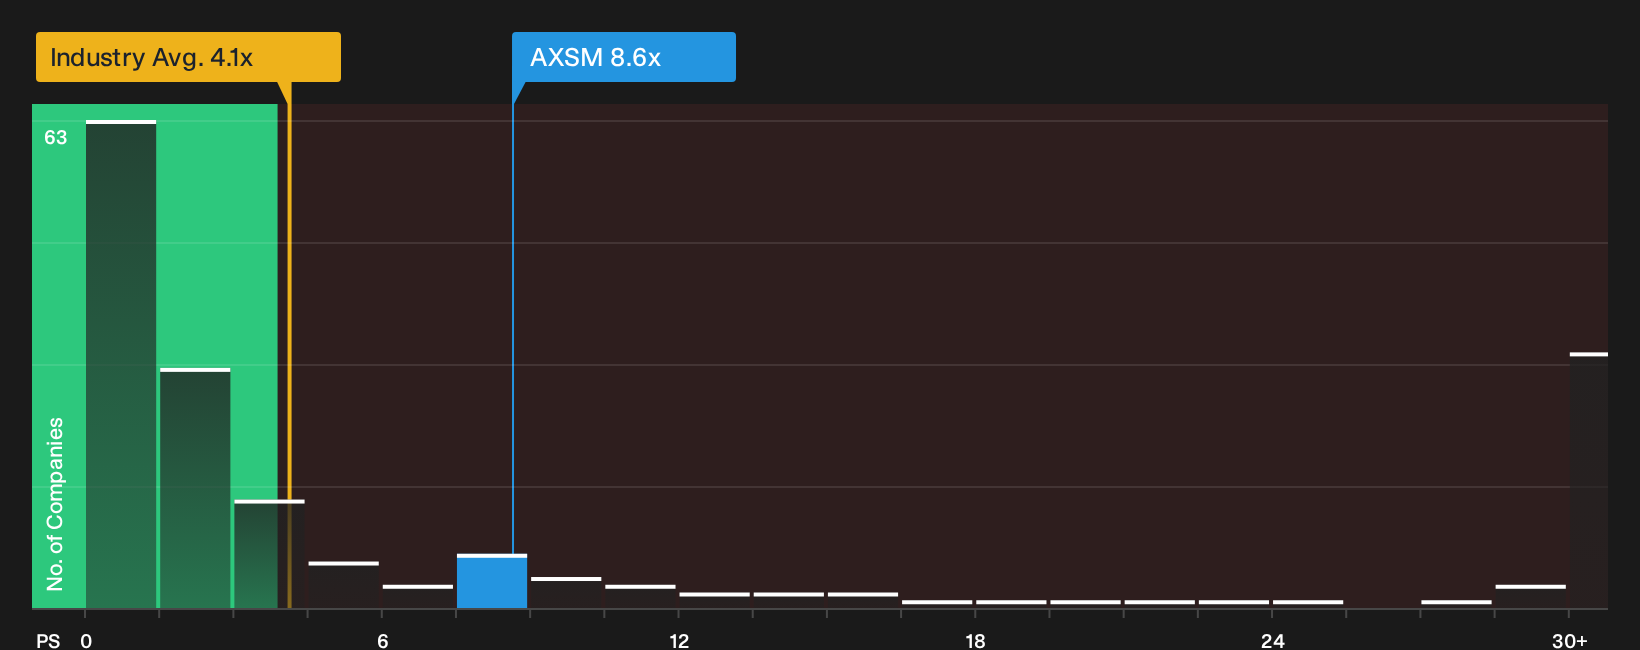
P/S is a useful yardstick for Axsome Therapeutics because the business is still loss making and investors are effectively paying for revenue rather than earnings. On this measure, the stock trades on a P/S ratio of 8.6x, compared with a pharmaceuticals sector average of 4.1x and a peer group around 9.9x. That places Axsome’s valuation at a premium to the wider industry while sitting below the narrower set of similar companies.
The Fair Ratio, which reflects what investors might expect to pay given Axsome Therapeutics’ growth profile, margins, size and risk, is above the current 8.6x. Based on this framework, the shares screen as undervalued. Because management recently flagged a revenue run rate targeting more than US$1b, the gap between the present multiple and that Fair Ratio suggests the market is not fully pricing in the sales profile implied by those ambitions. Explore the numbers behind Axsome Therapeutics's P/S valuation.
The Axsome Therapeutics Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Axsome Therapeutics valuation puzzle leaves off. They spell out which future paths for growth, margins and earnings would need to unfold for the stock to be worth materially more or less than today. Each scenario ties a fair value to a particular mix of potential catalysts and key risks, so you can track over time which version of Axsome Therapeutics' story is actually taking shape on the Community page.
One of the top narratives on Axsome Therapeutics: 48% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"Diverse CNS product portfolio and late-stage pipeline position company to capitalize on global demand trends while reducing dependence on single products..."
Discover why this Narrative puts Axsome Therapeutics at 48% undervalued.
The Axsome Therapeutics story also depends on who is steering it
Share price and sales only tell part of the Axsome Therapeutics story, because the executives setting priorities and the way they are rewarded can shape how that valuation evolves over time. See who runs Axsome Therapeutics and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com