


EN
How Investors May Respond To NCC (OM:NCC B) Major Contract Wins
- NCC reported Q3 2026 results and announced several new contracts, including a SEK 300 million artillery regiment base in Kristinehamn, a SEK 260 million data center groundwork project in Pori, Finland, and approximately SEK 290 million in new facilities at the Skogome correctional facility in Gothenburg.
- The cluster of government backed and industrial projects expands NCC's construction workload across defense, data infrastructure and correctional housing. This may reshape how investors view the quality, duration and mix of its Swedish and Nordic order book.
- We will now look at how NCC's investment narrative is affected by the new SEK 300 million Bergslagen artillery regiment base.
Scan construction stocks benefiting from the same mix of government backed infrastructure, defense and data center demand as NCC with our hand picked 43 power grid technology and infrastructure stocks.
NCC Investment Narrative Recap
To own NCC, an investor needs to believe that a more focused contracting group with solid Nordic infrastructure demand can offset weaker parts of the portfolio. The analyst consensus Narrative on Simply Wall St leans on order backlog quality and an asset light profile after the planned NCC Industry divestment. The new artillery, data center and prison projects support that contracting focus but do not change the need for better profitability.
The main near term catalyst still sits in execution and pricing on the core contracting backlog, as well as progress on Industry divestment terms. Key risks remain legal dispute costs, limited EBIT from Property Development and an uncovered 4.69% dividend, which Q3 2026 earnings and these orders do not solve on their own.
The Bergslagen artillery regiment base in Kristinehamn looks most relevant here. It is a SEK 300 million partnering agreement with the Swedish Fortifications Agency, tied to a broader SEK 6.5b government investment decision over coming years. This first subproject includes excavation, rock blasting and crushed stone production largely on site, which keeps materials self supplied and reduces transport exposure.
For an investor focused on catalysts, this contract tests NCC’s ability to deliver complex, defense related work while maintaining contracting margins that the analyst consensus Narrative on Simply Wall St views as central. Operational risks include schedule, environmental and cost control across large excavation volumes. Successful execution could support perceptions of backlog quality without directly addressing slower property sales or dispute expenses.
NCC's narrative projects SEK 44.0b in revenue and SEK 1.6b in earnings by 2029, based on analysts assuming revenue will decrease by 6.6% per year and earnings would need to rise from SEK 78.0m today to SEK 1.6b, which represents a very large step up from current earnings.
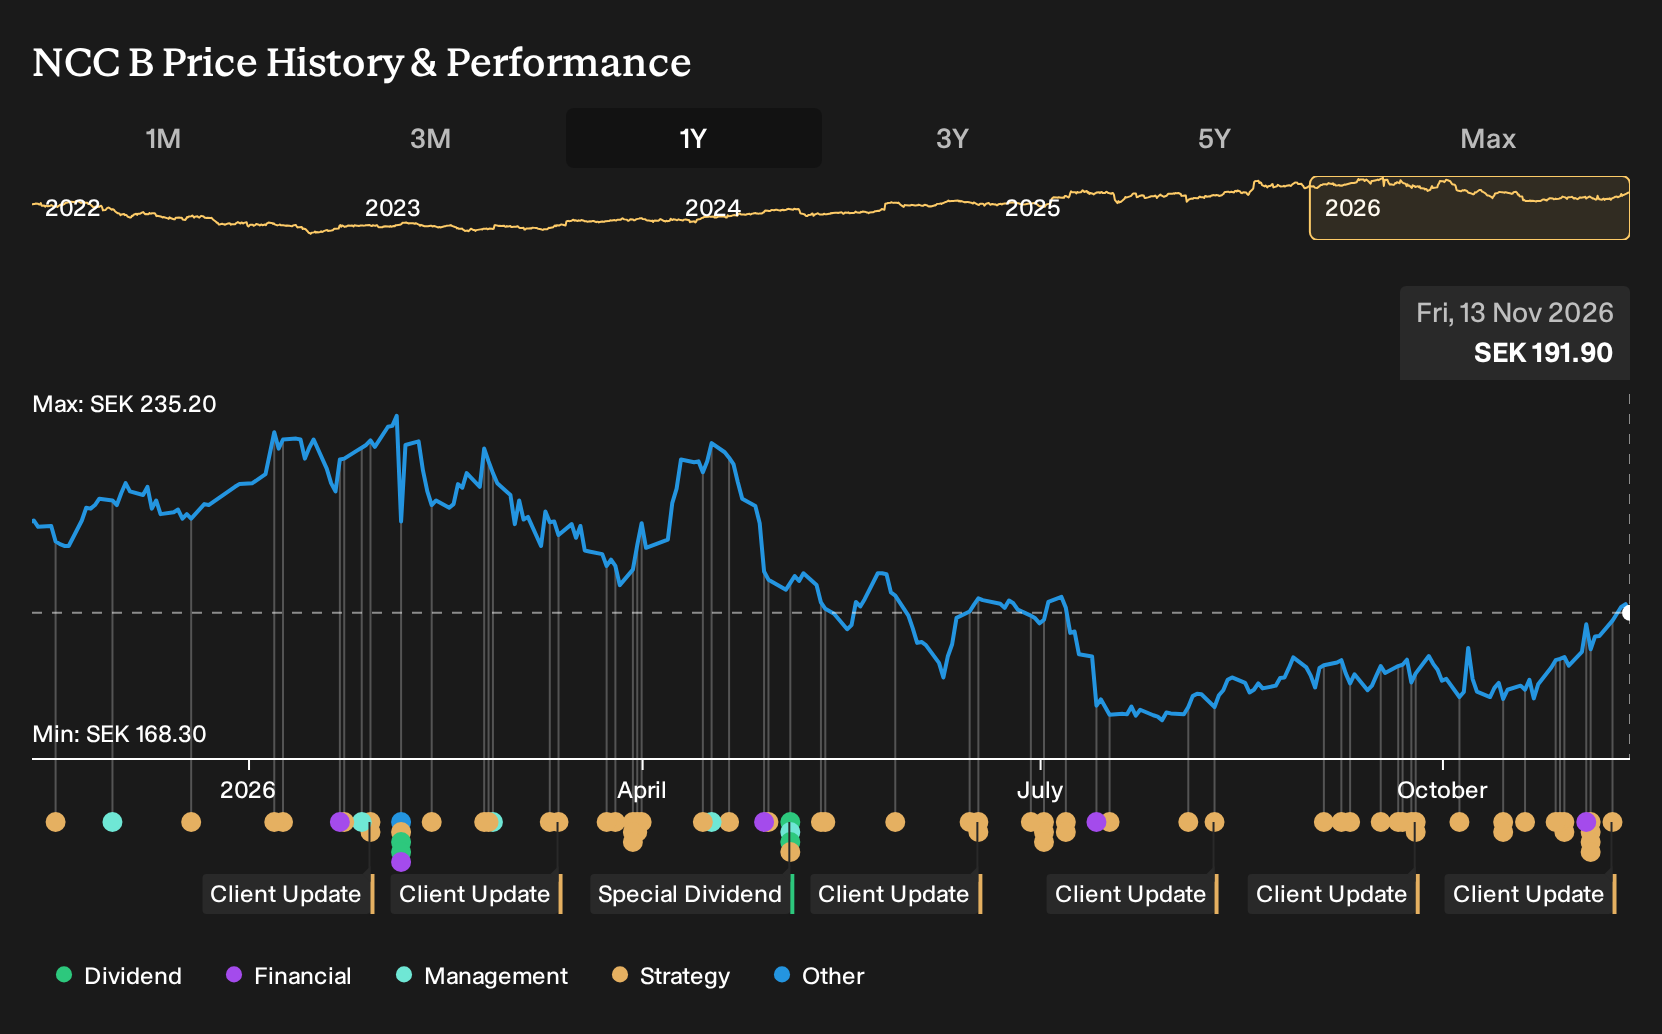
Uncover why NCC's fair value indicates a 7% potential upside to its current price before other investors close the gap.
Exploring Other Perspectives
Some of the most optimistic NCC analysts were already assuming revenue of about SEK 46.5b and earnings of SEK 1.5b by 2029, tied to a richer mix of public and social infrastructure projects. You can treat the new Bergslagen regiment base as a live test of that higher margin contracting story and explore how views might shift from here.
Explore 2 other NCC fair value estimates, including one that suggests as much as 12% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your NCC research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for NCC. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NCC's overall financial health at a glance.
Looking For More Ideas Beyond NCC?
If the NCC story has sharpened how you think about contracts, risk and balance sheets, it can be useful to test that same lens on a wider set of companies using the Simply Wall St Screener.
- For readers hunting for mispriced quality, start with 198 high quality undervalued stocks that pair solid fundamentals with prices that may not fully reflect them.
- If income reliability matters most, focus on dependable payers through 220 dividend fortresses that filter for higher yielding businesses.
- For a calmer ride through market swings, prioritise resilience and capital strength via our 210 resilient stocks with low risk scores that screen for sturdier balance sheets and lower risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com