


EN
Does Raised Guidance Change The Bull Case For Corpay Stock (CPAY)?
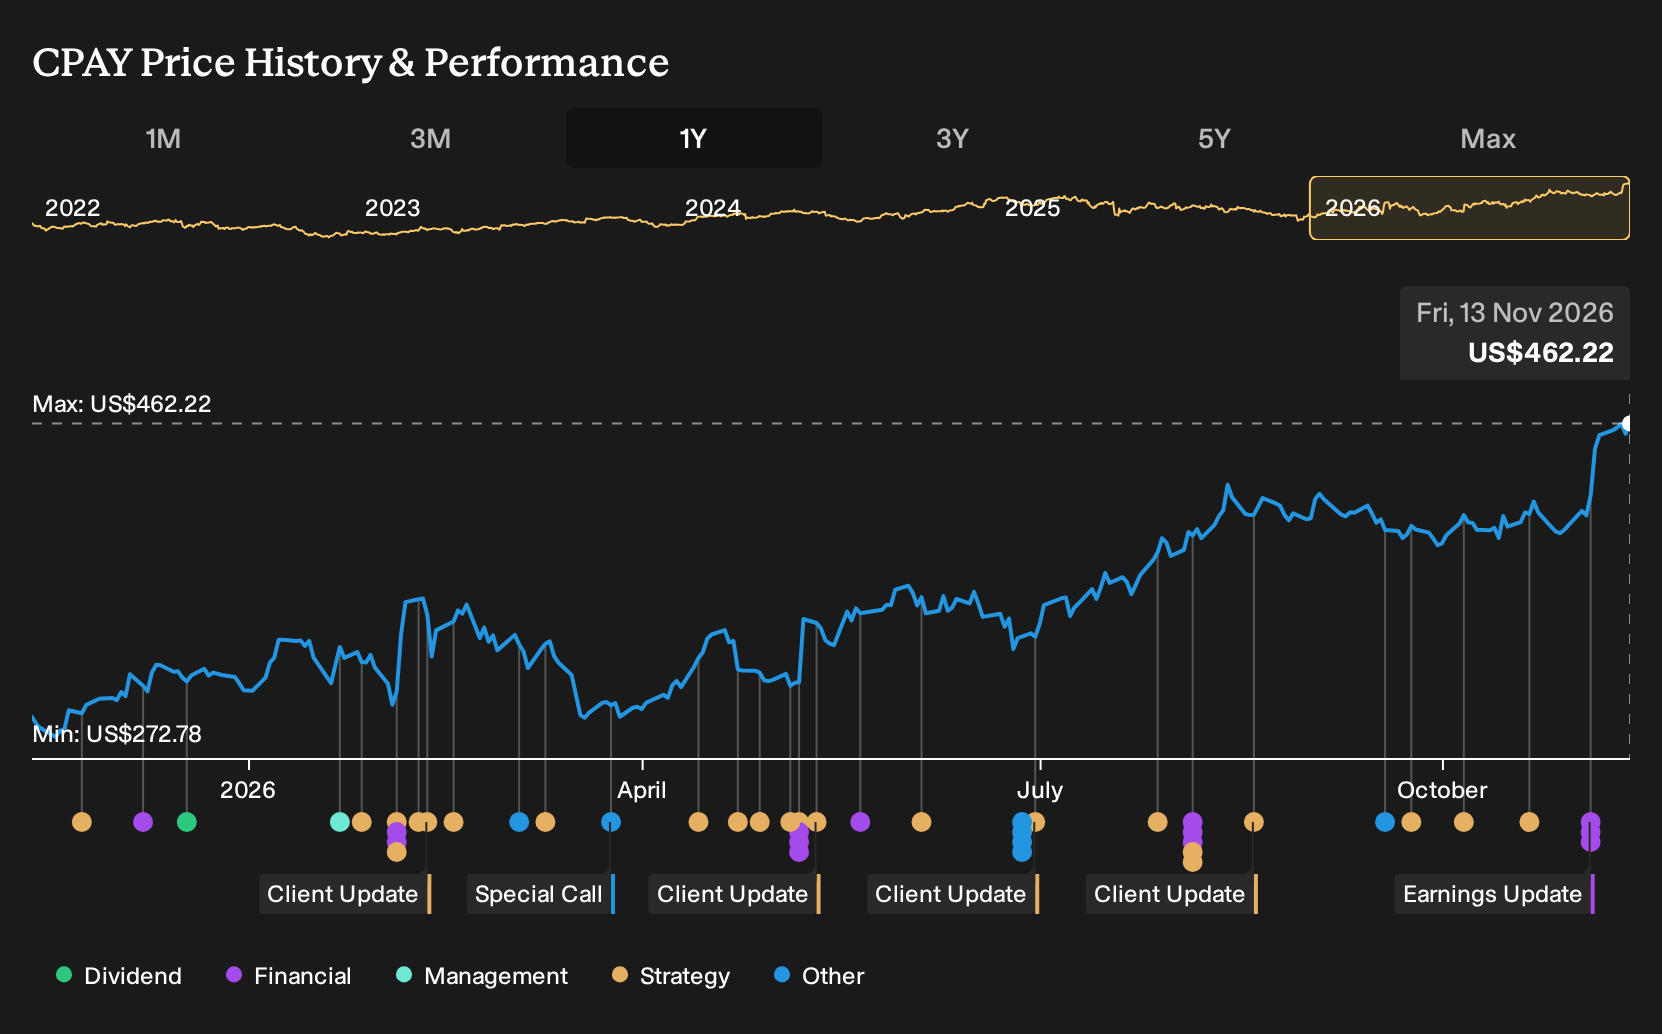
- Corpay reported third quarter 2026 sales of US$1,381.93 million and net income of US$378.42 million, with basic EPS from continuing operations of US$5.73, and also issued guidance for fourth quarter revenue of about US$1.37b.
- The company raised full year 2026 targets for total revenue to a range of US$5.34b to US$5.36b and net income per diluted share to a range of US$20.03 to US$20.23, which reflects management’s stated view of Corpay’s operating momentum and earnings power.
- Attention now turns to how Corpay’s raised full year earnings outlook may reshape the investment narrative built around corporate payments and capital deployment.
Corpay Investment Narrative Recap
To own Corpay, you need to believe the payment platforms across corporate, vehicle, and lodging can keep converting higher transaction activity into sustained earnings, even as parts of the portfolio are simplified. The raised 2026 guidance and strong third quarter figures support that operating story rather than changing it. The near term swing factor remains execution on corporate payments growth and cross border volumes.
The biggest risk still sits in regulatory and legal constraints around Vehicle Payments and any extra compliance costs that squeeze net margins. Recent results do not remove that overhang. They do, however, give Corpay a little more breathing room if organic growth in segments like Lodging or cross border slows.
The most relevant update for this story is the raised full year 2026 guidance. Management now projects total revenue between US$5.34b and US$5.36b and net income per diluted share between US$20.03 and US$20.23. That uplift aligns with the analyst consensus Narrative on Simply Wall St, which already leans on higher earnings and capital deployment as key supports.
For you as a shareholder, this sharper earnings outlook ties directly into the main catalysts. Stronger profit gives Corpay more capacity to handle legal settlements, invest in cross border infrastructure, and potentially pursue corporate payments deals using its available capital. The risk side is that expectations rise with the new numbers, so any stumble on margins or segment level performance may be judged more harshly.
Corpay's narrative projects US$6.7b revenue and US$2.1b earnings by 2029. This aligns with analyst assumptions for 8.8% yearly revenue growth and implies an earnings increase of about US$900m from current earnings of US$1.2b.
Uncover why Corpay's fair value indicates a 6% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span from just US$492 to about US$633.9b, which shows how far apart private investors can be on Corpay. Use that spread as a prompt to test your own thesis against both the settlement risk around Vehicle Payments and the potential catalysts in cross border and payables automation.
Explore 2 other Corpay fair value estimates, including one that suggests as much as 137140077860% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Corpay research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Corpay. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Corpay's overall financial health at a glance.
Looking for more investment ideas beyond Corpay?
Once you have a handle on Corpay, it can help to compare it with other opportunities that match your risk level, income needs, or balance sheet preferences. The Simply Wall St Screener is built for exactly that kind of side by side work, letting you filter for qualities that matter most to you.
- If you want income to play a bigger role in your portfolio, scan a focused set of higher yield payers through 6 dividend fortresses that aim to combine strong payouts with resilience.
- For readers who care first about financial sturdiness, filter for companies with healthier leverage and liquidity profiles using the list of solid balance sheet and fundamentals (24 results) to see which ones clear those quality hurdles.
- If you are hunting for potential mispricing, cast a wider net across fundamentally strong businesses with room for the market to catch up by running the 32 high quality undervalued stocks and seeing what surfaces alongside Corpay.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com