


EN
Agricultural Bank Of China (SEHK:1288) Could Be 3% Undervalued After Earnings Optimism
Agricultural Bank of China (SEHK:1288) has drawn fresh attention after completing a CNY 50b fixed income offering, issuing 1.75% callable notes due 2036. The transaction adds a new layer to its funding mix.
For investors watching Agricultural Bank of China’s share price, the momentum has been building, with a 17.64% 3 month share price return and a 17.84% year to date move. The 1 year total shareholder return of 19.54% and very large 3 and 5 year total shareholder returns point to a stronger long term payoff as recent earnings optimism and valuation appeal feed into sentiment.
Scan opportunities beyond Agricultural Bank of China by reviewing hand-picked value ideas in the 198 high quality undervalued stocks. These ideas pair solid balance sheets with cash flows the market may be underpricing.
For Agricultural Bank of China, the recent share price run and the upgraded earnings outlook tell a similar story, yet sentiment can move faster than fundamentals. How much of this move does the current valuation actually justify?
Most Popular Narrative: 3% Undervalued
Agricultural Bank of China last closed at HK$6.87, which sits just below the analyst consensus Narrative fair value of about HK$7.12. This figure is based on an 8.17% discount rate and detailed revenue and earnings forecasts from the analyst consensus Narrative on Simply Wall St.
Strong policy support for rural revitalization and agricultural modernization, combined with Agricultural Bank of China’s extensive county level network and continued growth in county loans and deposits, positions the bank to capture ongoing government directed credit demand and fee income, which can support revenue and earnings.
Urbanization and a growing middle class are driving increased demand for personal and commercial banking products, reflected in Agricultural Bank of China’s large base of around 900 million personal customers and leading personal deposits and loans, which can support future fee income and core revenue.
See why 21 investors see Agricultural Bank of China as 3% undervalued.
Result: Fair Value of HK$7.12 (UNDERVALUED)
Still, the narrative can unravel if hidden bad loans across the system force Agricultural Bank of China to raise credit costs, or if fast growing green and tech lending drags on margins.
Find out about the key risks to this Agricultural Bank of China narrative.
Another View: What Multiples Say About Agricultural Bank of China
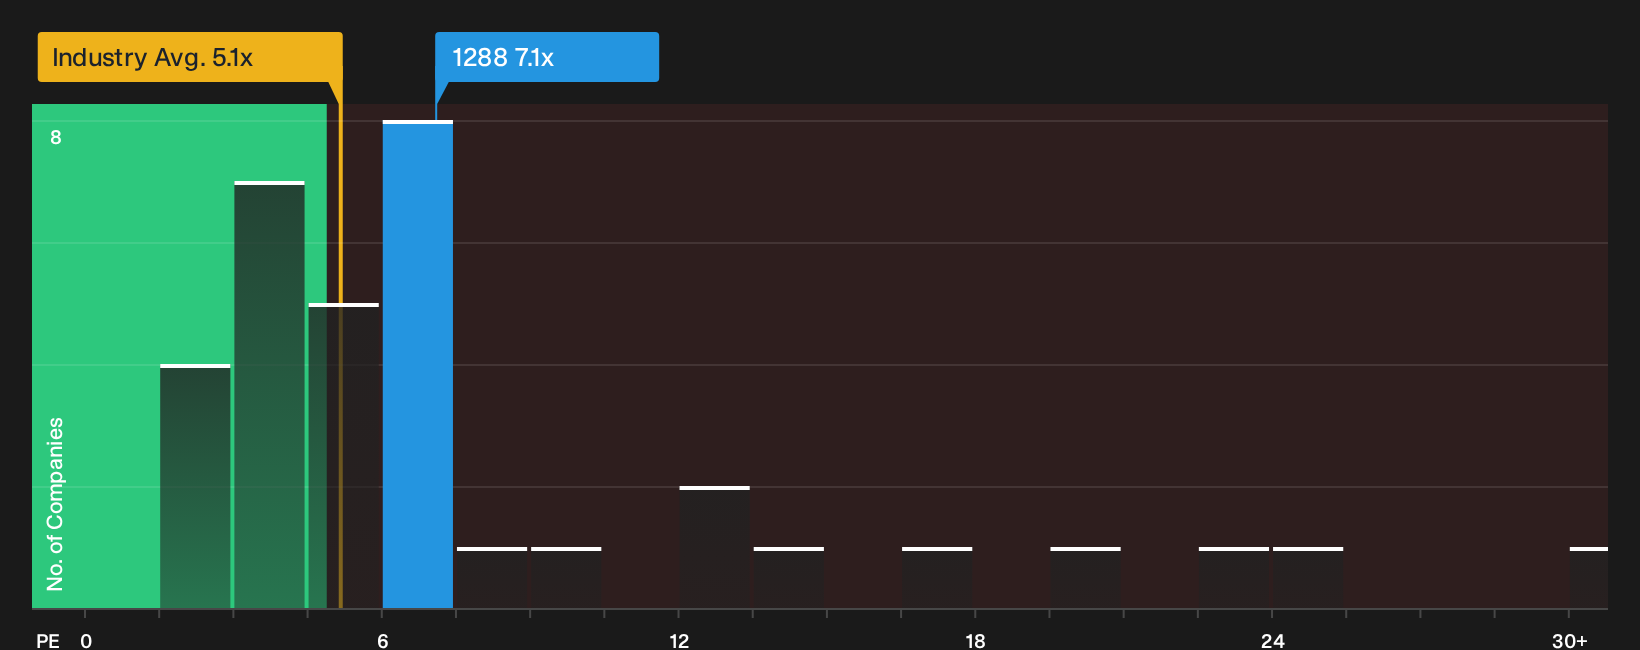
Analysts see Agricultural Bank of China as modestly undervalued against their HK$7.12 fair value, yet the P/E of 7.1x runs slightly higher than both peers at 6.9x and the Hong Kong Banks sector at 5.1x. It still sits under a fair ratio of 7.5x. That mix of mild premium against rivals but room to move toward the fair ratio raises a simple question for investors: Is the margin of safety strong enough for your taste, or is the risk of the multiple compressing the bigger story?
Before leaning on this kind of comparison, it is worth stress testing the earnings assumptions that feed into it. Then ask whether a higher or lower future P/E feels realistic for Agricultural Bank of China based on your own expectations rather than just the consensus. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Feeling encouraged by the tone around Agricultural Bank of China or a bit cautious about how much optimism is already priced in? Move quickly and review the underlying data, then pressure test whether the positives justify your own stance by weighing the 4 key rewards.
Looking for more investment ideas beyond Agricultural Bank of China?
If you stop with one opportunity, you miss the bigger picture. Use the Simply Wall St screener to hunt for other potential fits for your watchlist.
- Scan for resilient payers that aim to combine income with staying power by reviewing our hand picked 220 dividend fortresses today.
- Hunt for financially robust businesses by checking the list of solid balance sheet and fundamentals (198 results) that may handle shocks better than most.
- Unearth underfollowed opportunities with strong fundamentals through the focused 559 high quality undiscovered gems before the crowd gets interested.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com