


EN
Revenue Surge Might Change The Case For Bitdeer Stock As It Expands Into AI Cloud
- Bitdeer Technologies Group reported third quarter 2026 sales of US$320.75 million, with a net loss of US$125.5 million, while September operations included 86.4 EH/s of hash rate under management and 3,855 Bitcoin mined.
- The company highlighted an 89% year over year revenue increase and a pivot toward long term AI cloud infrastructure contracts, backed by about US$7.6b of expected contracted revenue and largely non dilutive project financing.
- We will now look at how Bitdeer’s AI focused contract backlog and revenue surge could reshape the longer term investment narrative.
Scan beyond Bitdeer Technologies Group and compare this AI infrastructure pivot with other data center and chip beneficiaries using our hand picked 53 AI infrastructure stocks.
Bitdeer Technologies Group Investment Narrative Recap
To own Bitdeer Technologies Group, you need to be comfortable with a business that is still loss making while pouring capital into AI focused infrastructure. The analyst consensus Narrative on Simply Wall St leans heavily on the idea that the AI cloud and colocation backlog eventually outweighs the drag from Bitcoin mining and high upfront capex. The near term swing factor is clear: execution on energizing contracted AI capacity and turning that US$7.6b backlog into recurring cash flow.
The biggest near term risk is that rising investment needs run ahead of funding and cash generation. Bitdeer has less than one year of cash runway and is carrying around US$1.8b of long term debt plus recent equity dilution. The latest quarter shows record sales but also a wider net loss, which keeps pressure on financing, project returns and mining exposure if economics stay weak.
The third quarter earnings release is the announcement that matters most here. Bitdeer posted US$320.75 million of sales for the quarter and a net loss of US$125.5 million. Over the first nine months of 2026, revenue reached US$738.46 million while losses came to US$377.31 million. Those figures underline a company growing its top line while still burning cash.
For you as a shareholder, that update frames the catalyst and risk in one place. The AI cloud contracts and colocation deals, including Tydal and Malaysian campuses highlighted in earlier commentary, need to move from backlog into cash flow fast enough to support debt, capex and limited runway. Until that happens, ongoing losses, mining volatility and reliance on higher risk funding remain central to the Bitdeer Technologies Group story.
Bitdeer Technologies Group’s analyst narrative points to forecast revenue of US$3.2b and projected earnings of US$398.8 million by 2029. This outlook is anchored to an assumed 58.4% yearly rise in revenue and an earnings shift of about US$627 million from current earnings of a US$228.6 million loss.
Uncover why Bitdeer Technologies Group's fair value indicates a 290% potential upside to its current price that may not last much longer.
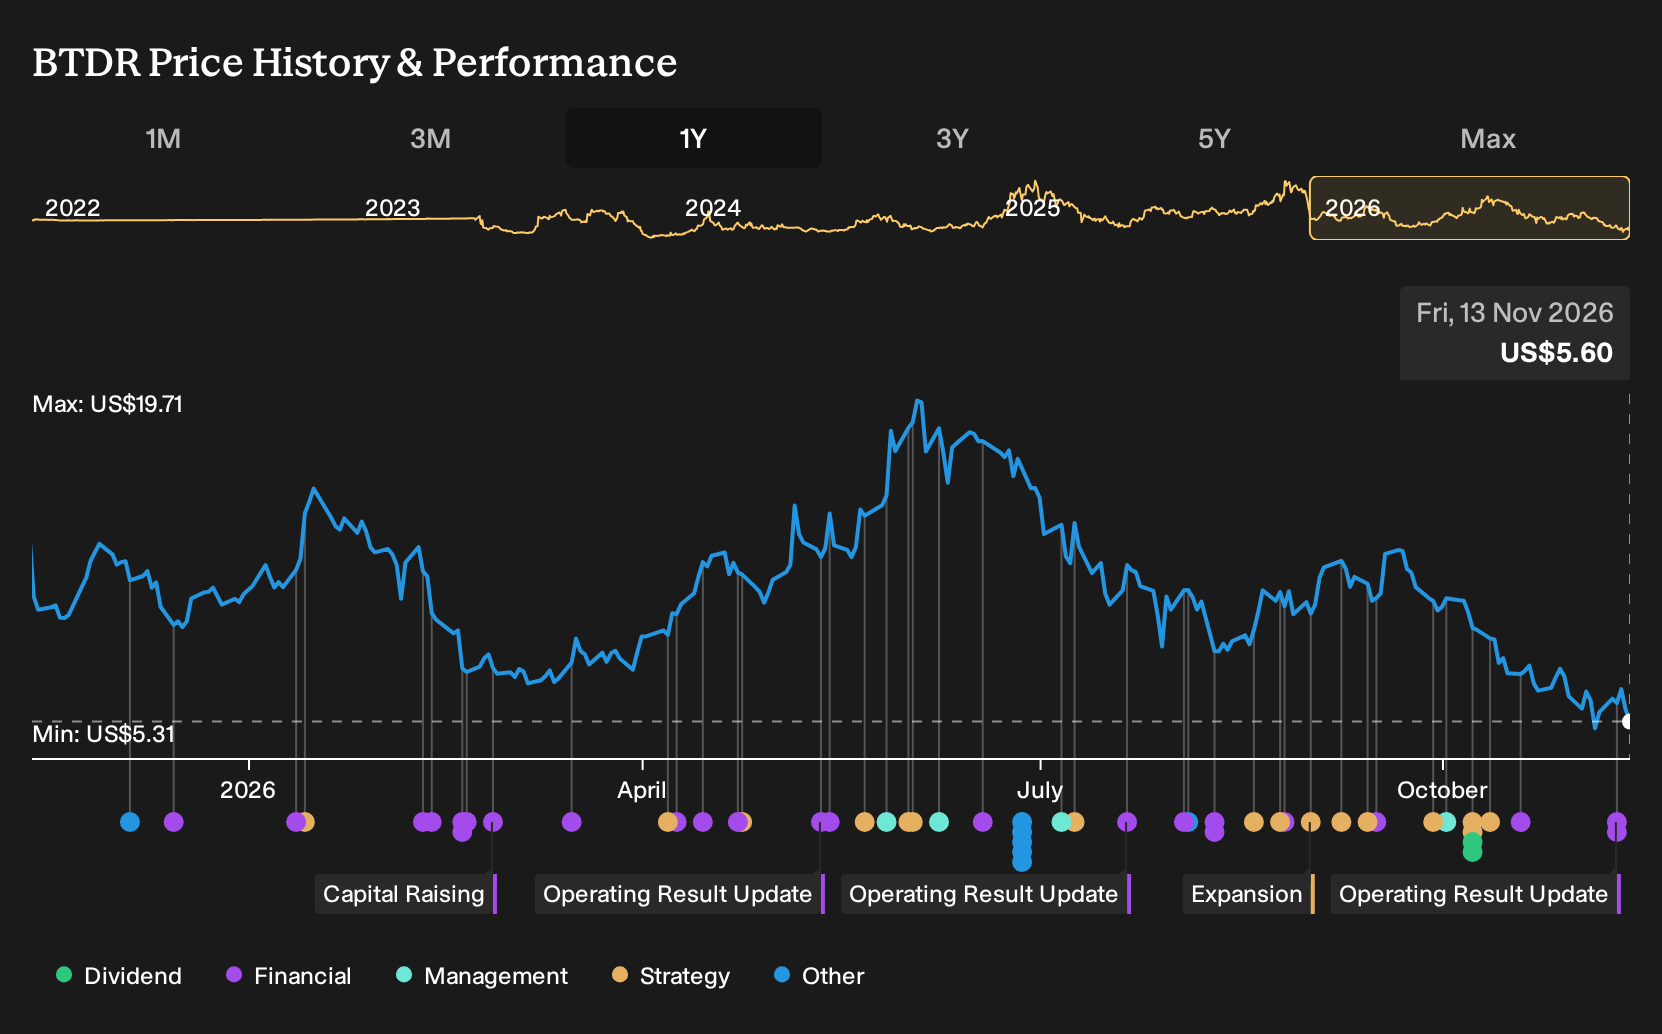
Exploring Other Perspectives
Some of the most bullish analysts frame Bitdeer Technologies Group’s Tydal AI colocation hub as the real swing factor, not the Bitcoin side at all. Before this earnings release, they were pencilling in revenue of about US$6.1b and earnings of roughly US$729.8 million by 2029. Those projections had not yet absorbed this latest mix of higher sales and larger losses, so you should expect opinions to move and explore how that more optimistic story may change from here.
Explore 4 other Bitdeer Technologies Group fair value estimates, including one that suggests as much as 899% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Bitdeer Technologies Group research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Bitdeer Technologies Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bitdeer Technologies Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Bitdeer Technologies Group?
If Bitdeer Technologies Group has sharpened your focus on risk, balance sheets and long term potential, it can help to line it up against a wider watchlist. Use the Simply Wall St Screener to build a shortlist of alternatives that fit your return targets and risk tolerance, then compare how each business stacks up on fundamentals before you commit fresh capital.
- For investors hunting for resilient operators with lower risk profiles, start by scanning a curated set of 31 resilient stocks with low risk scores that may better match a steadier approach.
- If reliable cash generation and strong finances matter most to you, build a comparison list from the list of solid balance sheet and fundamentals (24 results) and see how those companies manage leverage and liquidity.
- When you want quality but do not necessarily want to pay full price, broaden your radar with a hand picked group of 32 high quality undervalued stocks that currently screen as potentially mispriced on fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com