


EN
Is Biglari Holdings (BH.A) Overvalued Following Its Third Quarter Results?
Biglari Holdings (BH.A) just released third quarter and nine month results through September 30, 2026, giving investors fresh numbers on sales, revenue and profitability across its restaurant, insurance, energy and media operations.
The recent third quarter profit update comes as Biglari Holdings trades at US$1,806.09. The stock has logged a 14.75% 7 day share price return but is sitting about 5% lower over the past month and quarter. The 1 year total shareholder return of 18.43% and the very large 3 and 5 year total shareholder returns point to long term holders still being well rewarded despite shorter term volatility around earnings and valuation expectations.
Scan beyond Biglari Holdings and see how other multi segment operators are reacting to this earnings season with our curated 20 high quality undiscovered gems.
Biglari Holdings has swung from loss to profit and the share price is still down over the past month, which raises a sharper question. Is the current discount a sensible safety margin, or an overreaction to past worries?
Preferred Price-to-Sales of 2.9x: Is it justified?
On Simply Wall St's numbers, Biglari Holdings is trading on a P/S of 2.9x, which looks rich beside both hospitality peers and the wider US market when set against a last close of $1,806.09. That gap invites a closer look at whether investors are paying up for the right reasons or simply accepting a premium because the stock has delivered very strong multi year returns.
The P/S ratio compares the market value of Biglari Holdings to the $417.94m of revenue it generated, so it tells you how many dollars investors pay today for each dollar of recent sales. For a group that mixes restaurants, insurance, energy and media, this measure helps you see how the market weighs those different activities into a single price tag.
Context matters here. BH.A is currently unprofitable, reports a loss of $23.44m, has a declining earnings trend of 15% per year over five years, and carries only higher risk funding sources through external borrowing. At the same time, shareholders have enjoyed an 18.43% 1 year total return and very large 3 and 5 year gains, which suggests the premium multiple may be reflecting confidence in management, board experience and the diversified structure rather than recent profit performance.
The comparison with peers is stark. BH.A's P/S of 2.9x is more than double the US Hospitality industry average of 1.4x and sits well above the peer group average of 0.9x, so investors are paying a much higher revenue multiple than is typical for the sector. That is a strong signal that the market is assigning a premium to Biglari Holdings relative to its industry, even though the underlying business is currently loss making.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-sales of 2.9x (OVERVALUED)
Still, that premium can unwind quickly if Biglari Holdings continues to report losses or if any major segment underperforms and weakens overall investor confidence.
Find out about the key risks to this Biglari Holdings narrative.
Another view on Biglari Holdings from the SWS DCF model
A different lens tells a sharper story. Our DCF model estimates the future cash flow value of Biglari Holdings at $589.65 per share, compared with the current $1,806.09 price. That points to the stock trading well above this fair value estimate. Which signal should you place more weight on: the market or the model?
Look into how the SWS DCF model arrives at its fair value.
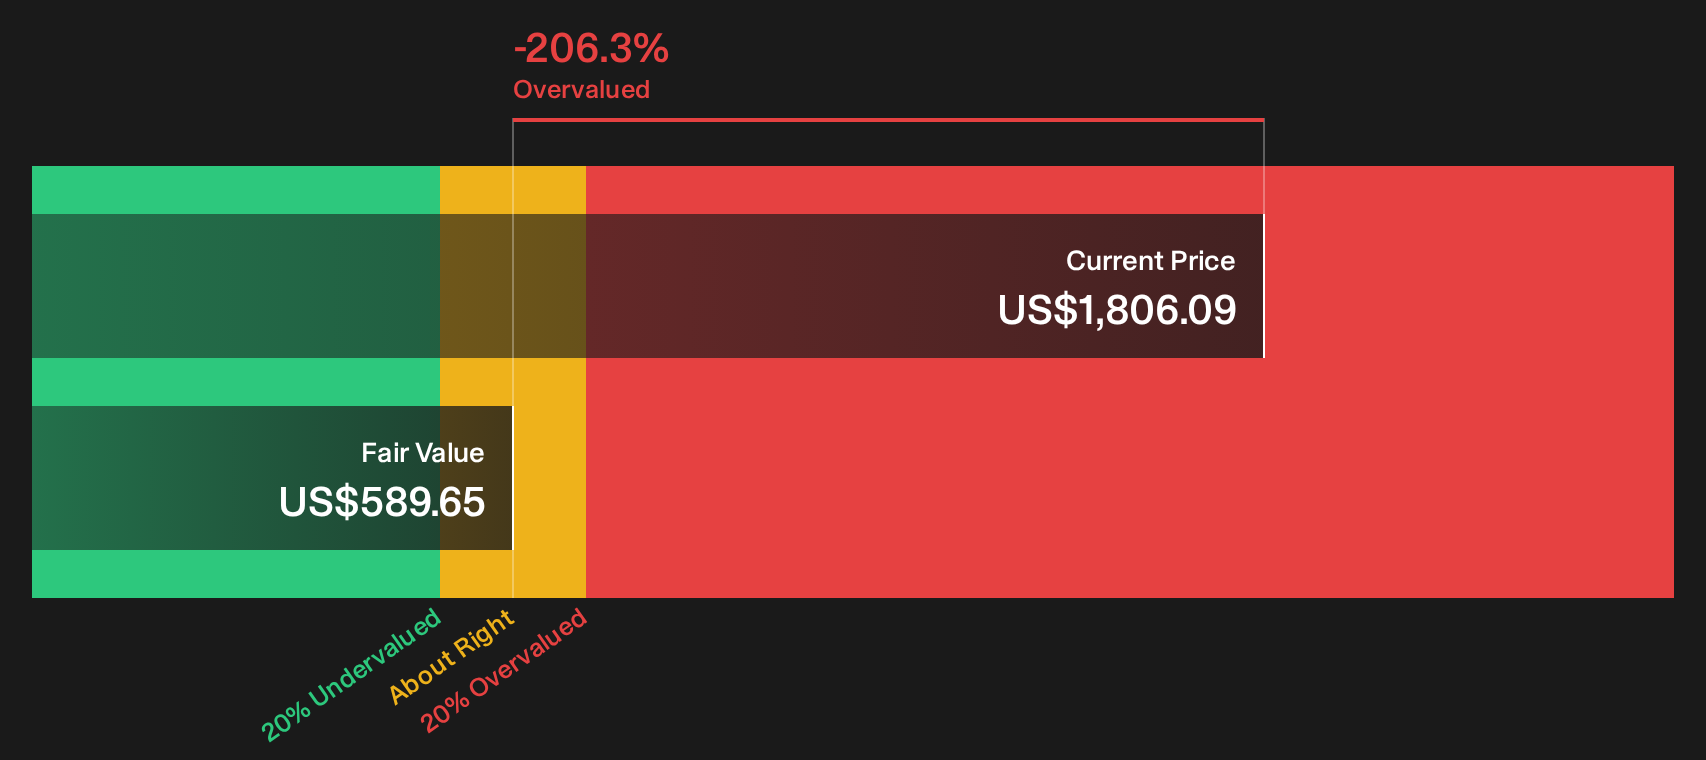
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Biglari Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Biglari Holdings is clearly mixed, which makes this one of those moments where your own homework really matters. Act quickly and stress test the story against the detailed risk flags, and weigh what the market might be missing by digging into the 1 important warning sign.
Looking for more investment ideas beyond Biglari Holdings?
If Biglari Holdings has sharpened your thinking, do not stop here. Broaden your watchlist now, or you risk missing opportunities that better fit your goals.
- Target stronger quality at a fairer tag by scanning our hand picked 32 high quality undervalued stocks that align solid fundamentals with attractive pricing.
- Build a steadier income stream by reviewing a focused group of 6 dividend fortresses that prioritise yield alongside financial resilience.
- Guard your capital with a curated 31 resilient stocks with low risk scores that keeps the spotlight on resilience and balance sheet strength.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com