


EN
Is CONMED (CNMD) Fully Valued As Its Surgical Growth Story Gains Traction?
CONMED (CNMD) has drawn investor attention after recent share moves, with the stock last closing at US$50.59. That price anchors any fresh look at the medical technology group’s value and risk profile.
Over the past month, CONMED’s 12.6% share price return and 24.85% year to date gain contrast with a 20.34% total shareholder return over one year and deep three and five year total return declines. This pattern suggests that recent momentum is building off a weak longer run base.
Contrast CONMED’s rebound with a curated set of medical and healthcare stocks by scanning our 36 healthcare AI stocks that are already showing fresh momentum.
For CONMED, that sharp short term bounce clashes with years of weaker total returns. Is the latest move finally catching up to the underlying surgical devices business, or is sentiment simply swinging the pendulum again as valuation resets next?
Most Popular Narrative: 11% Overvalued
CONMED’s last close at $50.59 sits above the analyst consensus Narrative fair value of $45.50, so the current share price leans richer than that framework suggests. The analyst consensus Narrative on Simply Wall St ties that gap directly to execution on a handful of very specific growth platforms and capital allocation choices.
The accelerating adoption of minimally invasive and robotic-assisted surgeries, combined with CONMED's positioning through AirSeal and BioBrace, remains a live driver as AirSeal is still used in only 6% to 7% of more than 3 million annual U.S. laparoscopic procedures and is now cleared for use with additional robotic cannulas. This can support higher procedure-driven revenue and recurring consumables sales.
See why 3 investors see CONMED as 11% overvalued.
Result: Fair Value of $45.50 (OVERVALUED)
Still, the CONMED story can break if organic growth underwhelms or higher interest costs squeeze the cash needed to support its key surgical platforms.
Find out about the key risks to this CONMED narrative.
Another View On CONMED’s Valuation
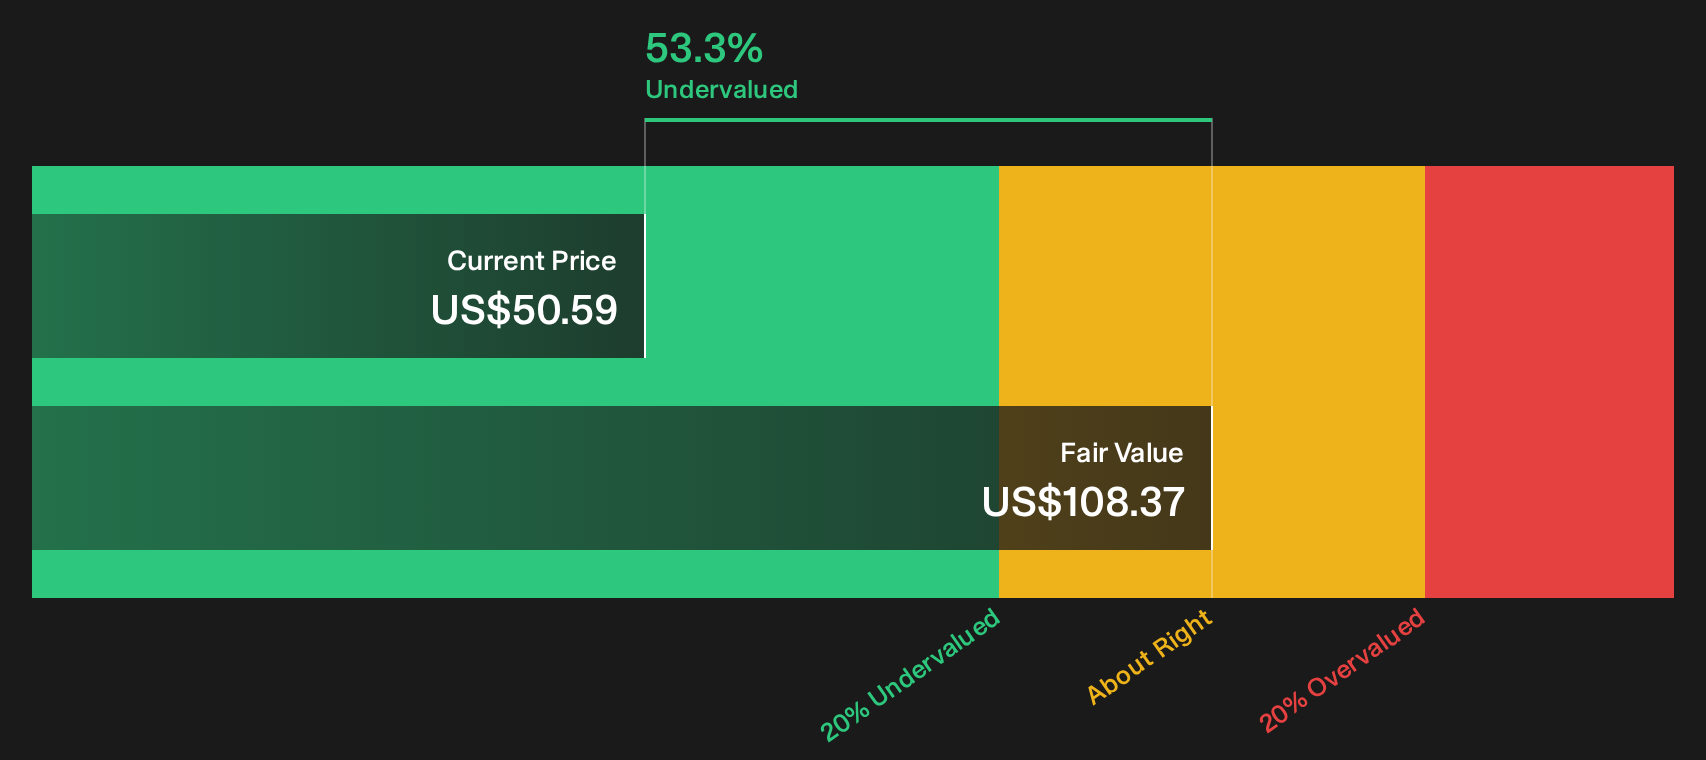
The analyst narrative frames CONMED as about 11% overvalued at $50.59 versus a $45.50 fair value. A different lens tells another story. Simply Wall St’s DCF model estimates future cash flows at $108.37 per share, which points to the stock trading at roughly a 53% discount. Which framework do you trust more when actual cash generation is the anchor?
For a closer look at how this cash flow view is built, including the key assumptions behind that gap, Look into how the SWS DCF model arrives at its fair value.
Next Steps
If the split views on CONMED leave you undecided, use that tension as a prompt to act quickly, review the underlying data, and form your own perspective with 4 key rewards and 1 important warning sign
Looking for more investment ideas beyond CONMED?
Do not stop at CONMED alone. Use the Simply Wall St screener to quickly surface fresh ideas that match your risk appetite, income goals, and quality filters.
- Target stronger balance sheets by scanning our list of solid balance sheet and fundamentals (24 results) so you are not relying on highly leveraged businesses when conditions change.
- Hunt for underappreciated quality through the 32 high quality undervalued stocks and see which companies trade at prices that differ from their underlying fundamentals.
- Build a steadier income stream by reviewing the 6 dividend fortresses and spot stocks with yields that might complement your existing holdings.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com