


EN
Valvoline (VVV) Stock Looks Stretched Against Its Current Earnings Power
Valvoline shares have quietly put together a solid run so far this year, which puts a spotlight on a simple question for you as a shareholder or potential buyer: Is the current price really supported by the earnings power of the business?
- The stock is up 19.9% year to date, which makes it important to check whether that gain lines up with what the company currently earns.
- The business model leans heavily on service center profitability and cash generation from routine vehicle maintenance, which can shape how much value investors place on each dollar of earnings.
- Your read on Valvoline is one view; the desks covering it have another. See what analysts think Valvoline's shares could be worth.
The stock's next move may depend on whether today's valuation can be explained by what Valvoline earns right now and what investors expect it to earn over time.
If you are questioning whether Valvoline's 19.9% year to date run is really backed by its earnings, it can help to compare that same lens across 32 high quality undervalued stocks.
Is Valvoline Getting Expensive on Earnings?
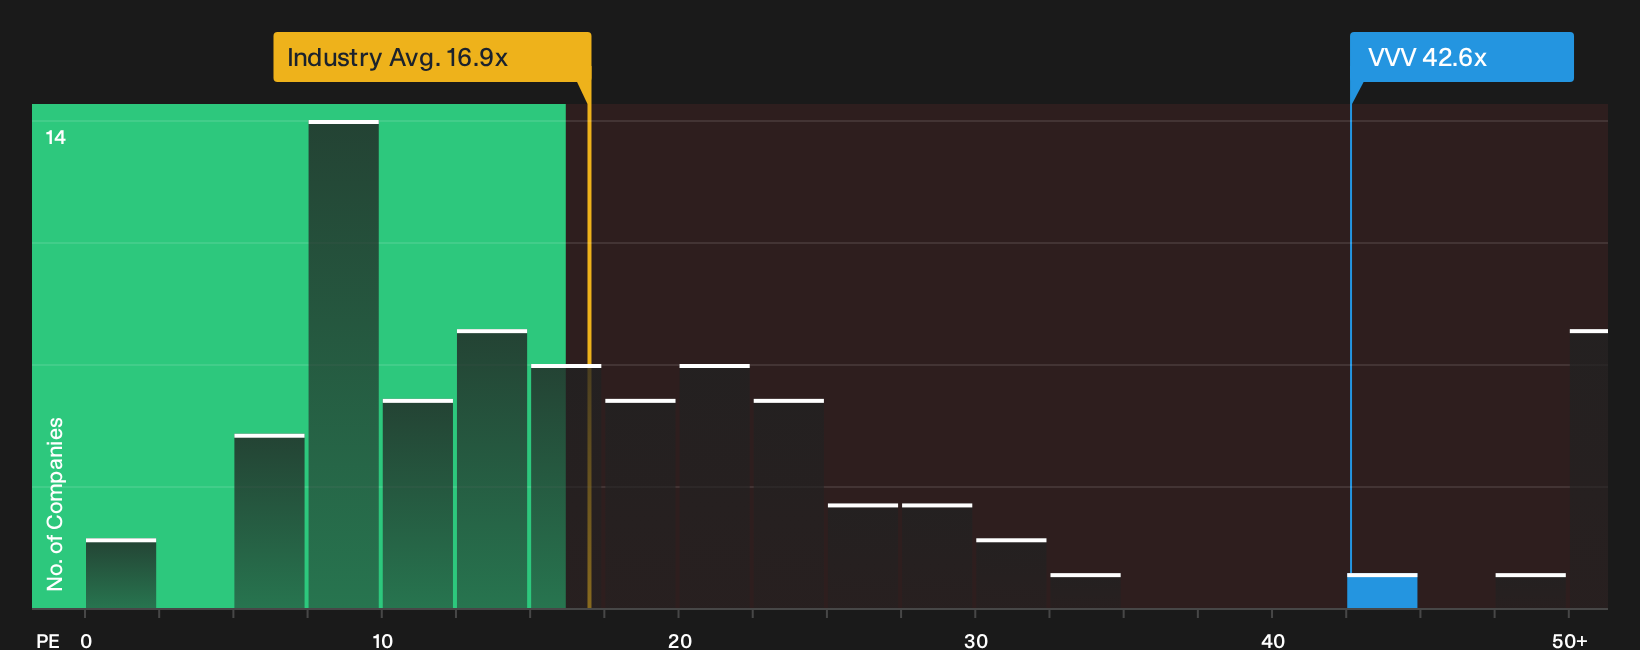
P/E is a useful lens for Valvoline because the market is clearly keying off its earnings stream rather than book value or revenue alone. On that yardstick, the stock trades on a P/E of 42.6x, compared with around 16.9x for the broader Specialty Retail group and a peer set closer to 7.9x. That is a sizeable earnings multiple for a vehicle service business where cash flow and repeat maintenance visits do a lot of the heavy lifting.
The Fair Ratio model, which estimates the kind of P/E you might expect given Valvoline's fundamentals and risk profile, points to a lower figure than where the shares trade today. In plain terms, the current valuation sits above that tailored benchmark and also well ahead of sector and peer levels, so anyone buying in at this price is paying a premium for the earnings stream and whatever future outcomes they are hoping those earnings can support. Explore the numbers behind Valvoline's P/E valuation.
The Valvoline Narrative: What Would Justify Today's Price?
Narratives on Valvoline take the high P/E puzzle you just saw and spell out the specific future paths for growth, margins and earnings that would need to play out for the stock to be worth materially more or less than it is today, and they sit on Simply Wall St's Community page. Instead of stopping at a single fair value number, Narratives describe the business outcomes that figure rests on so you can watch in real time whether those assumptions still match Valvoline's actual progress.
One of the top narratives on Valvoline: 20% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"Analysts expect Valvoline to keep leaning on store expansion, premium service mix, and franchise partner growth to grow system-wide sales over time…"
Discover why this Narrative puts Valvoline at 20% undervalued.
One big question Valvoline’s valuation still does not answer
The current price tells you what the market thinks Valvoline is worth today, but analyst projections a few years out offer a different lens on where earnings and cash flows might head next. Explore where analysts expect Valvoline to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com