


EN
Is Celsius Holdings (CELH) Trading At A Premium After Record Revenue?
Celsius Holdings has reshaped its energy drink portfolio and leadership structure while the share price has been under pressure for several years. This puts a spotlight on whether the current valuation is properly anchored to its earnings power. With the stock trading around US$32, the question is how much of the business story is already reflected in that number, and how much is still just hope.
- The share price has fallen 35.1% over the past 3 years, so any case for owning Celsius now leans heavily on what its earnings can justify rather than past momentum.
- A record US$847.2m revenue quarter driven by the broader portfolio and new brand structure can support expectations for future profit growth, but it also raises the bar for what investors may look for in earnings delivery.
- Your read on Celsius Holdings is one view; the desks covering it have another. See what analysts think Celsius Holdings's shares could be worth.
The issue now is whether Celsius Holdings' current share price is adequately backed by the earnings it is generating today and what those profits may reasonably support in the years ahead.
If you want a wider set of ideas alongside Celsius Holdings while still keeping earnings power in focus, a curated screen of 32 high quality undervalued stocks.
Has Celsius Holdings Run Too Far on Earnings?
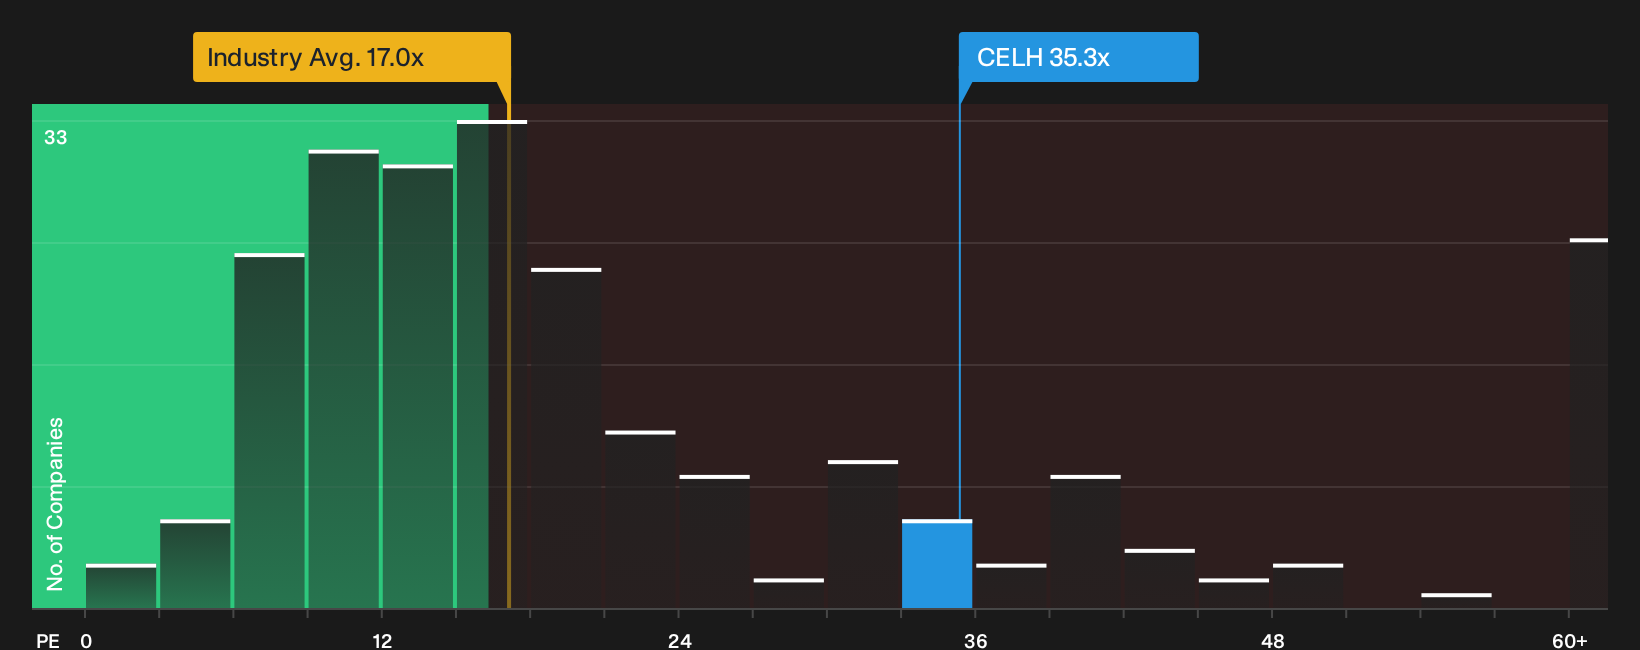
The P/E ratio fits Celsius Holdings well because earnings are now a key reference point for the reshaped energy portfolio. At roughly 35.3x, the stock trades at a premium to both the Beverage sector average near 17.0x and the peer pack around 29.6x, so the market is putting a richer price on each dollar of current profit than many rivals.
That premium also sits above what a tailored fair P/E multiple would suggest for Celsius Holdings once growth, margins, size and risk are blended together, which points to the shares screening as overvalued on this lens. Because the record US$847.2m quarter came with some margin pressure and no formal guidance, the valuation may appear demanding for investors who prefer clear earnings follow through before paying this kind of earnings multiple. Explore the numbers behind Celsius Holdings's P/E valuation.
The Celsius Holdings Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Celsius Holdings valuation puzzle leaves off by spelling out which future paths for revenue, margins and earnings would need to play out for the stock to look meaningfully cheaper or more expensive than it does today, all housed on the Community page. Each narrative treats fair value as a thesis about the business that can be tracked over time rather than a static snapshot, so you can see how the underlying story holds up as new information arrives.
Bulls and bears are looking at the same Celsius Holdings data and reaching very different conclusions about what the current earnings justify.
Bull case: 42% undervalued
According to JD009, an investor in the Simply Wall St Community, the long view on Celsius starts with how the business changed in 2022 and 2024.
"The ones who understood what actually happened in 2024 and why the crash was a channel inventory problem, not a brand problem, had the best entry point..."
Discover why this Narrative puts Celsius Holdings at 42% undervalued.
Bear case: 12% overvalued
The bearish analyst Narrative on Simply Wall St frames Celsius through the lens of pressure on margins, mix and execution rather than just headline revenue.
"The gap between modest Celsius scanner declines and much steeper reported net sales pressure hints at ongoing mix, trade spend and distribution issues..."
Explore why this Narrative puts Celsius Holdings at 12% overvalued.
Celsius Holdings valuation is only part of the story
Celsius Holdings still has another layer that matters just as much as the earnings multiple, because internal checks have raised specific business concerns that investors may want to review before deciding how to weigh this stock. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com