


EN
Is Freedom Holding (FRHC) Priced For Too Much Earnings Hope?
Freedom Holding has given long term shareholders a powerful ride over the past few years, yet the recent pullback and fresh headlines now put a sharper spotlight on whether its current price is properly supported by its earnings profile.
- Over the past 5 years the stock has returned about 118.9%, which puts real pressure on the question of how much of its earnings power may already be reflected in the valuation.
- S&P’s upgrade of Freedom Finance Insurance to BB can support assumptions about balance sheet resilience and potentially steadier profitability, which feeds directly into how much investors are prepared to pay for the group’s earnings stream.
- Before you settle on a price for Freedom Holding, see what its peers cost. See how Freedom Holding's 67.4x P/E compares with its peers.
The issue now is whether Freedom Holding's current share price is adequately backed by the earnings it generates today and what analysts expect it to produce in the future.
If you want more context around Freedom Holding's recent run and the earnings debate, it can help to weigh it against 32 high quality undervalued stocks.
Does Freedom Holding Look Pricey on Earnings?
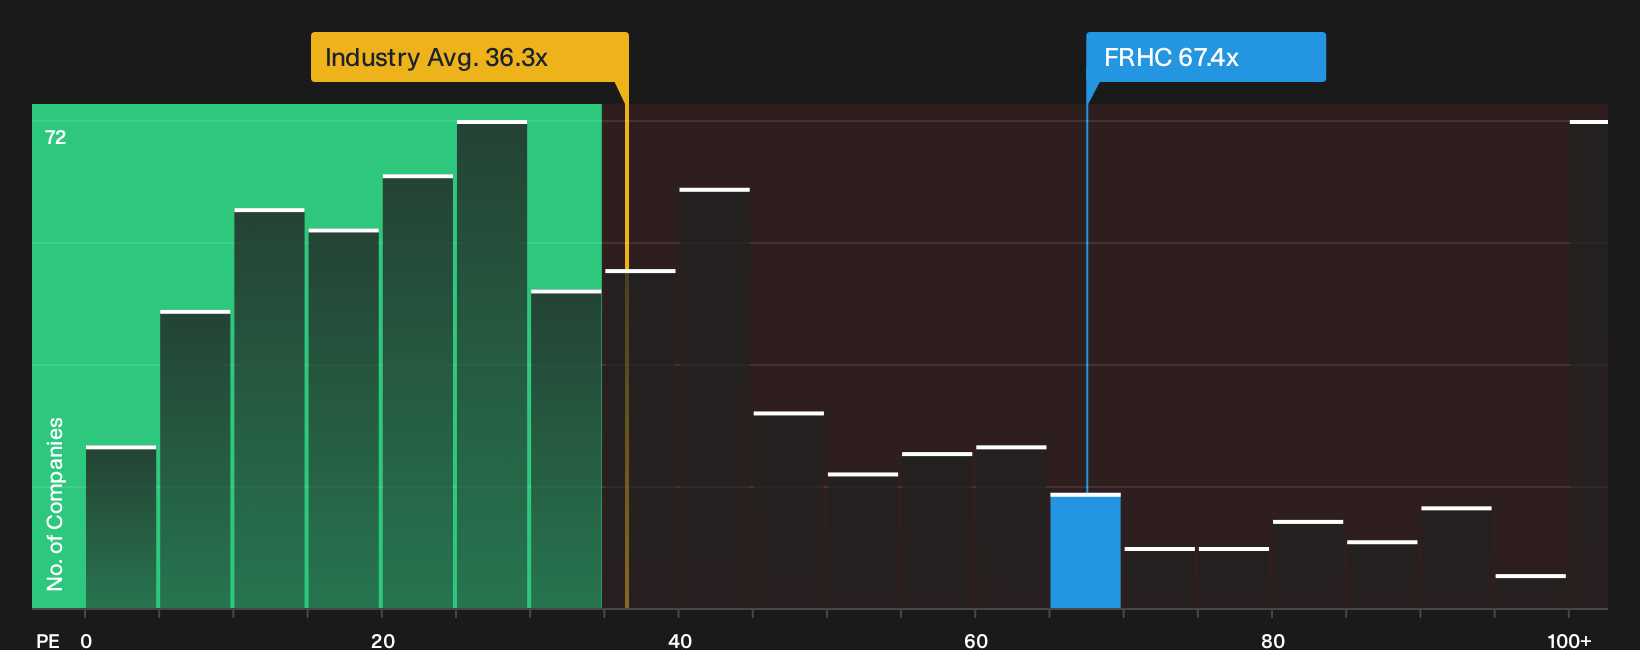
P/E suits Freedom Holding because earnings are a key anchor for a capital markets platform that investors often judge on profit per share. On that yardstick, the stock trades on about 67.4x earnings, which sits well above the Capital Markets industry average of roughly 36.3x and the peer group near 15.1x. That gap indicates that buyers today are willing to pay much more for each dollar of Freedom Holding's reported profit than they typically do across the sector.
S&P’s upgrade of Freedom Finance Insurance may help some investors justify a richer multiple by pointing to balance sheet strength, yet the current P/E still appears elevated relative to the broader industry. To decide whether that premium is acceptable, you would need to consider how durable Freedom Holding's earnings engine is compared with other capital markets businesses, and how comfortable you are with paying a sector-level price that stands this far above the mainstream. Explore the numbers behind Freedom Holding's P/E valuation.
The Freedom Holding Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Freedom Holding valuation puzzle leaves off by explaining which specific assumptions about growth, margins and earnings would need to hold for the shares to be worth much more or considerably less than today's price on a risk aware basis. Each narrative treats fair value as a thesis about how the business might play out over time that you can watch mature, rather than as a frozen snapshot, and all are hosted on Simply Wall St's Community page.
A written, number driven view on Freedom Holding gives you a clear way to test whether developments like the S&P upgrade of Freedom Finance Insurance and the group’s global expansion are actually feeding into the earnings profile the current P/E implies. It turns those moving parts into explicit assumptions on growth, margins and capital strength that you can revisit as new results and news arrive.
Share your own Narrative for Freedom Holding and set out the assumptions behind your valuation.
Freedom Holding's valuation still hinges on one unresolved piece
Everything so far revolves around what the market pays for today, while the real swing factor is how professional analysts currently see Freedom Holding a few years down the road. Explore where analysts expect Freedom Holding to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com