


EN
E.ON (XTRA:EOAN) Profit Swing Puts Its Valuation Story Back In Focus
E.ON (XTRA:EOAN) just delivered a sharp swing in profitability, moving from a net loss a year ago to net income of €972 million in the third quarter of 2026.
The earnings swing has arrived alongside a clear shift in sentiment around E.ON, with the share price at €19.47 and a 30 day share price return of 12.71% adding to an 18.32% year to date gain and a 31.54% total shareholder return over twelve months, pointing to momentum that investors are treating as more than a short term bounce.
Look beyond E.ON's earnings swing and see how other utilities with improving profitability compare in our hand picked list of solid balance sheet and fundamentals (198 results)
E.ON’s sharp earnings recovery and double digit one year return have pulled the share price close to analyst targets, yet it remains below some intrinsic estimates. Where does a fair valuation really land on that spread?
Most Popular Narrative: 7% Undervalued
E.ON’s analyst consensus Narrative on Simply Wall St points to a fair value of €20.98, modestly above the latest close at €19.47. This suggests a valuation gap built around long term grid spending, regulation and the OVO deal rather than short term trading moves.
The planned €48b investment program between 2026 and 2030, with around €40b directed to Energy Networks and annual capex in 2026 already running well above depreciation, positions E.ON to expand its regulated asset base and earnings if the spend translates into approved projects and tariffs.
See why 36 investors see E.ON as 7% undervalued.
Result: Fair Value of €20.98 (UNDERVALUED)
Still, the E.ON story hinges on RP5 terms and project approvals, since tougher German regulation or weaker returns on heavy grid capex could quickly cool this undervaluation narrative.
Find out about the key risks to this E.ON narrative.
Another View: DCF Marks E.ON As Slightly Rich
While the popular Simply Wall St narrative frames E.ON as about 7% undervalued on analyst targets, the SWS DCF model points in the opposite direction. On that future cash flow view, the shares at €19.47 sit above an estimated value of €18.65, which leans toward modest overvaluation and raises a simple question for you: Which yardstick do you trust more for a long holding period?
To unpack how that future cash flow estimate is built and stress test the inputs against your own expectations, take a closer look at the Look into how the SWS DCF model arrives at its fair value..
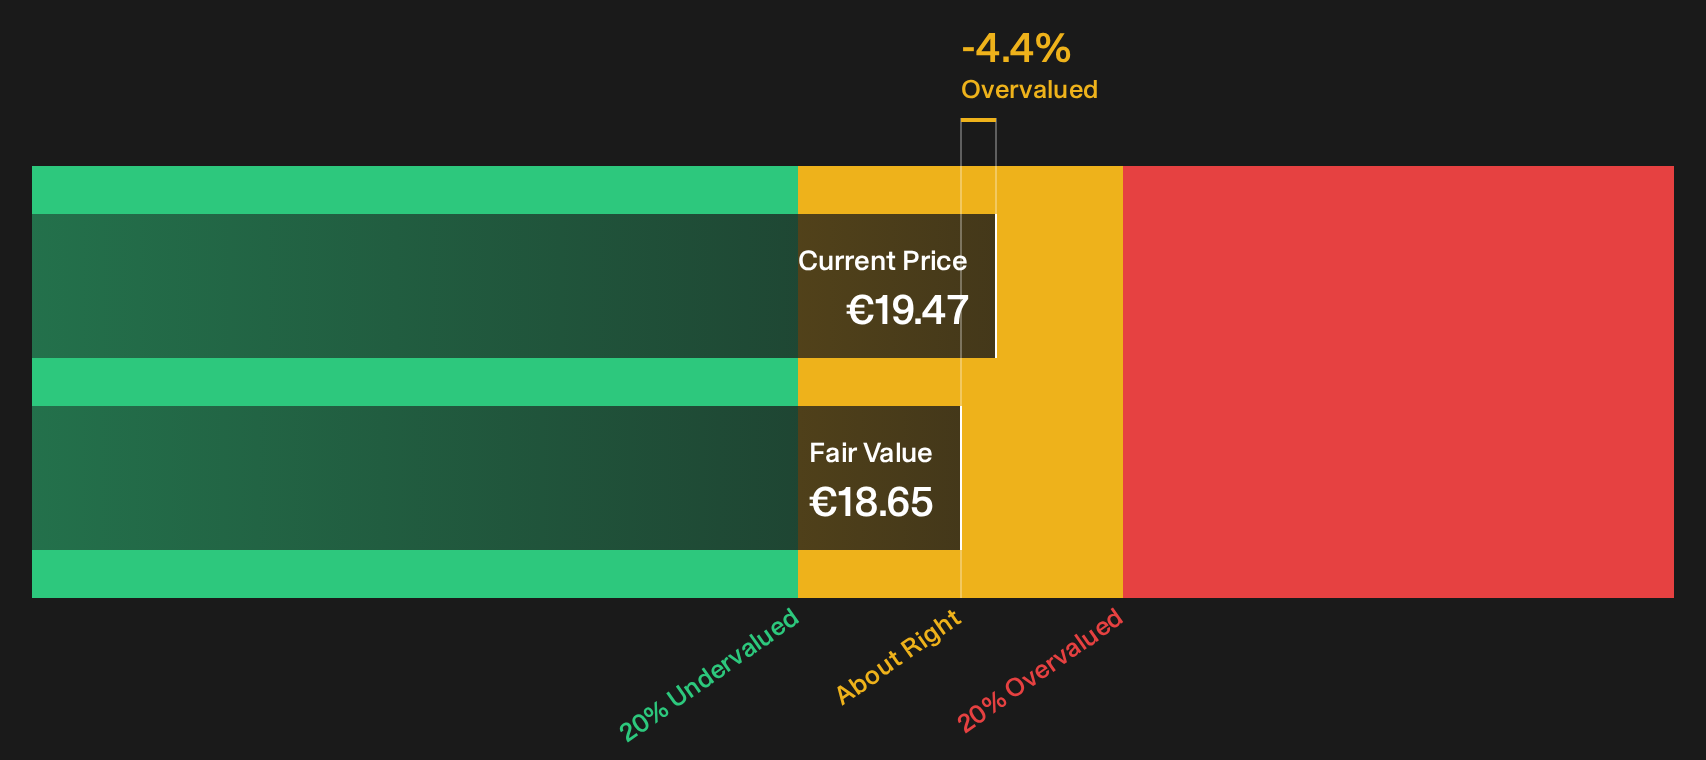
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out E.ON for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 198 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on E.ON’s value story so far. If you want to move fast and judge the balance of risk and upside for yourself, go straight to the 3 key rewards and 2 important warning signs
Looking For More Ideas Beyond E.ON?
Do not stop your research with E.ON. Broaden your watchlist using a few focused stock lists that highlight different ways to balance risk, quality and potential returns.
- Target higher quality upside by scanning companies that look mispriced on fundamentals through the 198 high quality undervalued stocks.
- Build an income focused watchlist by zeroing in on companies that offer strong payouts using the 220 dividend fortresses.
- Prioritise resilience by concentrating on businesses with robust finances through a 210 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com