


EN
Paycom (PAYC) Stock Looks Fully Priced After Raised 2026 Guidance
Paycom Software has delivered a sharp year to date gain, and with earnings in focus after recent headlines, the question now is whether that higher share price still lines up with what the business is actually making. For anyone looking at Paycom stock today, the key issue is how much of the current optimism is already reflected in the earnings that support it.
- The share price is up 63.3% year to date, which puts extra pressure on current and future earnings to carry that kind of move.
- Recent commentary around Paycom's AI driven products and investment in automation suggests investors are weighing how these efforts can influence profit margins and the timing of cash generation from its software platform.
- Your read on Paycom Software is one view; the desks covering it have another. See what analysts think Paycom Software's shares could be worth.
The stock's next move may depend on whether Paycom's current earnings are strong enough to support the valuation that this year to date rally has created.
If you want more context around how Paycom Software's AI story fits into the broader theme of enterprise automation, a focused stock screen is a useful second step in your research with 42 profitable AI stocks that aren't just burning cash.
Where Does Paycom Software Sit on Earnings?
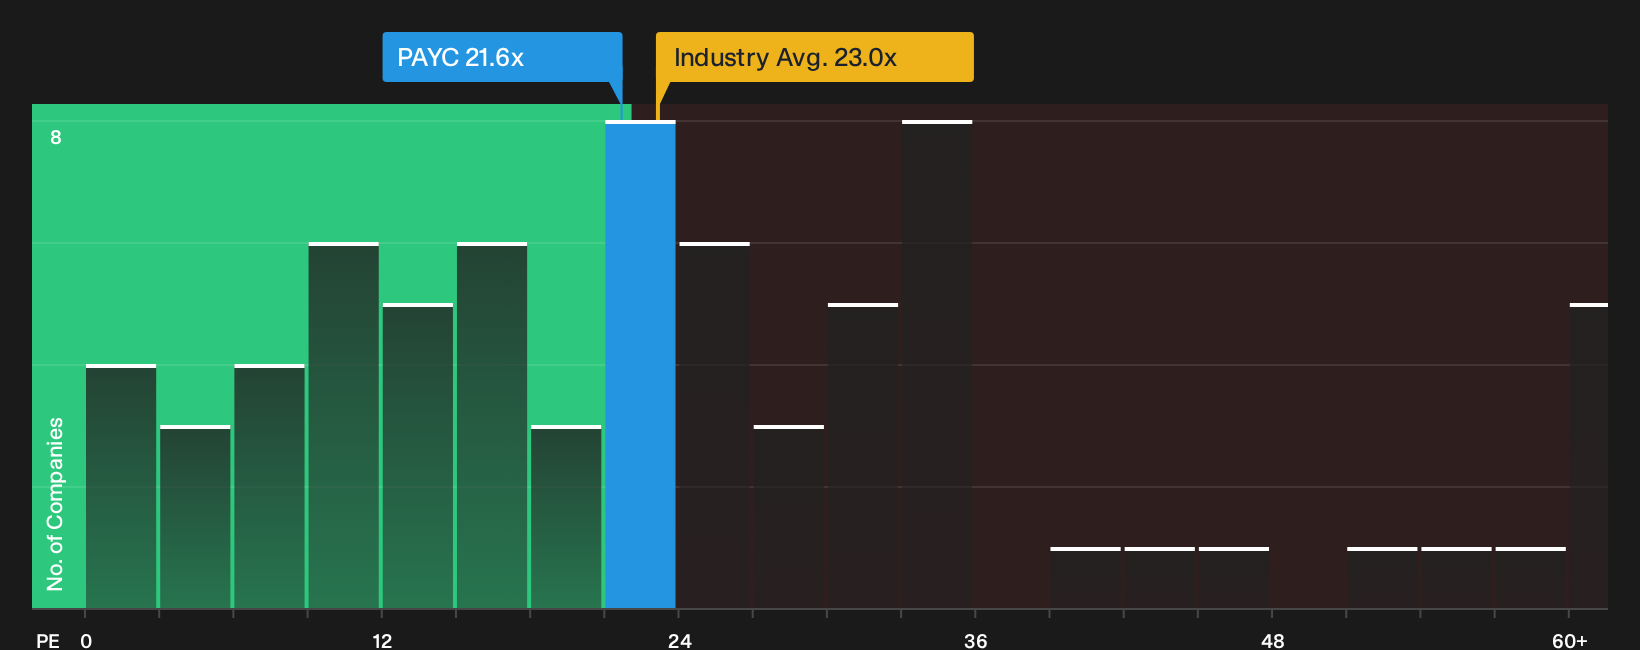
The P/E ratio is a useful lens for Paycom Software because earnings are a core focus for investors watching its AI driven automation story. On this measure, the stock trades on a P/E of 21.6x, which is slightly below both the Professional Services industry average of 23.0x and the peer group on 22.8x. That places Paycom in roughly the same valuation ballpark as similar businesses in its space rather than at a clear premium or clear discount.
The Fair Ratio model, which blends factors like profitability, expected cash generation and sector risk, points to a level close to where Paycom currently trades, so the P/E looks about right rather than clearly cheap or expensive on this framework. Because management recently raised full year guidance on the back of AI adoption and automation uptake, the current multiple suggests the market already recognises those drivers without assigning an aggressive extra premium. For anyone researching the stock, the key question is whether the earnings profile you expect from Paycom justifies paying this kind of going rate for each dollar of profit. Explore the numbers behind Paycom Software's P/E valuation.
The Paycom Software Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where this valuation puzzle for Paycom Software leaves off by spelling out what sort of growth path, margin profile and earnings power would need to show up for the stock to be worth materially more or materially less than today’s price, based on views shared on the Community page. Rather than a single P/E or model output, each narrative lays out its own set of fair value assumptions so you can see how those expectations stack up against Paycom Software's reported results over time.
Bulls and bears are reading the same Paycom Software story yet reaching very different conclusions about how much is already priced in.
Bull case: 8% undervalued
The analyst consensus Narrative on Simply Wall St sees a stronger payoff from Paycom Software's automation and AI toolkit.
"Ongoing automation and AI driven product development across Paycom Software's single database HCM suite, including tools such as Beti and GONE that management links to reduced manual processing and higher client satisfaction, continues to support strong revenue retention and operational efficiencies that can sustain EBITDA margin strength and earnings power..."
Discover why this Narrative puts Paycom Software at 8% undervalued.
Bear case: 24% overvalued
The bearish analyst Narrative on Simply Wall St leans toward a slower trajectory for Paycom Software's add on products.
"The current valuation implies that the market is placing a high multiple on 7 to 8% guided 2026 revenue growth, record mid 40s EBITDA margins, and free cash flow expected to exceed US$650 million, which this narrative views as too rich given the slower topline trajectory..."
Explore why this Narrative puts Paycom Software at 24% overvalued.
One more Paycom Software factor to check before you act
Price, profits and product get most of the attention, yet the people steering Paycom Software and the way their incentives are structured can heavily influence how this story plays out over time. See who runs Paycom Software and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com