


EN
What Franklin Templeton Doubters Missed
Franklin Templeton spent the past year juggling record AUM growth, a $100 million regulatory settlement at Western Asset, and an aggressive push into crypto products, yet the shareholder outcome was remarkably simple. For Franklin Templeton shareholders, the return over the past year was 70.5%, including dividends. If you had been weighing the bullish Uzbekistan and Saudi expansion against warnings about fee pressure and tech rivals back in November 2025, what did you really have to go on?
This theme extends beyond Franklin Templeton. See which of 23 cryptocurrency and blockchain stocks may still merit a closer look.
The Argument You Would Have Been Weighing On Franklin Templeton
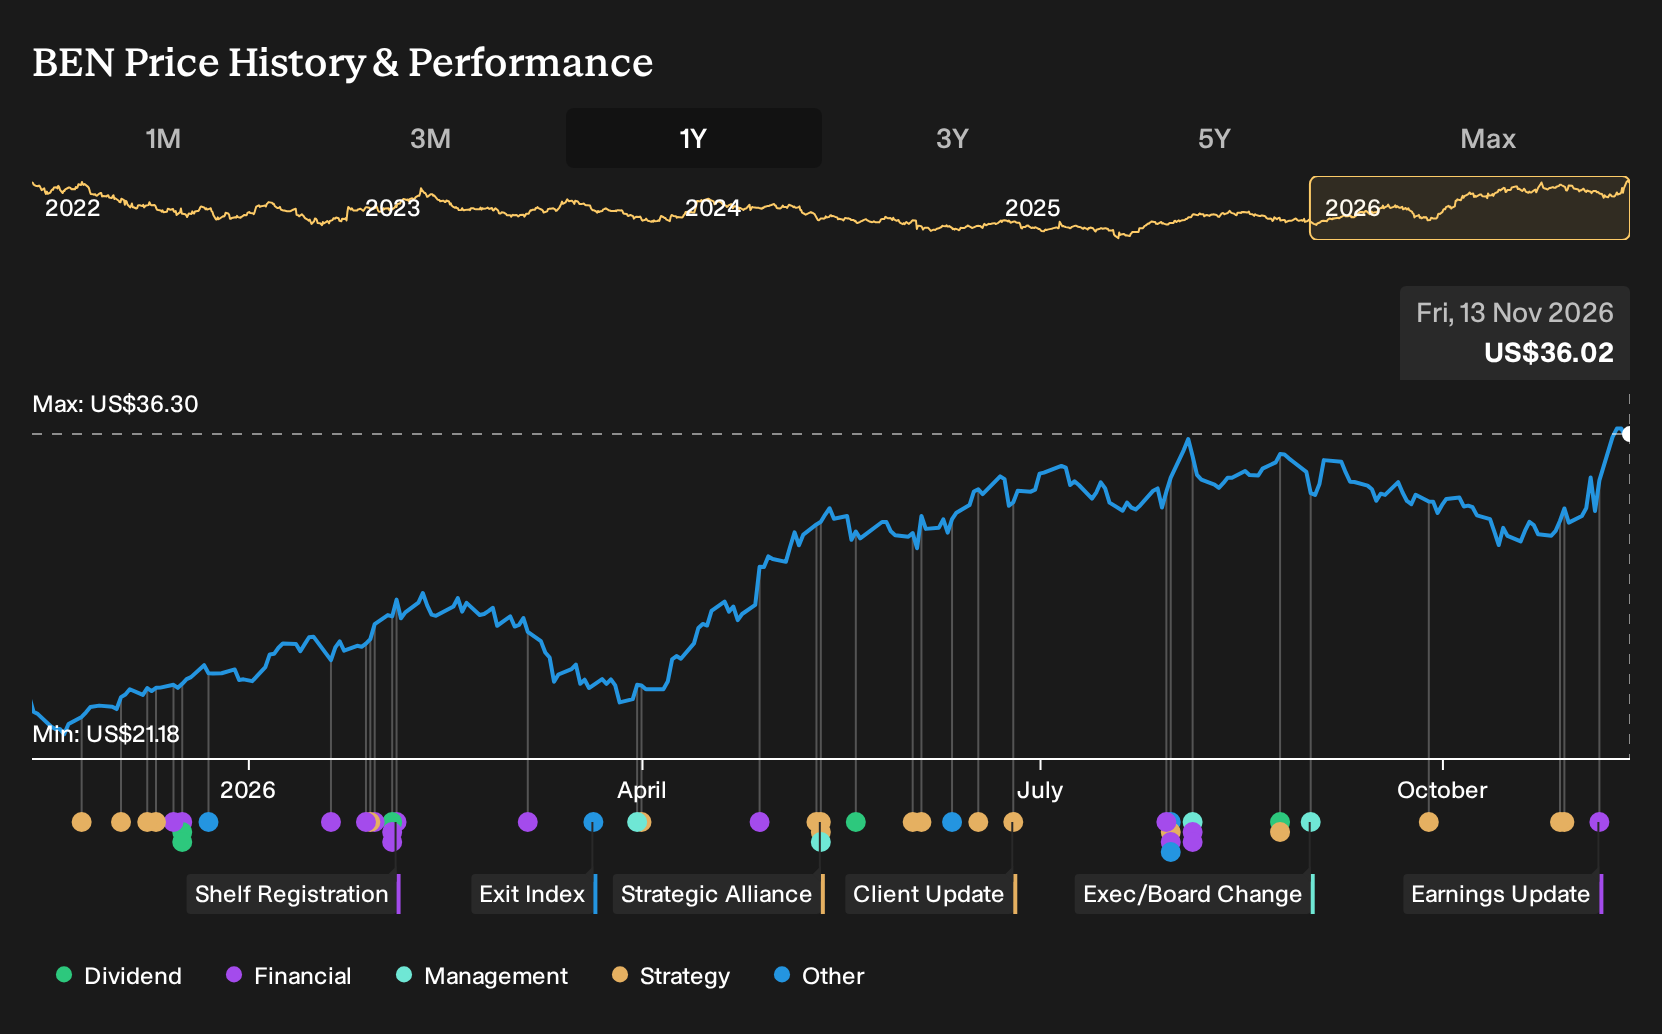
The shares cost US$22.29 at the start of the period. Franklin Templeton sat between two very different stories investors had in mind, each leaning on specific forecasts rather than hindsight.
On the bullish side, one narrative pointed to a Fair Value of US$25, a notional target based on Uzbekistan and Saudi mandates helping diversify AUM. That view leaned on assumptions of 1.0% annual revenue growth and profit margins reaching 15.6% over roughly three years.
The bearish script argued that legacy fee pressure and tech rivals justified a Fair Value of US$19, again only if its expectations played out. It focused on continued active fund outflows and the risk that unproven digital spending might still leave margins constrained.
What The Franklin Templeton Results Actually Tested
The launch of Franklin Templeton’s dividend to Bitcoin ETFs and the creation of Franklin Crypto supported the bullish idea that digital assets could become a meaningful extension of the business. At the same time, Q4 2026 numbers showed revenue at US$2,434.9m and net income at US$364.1m, with net margin at 15.0% versus 4.6% a year earlier. On balance, the evidence supported the optimistic case more than the cautious one.
The key lesson is simple. When a story relies on margin expansion, treat net margin as the main test. For any other asset manager, compare that promised profitability path with the margin that actually appears in quarterly filings before deciding how much of the thesis has really shown up in the accounts.
What Franklin Templeton’s Price Already Assumes After A 71% Run
Franklin Templeton now trades at US$36.02, after a 70.5% gain over the past year. The bearish analyst Narrative on Simply Wall St places its Fair Value below that level, arguing the current tag already bakes in a lot of optimism.
That Narrative centers on whether newer ETFs, SMAs, alternatives and digital efforts really scale into high margin, fee rich AUM. A buyer today effectively banks on those franchises offsetting fee sharing pressure, so the open question is how that pressure interacts with any future margin ambitions.
"The current valuation implies the market is already pricing Franklin Templeton as if its alternatives, ETF, SMA and digital asset franchises will justify premium margins and sustained organic inflows, leaving limited room for disappointment if these businesses do not continue to scale as implied."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
Before The Next Story Makes Headlines
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 48% below our estimate - expands beyond a single therapy by advancing kidney and endocrine pipelines.
- Company 2 - 44% below our estimate - rolls out higher margin automation while tightening service, efficiency and cost initiatives.
- Company 3 - 25% below our estimate - turns a cable niche into a full connectivity stack through silicon photonics integration.
Those are three of them. See every one of the 32 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com