


EN
What Is Drawing Fresh Attention To Kilroy Realty (KRC)?
Kilroy Realty (KRC) set its latest income signal with a regular quarterly cash dividend of $0.54 per share. The dividend is payable on January 13, 2027, to holders of record on December 31, 2026.
The dividend decision lands as Kilroy Realty trades at $36.04, with a 1 month share price return of 8.23% but a year to date share price decline of 5.21%. That mixed pattern pairs a 1 year total shareholder return decline of 5.96% with a 3 year total shareholder return gain of 39.76%, suggesting that longer term holders have seen recovery even as near term sentiment has been softer.
Compare Kilroy Realty's latest dividend move with a curated 6 dividend fortresses that pairs income potential with financial resilience.
Kilroy Realty now trades at a discount to both analyst targets and an internal fair value estimate, yet the share price still reflects clear caution. Is the gap compensation for real risk, or is it an opening mispriced by the market?
Most Popular Narrative: 10% Undervalued
Kilroy Realty's analyst consensus Narrative on Simply Wall St places fair value at $40.14 compared with the recent $36.04 share price. This frames the current discount around future leasing and development execution rather than past returns.
The pool of more than 1,000,000 square feet of signed but not yet commenced leases carrying about $78 million of annual base rent and a high share of triple net structures is poised to feed through into higher occupancy, revenue and potentially wider net margins as these leases commence.
Improving life science sentiment and rising robotics requirements around Kilroy Oyster Point Phase 2 and other Bay Area clusters, combined with pre leasing progress and targeted mid 5% yields on new lab space, can support rent growth and incremental earnings as these projects reach higher stabilization.
See why 15 investors see Kilroy Realty as 10% undervalued.
Result: Fair Value of $40.14 (UNDERVALUED)
Still, Kilroy Realty faces real pressure if portfolio occupancy lingers near 77% and the large 2027 DIRECTV, AT&T and Long Beach lease rollovers bite harder than expected.
Find out about the key risks to this Kilroy Realty narrative.
Another View: Kilroy Realty Looks Expensive On Earnings
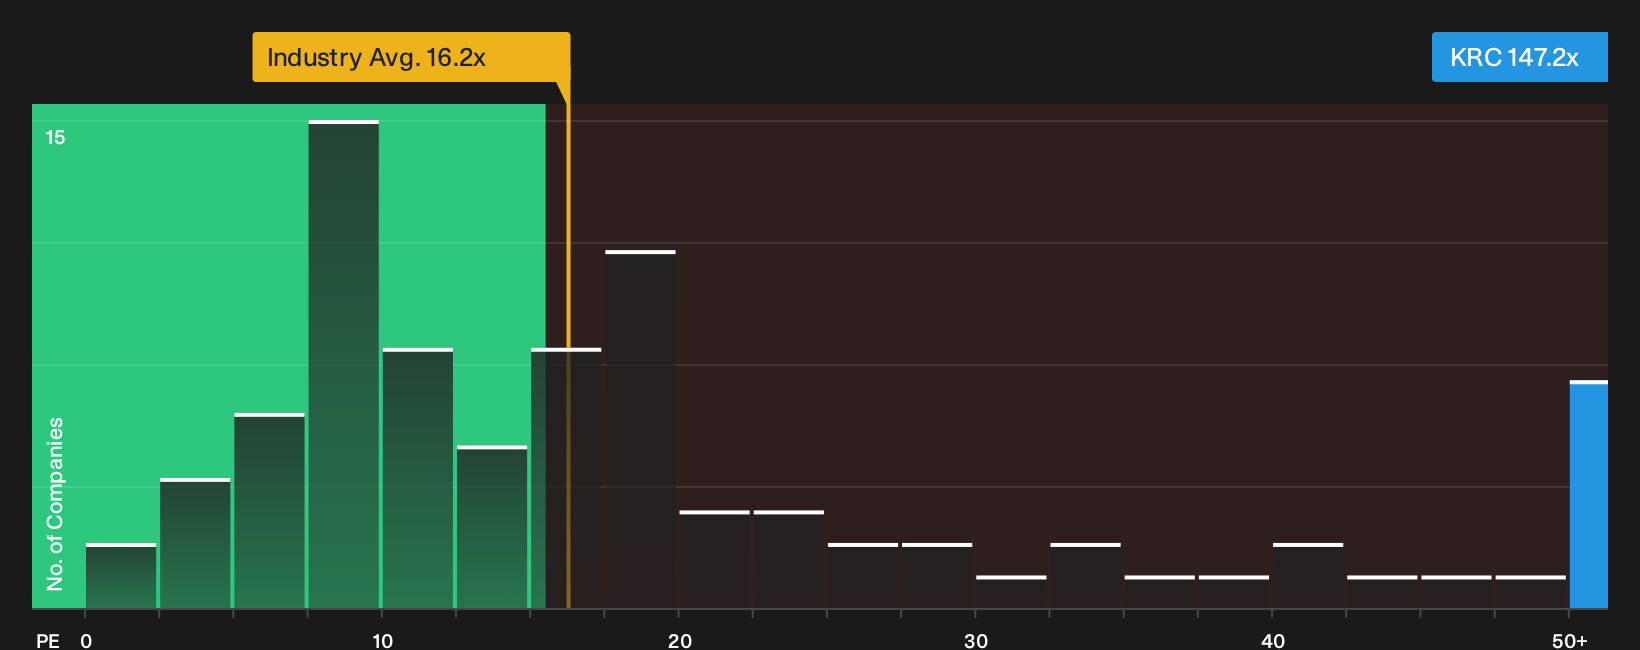
Kilroy Realty screens as undervalued on future cash flows, yet the current P/E of 147.2x tells a very different story. That multiple is far above the US Office REITs peer average of 34.1x and the 47.2x fair ratio, which points to valuation risk if earnings do not keep pace.
The gap between discounted cash flow support and a rich headline multiple leaves a simple question for investors: Which signal deserves more weight for Kilroy Realty at $36.04, the SWS DCF model or the earnings-based comparison across the sector?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Kilroy Realty's valuation and risk profile can feel messy, so move quickly, review the underlying data yourself, and then weigh the 3 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Kilroy Realty?
If Kilroy Realty has sharpened your view on pricing and risk, do not stop here. Broader opportunity often appears where expectations are low and quality quietly holds.
- Target dependable growth by scanning companies with robust cash generation and disciplined balance sheets through the 32 high quality undervalued stocks.
- Prioritize resilience by reviewing a 31 resilient stocks with low risk scores that filters for businesses with steadier risk profiles and fewer potential surprises.
- Spot potential early movers by checking a 20 high quality undiscovered gems before they sit squarely on every investor's radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com