


EN
Missed RS Group's Run? What Holders Had To Believe
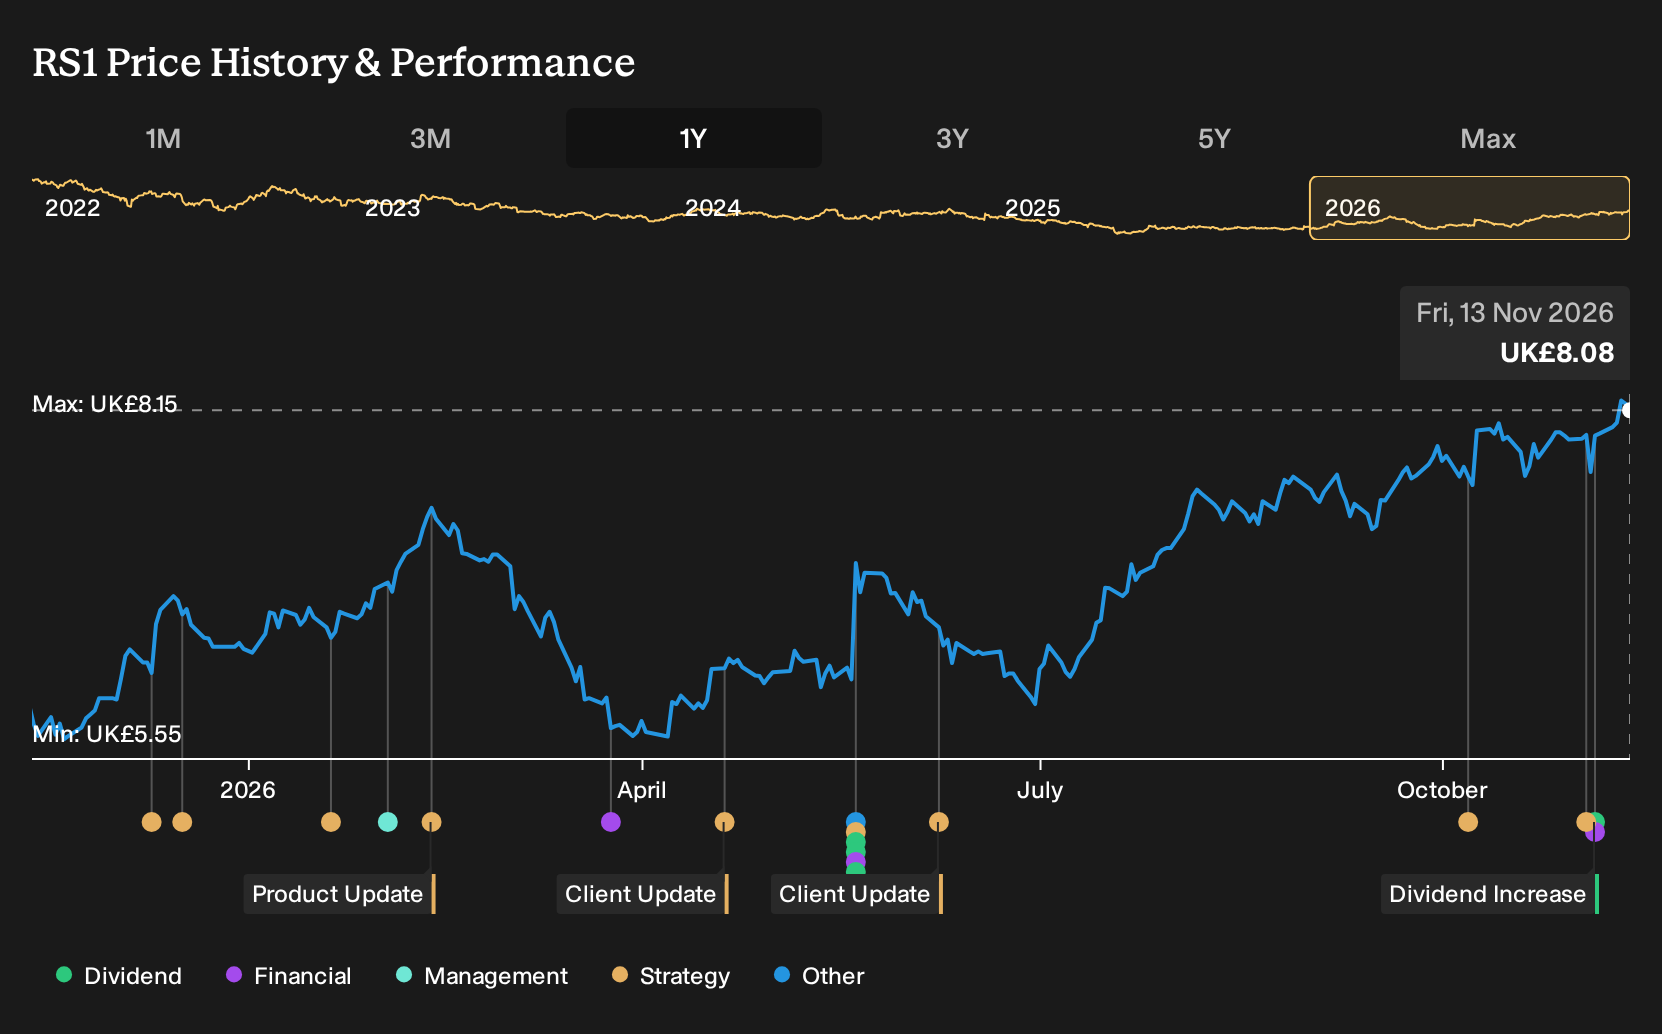
RS Group spent the year talking up AI search tools, tighter cost control and the Distrelec integration, while one concrete launch on offer to industrial clients was Schneider Electric's TeSys Tera system for cutting motor downtime and power use in aging plants. Holding RS Group over the past year would have returned 50.6%, including dividends. If you were deciding on 13 November 2025, what would you have needed to believe about that TeSys Tera push and the wider digital commerce story?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
This theme extends beyond RS Group. See which of 86 robotics and automation stocks may still merit a closer look.
The Two RS Group Stories Investors Were Weighing
The shares cost £5.67 at the start of the period, and RS Group sat between two sharply different stories about where digital commerce and Distrelec might lead.
In the bullish case, Fair Value sat at £7, or 24% above the start price, if integration of Distrelec created scale benefits and RS Group’s AI search and digital engines lifted customer conversion.
The cautious view pointed to a £4.8 Fair Value, or 15% below the start price, if direct manufacturer channels, higher tech spend and tougher regulations kept squeezing distribution margins.
What The Evidence Around RS Group Actually Tested
The clearest test of the RS Group thesis came from the TeSys Tera rollout, which directly backed the view that richer digital tools can deepen customer ties. H1 2027 results showed revenue at £1.5b and net income at £87.8m, with net margin at 5.7%, slightly lower than 5.9%. The evidence cut both ways.
The key question was not just headline growth. It was whether higher tech spending translated into better profitability. For a different stock with a similar pitch, it may be useful to watch net margin alongside any story about digital upgrades or AI tools.
What RS Group's Current Price Already Assumes
RS Group now trades at £8.07, after a 50.6% gain over the past year. The bearish analyst narrative on Simply Wall St places its fair value below that level, arguing that the recent re-rating already prices in successful execution in digital, RS PRO and solutions.
A buyer today is effectively counting on RS Group turning higher tech and operating expenditure into durable margin gains. The question is how that assumption holds up if digital adoption, own-brand mix or cost inflation track closer to the risks the narrative sets out.
"The numbers imply the share price already factors in successful execution on digital growth, mix shift and cost reduction, leaving limited room for disappointment if cyclical end markets or self-chosen investment spend weigh on earnings."
One Narrative disagrees with today's price. → See where this Narrative says RS Group should trade
Go Straight To The Source
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 40% below our estimate - builds late-stage drug pipelines that address upcoming loss of exclusivity.
- Company 2 - 24% below our estimate - ramps production capacity and digitalisation so a large contract backlog converts to cash.
- Company 3 - 30% below our estimate - advances copper developments that feed incremental ore through an existing processing facility.
That is three of the list. See the full list of 15 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com