


EN
Is Sociedad Química Y Minera De Chile (NYSE:SQM) Reasonable On Earnings?
Sociedad Química y Minera de Chile has had a tough start to the year, with the share price under pressure and investors asking whether the current valuation still lines up with the company’s earnings power. After a stretch of mixed longer term returns, the key question is what today’s price is really asking you to believe about future profits.
- Year to date, the stock is down 23.1%, which puts the spotlight firmly on whether that drop has brought the share price closer to or further from what its earnings can justify.
- The business relies heavily on its ability to convert commodity exposure into consistent profit margins. Any change in cost discipline or pricing power can quickly alter how much support its current P/E multiple gets from underlying earnings.
- Your read on Sociedad Química y Minera de Chile is one view; the desks covering it have another. See what analysts think Sociedad Química y Minera de Chile's shares could be worth.
For investors, the debate is whether Sociedad Química y Minera de Chile's current share price is reasonable when set against the earnings it is generating today and is expected to produce over time.
If you want a wider earnings lens alongside Sociedad Química y Minera de Chile, consider using a focused screener of 32 high quality undervalued stocks.
Does Sociedad Química y Minera de Chile Look Undervalued on Earnings?
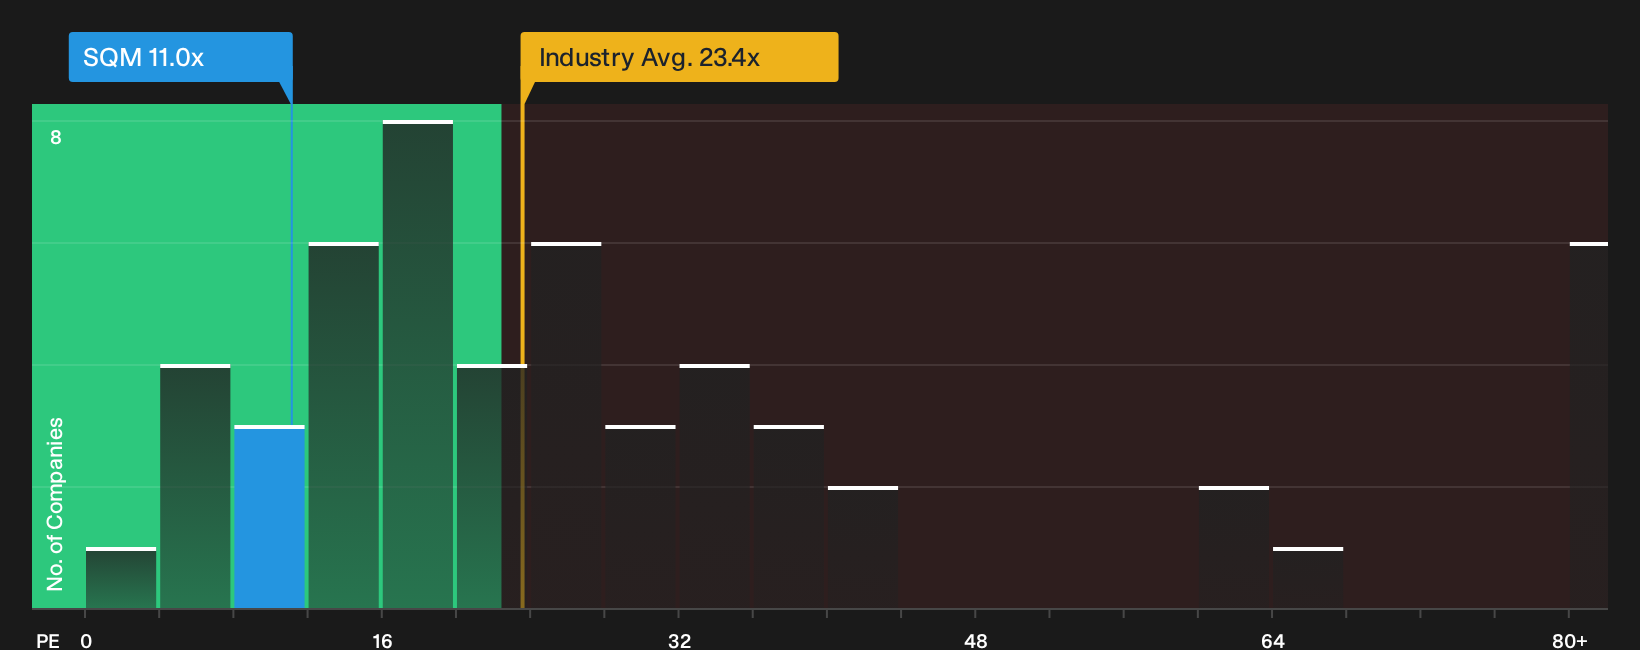
The P/E ratio is a useful quick filter for Sociedad Química y Minera de Chile because earnings still sit at the centre of how investors frame its value. Right now the shares trade on a P/E of 11.0x, which is well below the Chemicals sector average of 23.4x and also under the broader peer group on about 20.3x. That kind of gap tells you the market is putting a much lower price on each dollar of Sociedad Química y Minera de Chile's earnings than it does for many comparable businesses.
The tailored fair P/E multiple for the stock, which weighs its growth profile, profitability, size and risk, sits above the current 11.0x level. That indicates the shares are screening as undervalued on this specific earnings measure, although any investor still needs to judge whether Sociedad Química y Minera de Chile's future cash generation and commodity exposure justify closing that gap. Explore the numbers behind Sociedad Química y Minera de Chile's P/E valuation.
The Sociedad Química y Minera de Chile Narrative: What Would Justify Today's Price?
Narratives for Sociedad Química y Minera de Chile pick up where the valuation question leaves off by spelling out what kind of future growth, profitability and earnings path would need to play out for the shares to be worth materially more or materially less than they are today, on Simply Wall St's Community page. Where a single ratio or model gives you one number, Narratives unpack the set of assumptions behind it so you can watch in real time whether those conditions still look realistic.
Bulls and bears looking at Sociedad Química y Minera de Chile are reading the same lithium story but drawing very different conclusions about what matters most.
Bull case: 33% undervalued
This is drawn from the analyst consensus Narrative on Simply Wall St, which aggregates Street forecasts into a single view.
"Expansion of lithium production capacity in Chile through Novandino Lithium, which plans to increase production from 234,000 metric tons LCE in 2025 to between 280,000 and 290,000 metric tons in 2026 and around 300,000 metric tons in 2027, provides a visible path for higher lithium related revenue and potentially greater operating leverage…"
Discover why this Narrative puts Sociedad Química y Minera de Chile at 33% undervalued.
Bear case: 7% overvalued
This comes from the bearish analyst Narrative on Simply Wall St, which builds around the most cautious forecasts and price targets.
"The updated capex outlook of about US$3b over 2026 to 2028, together with roughly US$3b of long dated spending on Salar Futuro starting after environmental approval expected around 2029, increases the chance that cash generation lags capital needs and that returns on invested capital fall below what current growth assumptions for lithium, iodine and Specialty Plant Nutrition would imply…"
Explore why this Narrative puts Sociedad Química y Minera de Chile at 7% overvalued.
For Sociedad Química y Minera de Chile, the share price is only part of the story
The people steering Sociedad Química y Minera de Chile, how they are rewarded and whether those incentives align with long term shareholders can be just as important as any multiple on a screen. See who runs Sociedad Química y Minera de Chile and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com