


EN
What RB Global (RBA) Strong Q3 Earnings Means For Shareholders
- RB Global reported third quarter 2026 revenue of US$1,274.4 million and net income of US$140.1 million, alongside a US$0.33 quarterly dividend and completion of a US$500.25 million share repurchase program.
- The combination of higher earnings per share from continuing operations and active capital returns reflects how RB Global is balancing growth investment with direct cash distributions to shareholders.
- We will examine how RB Global's third quarter results and updated outlook influence the investment narrative around its marketplaces.
Scan how RB Global’s latest earnings, dividend, and buyback activity compare with other companies returning cash to investors by reviewing the 6 dividend fortresses in the market right now.
RB Global Investment Narrative Recap
Owning RB Global means believing its auction and salvage marketplaces can keep pushing more volume through the platform while holding on to healthy economics. The analyst consensus Narrative on Simply Wall St highlights expansion across heavy equipment, salvage and agriculture, supported by digital tools. Strong Q3 revenue and earnings keep that story intact and support near term confidence in execution.
The key short term swing factor remains how much of that higher GTV converts into profit while service fee take rates sit under pressure and fuel costs stay elevated. Heavy capital expenditure in the range of US$350 million to US$400 million still looks like the main risk, because slower payback would keep free cash flow and buyback capacity tight.
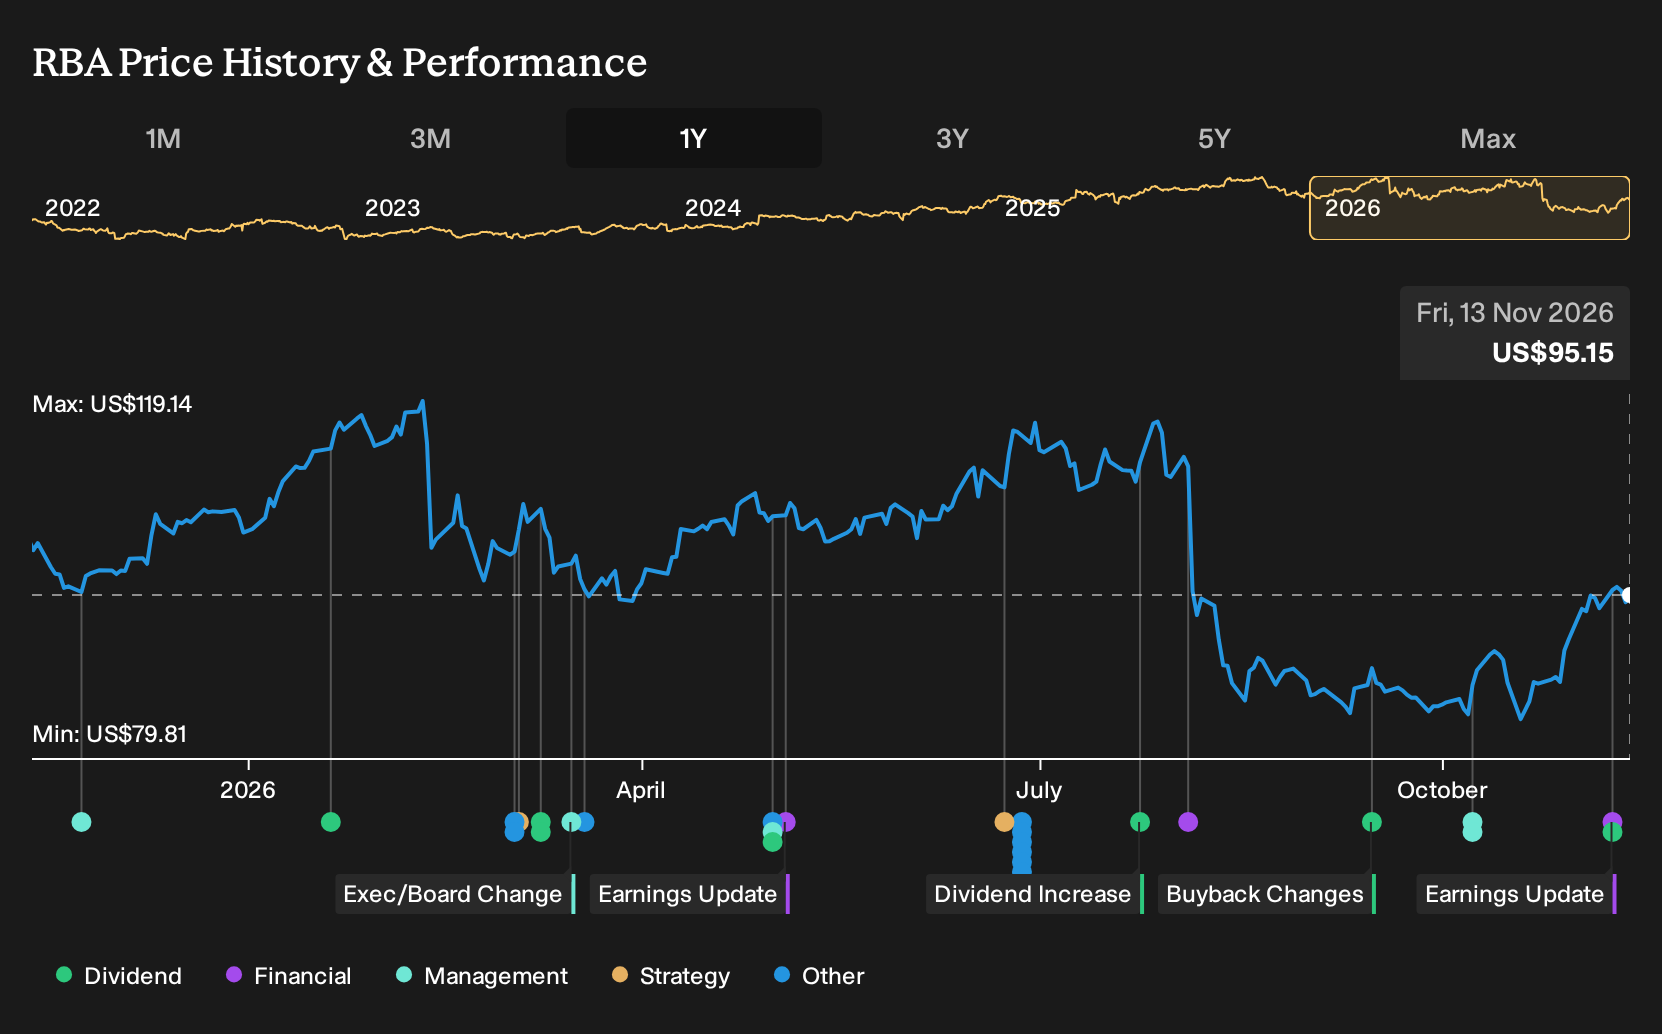
The most relevant fresh data point is RB Global’s third quarter earnings release. Management reported US$1,274.4 million of revenue and US$140.1 million of net income for the period, with both revenue and earnings higher than the same quarter last year. Basic EPS from continuing operations of US$0.70 also moved up from US$0.43.
Those figures matter for the current catalyst question. The analyst consensus Narrative on Simply Wall St focuses on the company converting volume growth in salvage, international contracts and BigIron agriculture into higher profitability. Recent margin pressure from lower service revenue take rates and fuel costs remains in view, yet the latest EPS performance gives investors more recent evidence on how the business is handling those headwinds while investing heavily in technology and facilities.
RB Global's current narrative points to forecast revenue of US$6.3b and earnings of US$946.3 million by 2029, based on analysts assuming 9.1% yearly revenue growth and an earnings increase of about US$509.9 million from US$436.4 million today.
Uncover why RB Global's fair value points to a potential upside of 35% relative to its current price, which could narrow quickly as sentiment catches up.
Exploring Other Perspectives
One alternate view on RB Global leans heavily on capital returns as the real catalyst. The most optimistic analysts were already penciling in earnings of about US$999.6 million by 2029 and annual share count reductions of roughly 2.37% before this earnings, dividend and buyback update. These forecasts were set before the latest results, so you may see those upbeat expectations, compare them with today’s numbers, and reach a very different conclusion from more cautious forecasts.
Explore 3 other RB Global fair value estimates, including one that suggests as much as 146% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your RB Global research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for RB Global. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate RB Global's overall financial health at a glance.
Looking For More Investment Ideas Beyond RB Global?
If RB Global has sharpened your focus on what you want from a business, use that same checklist to scan the wider market. The Simply Wall St Screener helps you filter by balance sheet strength, income potential, or long term upside so you can build a watchlist that actually matches your goals.
- If capital preservation and financial resilience sit high on your list, start with a list of solid balance sheet and fundamentals (24 results) that can handle tough conditions.
- If you prefer opportunities where quality and pricing look more attractive, review a curated 32 high quality undervalued stocks that meet stricter fundamental criteria.
- If future growth matters but you also want businesses the market has not fully focused on yet, scan a 20 high quality undiscovered gems that pair strong fundamentals with lower visibility.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com