


EN
EMCOR Group (EME) Stock May Look Reasonable Despite Its P1 Construction Deal
EMCOR Group has compounded a very large 5 year gain while still trading through bouts of volatility, which naturally raises the question of whether the current share price lines up with what its earnings can support. With fresh deal activity and building services growth in the headlines, the valuation story around EMCOR Group has become more focused on what investors are really paying for each dollar of profit.
- Over the past 5 years the stock has delivered a very large total return of about 4.2x. Anyone buying today is stepping in after a long winning stretch that puts more attention on what the earnings base is truly worth.
- The planned all cash acquisition of P1 Construction and growth in U.S. building services revenue can influence how investors think about EMCOR Group's future earnings power, margin profile and the timing of cash flows that underpin its valuation.
- There is a second opinion on EMCOR Group worth weighing. See what analysts think EMCOR Group's shares could be worth.
The stock's next move may depend on whether EMCOR Group's current earnings are strong enough to justify the price investors are asked to pay today.
If you are weighing whether EMCOR Group's 417.4% five year return still lines up with its earnings, it can help to compare that question across 32 high quality undervalued stocks.
Does EMCOR Group Look Undervalued on Earnings?
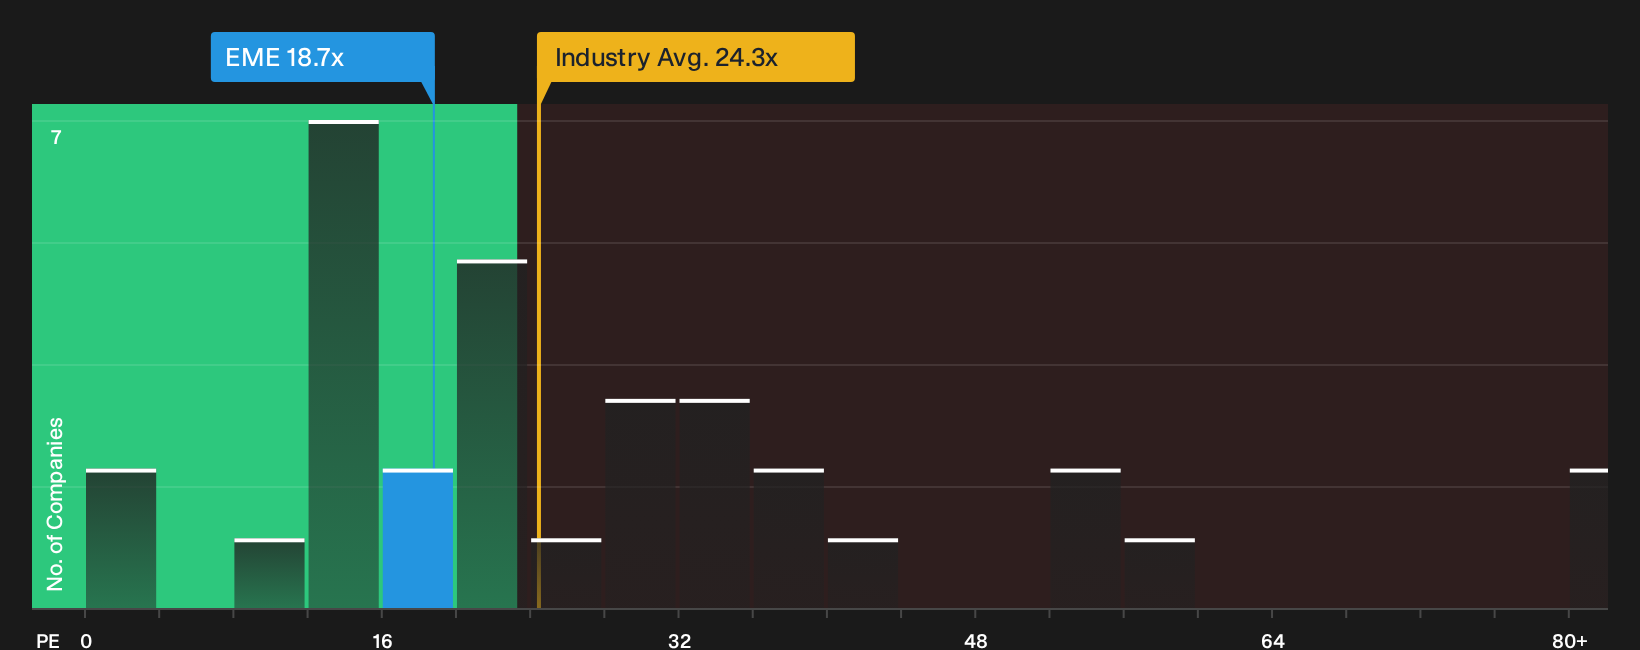
P/E fits EMCOR Group because earnings are the key lens most investors use for established contractors with steady project backlogs. The stock trades on a P/E of 18.7x, which is below the construction industry average of 24.3x and also below the broader peer group around 33.0x. On this framework, the market is paying less for each dollar of EMCOR Group profit than for many similar businesses.
The fair multiple that factors in EMCOR Group's growth profile, margins, size and risk suggests investors might usually expect a higher P/E than where the shares change hands now. This points to the stock looking undervalued on this metric. Because the planned P1 Construction acquisition adds a sizable mechanical and electrical contractor to the portfolio, the current discount comes despite a business mix that is becoming more aligned with complex, higher value projects that many investors often associate with richer earnings multiples. Explore the numbers behind EMCOR Group's P/E valuation.
The EMCOR Group Narrative: What Would Justify Today's Price?
Narratives for EMCOR Group pick up where the P/E puzzle leaves off and spell out which paths for future growth, profitability and earnings could justify a materially higher or lower share price than today. Each scenario sets out the assumptions sitting behind its idea of fair value, which lets you compare those moving parts with EMCOR Group's actual results as they arrive, and they sit on Simply Wall St's Community page.
One of the top narratives on EMCOR Group: 27% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"The main thing that has to go right is that EMCOR Group converts its record backlog and growing mix of complex GMP and cost-plus projects into sustained margins..."
Discover why this Narrative puts EMCOR Group at 27% undervalued.
One more piece of EMCOR Group's puzzle before you decide what the valuation really means
Current earnings and past returns only tell part of the story, because professional estimates for where EMCOR Group might be a few years from now offer a separate lens to compare with today's pricing. Explore where analysts expect EMCOR Group to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com