


EN
Should Stronger Earnings Require Action From Evergy (EVRG) Investors?
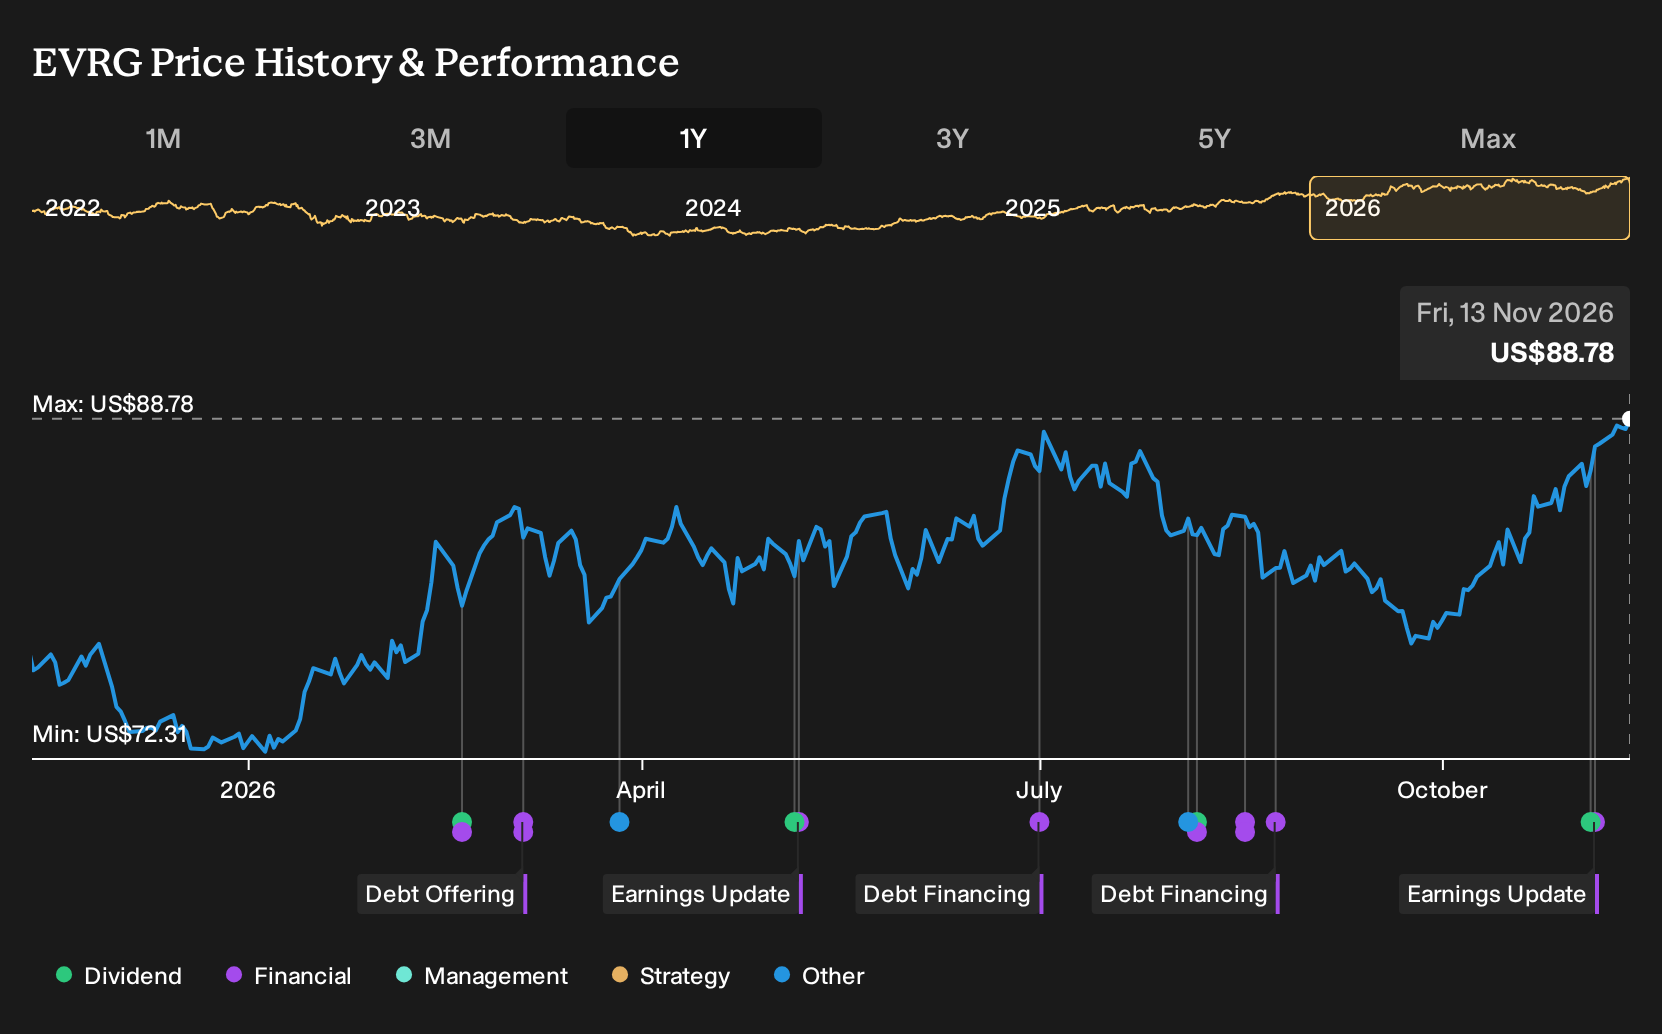
- Evergy reported third quarter 2026 sales of US$2,096.6m and net income of US$612.9m, alongside a quarterly dividend of US$0.7225 per share declared for payment on December 18, 2026.
- The combination of higher third quarter and nine month earnings per share and a maintained cash dividend highlights Evergy's focus on funding a capital heavy plan while still returning cash to shareholders.
- We will now look at how Evergy's stronger third quarter earnings per share profile fits into the existing long term investment narrative.
Scan how Evergy's earnings and dividend story compares with other regulated utilities by reviewing a curated set of 43 power grid technology and infrastructure stocks today.
Evergy Investment Narrative Recap
Owning Evergy means aligning with the analyst consensus narrative on Simply Wall St that its large data center and industrial load growth, along with its US$21.6b capital plan, can be converted into steady, regulated earnings while keeping customer bills acceptable. The stronger third quarter and nine month earnings indicate the plan currently supports higher profitability, but they do not remove execution risk.
The biggest near term swing factor remains how quickly contracted large load customers ramp up and how regulators react as more projects move into rates. The main risk is that higher operations, maintenance, depreciation and interest costs, together with equity issuance, tighten margins. The latest results do not materially change that risk profile.
The recent third quarter report, with basic EPS from continuing operations of US$2.65 and nine month EPS of US$4.24, ties directly into those catalysts. Higher earnings alongside a capital intensive program indicate that Evergy is currently covering higher spending and financing costs from operations. This matters when interest payments have been flagged as not well covered by earnings.
For you as a shareholder or potential investor, the declared US$0.7225 quarterly dividend and the earnings trend need to be considered together. The dividend adds pressure on cash flows that are already supporting grid and generation investment and are funded solely with higher risk external borrowing. Execution on large load projects and rate recovery will be important if Evergy is to sustain both the capital plan and its payout.
Evergy's Forecasts in Context
Evergy's narrative projects US$7.6b revenue and US$1.4b earnings by 2029. This implies 5.9% yearly revenue growth and an earnings increase of about US$300m from current earnings of US$1.1b.
Uncover why Evergy's fair value indicates a 3% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly US$61.64 to US$91.50, which leaves Evergy framed very differently depending on whose model you trust. Those views were formed before the latest earnings and dividend updates. You may want to weigh fresh load growth, regulatory and funding risks while exploring broader community opinions.
Explore another Evergy fair value estimate, including one that suggests it could be worth as much as $91.50.
Decide For Yourself
Don't just follow the ticker, dig into the data and build a conviction that's truly your own.
- A great starting point for your Evergy research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Evergy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Evergy's overall financial health at a glance.
Looking For More Investment Ideas Beyond Evergy?
If Evergy has you thinking about how regulated utilities and other sectors fit together in your portfolio, the next step is to widen the opportunity set. The Simply Wall St Screener can help you quickly surface different kinds of stocks that match the balance of quality, risk and income you are looking for.
- For investors who want income that works harder, consider stocks offering robust yields and payout profiles by reviewing 6 dividend fortresses.
- If capital protection and steadier business profiles matter most to you, focus on companies with stronger resilience scores through the 31 resilient stocks with low risk scores.
- When you want to back businesses with solid finances instead of fragile balance sheets, start with the list of solid balance sheet and fundamentals (24 results) to narrow the field quickly.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com