


EN
Should Profit Rebound Require Action From ICU Medical Stock Investors?
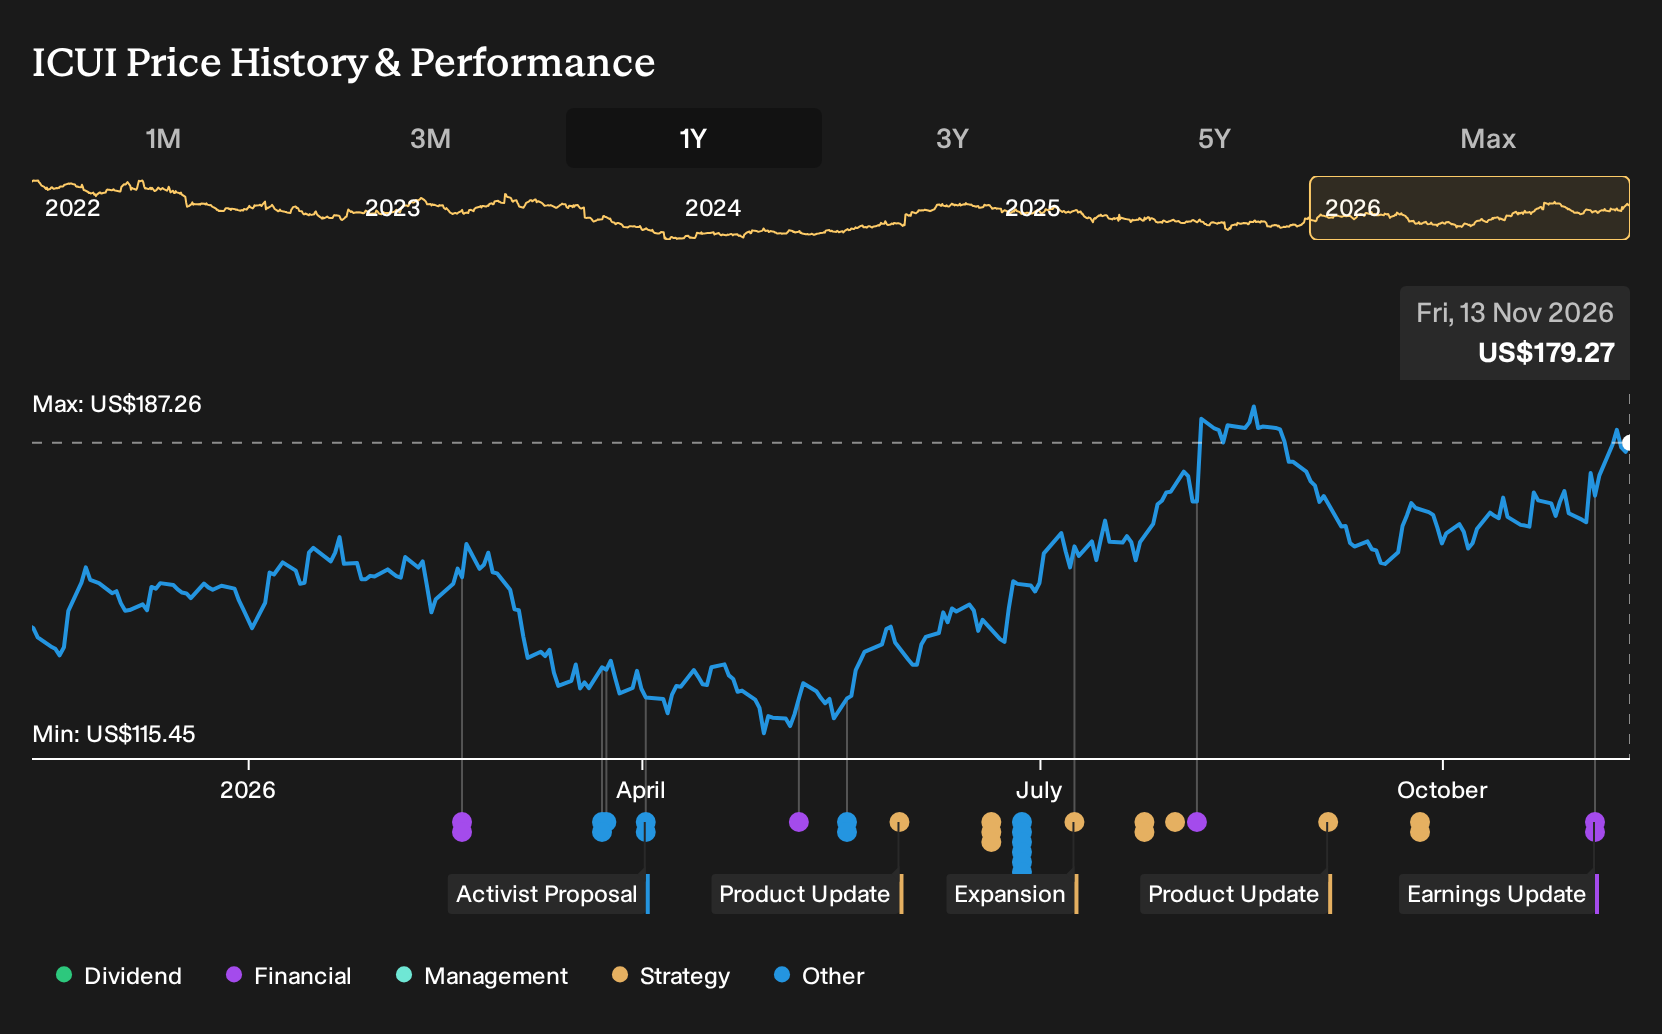
- ICU Medical reported third quarter 2026 sales of US$560.44 million and net income of US$26.85 million, compared with a loss in the prior year, and reaffirmed full year 2026 GAAP net income guidance of US$73 million to US$83 million.
- The shift from a third quarter loss to positive earnings, together with expectations to finish 2026 near the upper end of guidance, highlights how execution and cost control are feeding into ICU Medical's profitability metrics.
- Next, the focus turns to what this profit rebound and high end 2026 guidance could mean for ICU Medical's broader investment narrative.
Scan how ICU Medical’s rebound compares with other profitable healthcare suppliers by reviewing the hand picked list of solid balance sheet and fundamentals (24 results) that are now benefiting from tighter cost control and sturdier finances.
ICU Medical Investment Narrative Recap
To own ICU Medical, you need to believe that consistent hospital demand for infusion therapy and consumables will support a more profitable integrated platform over time. The jump to US$26.85 million in third quarter net income and stronger nine month earnings point to better execution and cost discipline. The near term catalyst remains further margin progress as manufacturing consolidation, tariff management and mix shift play through. The biggest short term risk is that tariff costs and the weaker Vital Care segment keep dragging on profitability and limit how far this earnings rebound can run.
The analyst consensus Narrative on Simply Wall St relies on sustained earnings improvement to support ICU Medical, and the reaffirmed 2026 GAAP net income range of US$73 million to US$83 million aligns with that story rather than changing it. Management now expects results toward the high end, yet tariffs of roughly US$8 million per quarter and the dilutive Vital Care unit still matter. If those pressures do not ease or the consumables and infusion franchises slow, the current earnings step up could prove harder to extend.
The reaffirmed full year 2026 GAAP net income guidance of US$73 million to US$83 million, with management aiming toward the upper end, is the announcement that ties closest to this earnings release. It indicates that ICU Medical views the current profitability level as consistent with prior expectations rather than a one off spike. For you as a shareholder, that is important because the core thesis relies on operating leverage from consolidation, software integration and higher margin devices supporting a multi year earnings build, not just one quarter of clean execution.
This guidance also frames the next set of catalysts and pressure points. If ICU Medical keeps converting its manufacturing and product integration work into steadier net income within that guided range, it helps balance concerns about tariff exposure, mixed historical returns and the Vital Care drag. If progress stalls, the risk case in the analyst consensus Narrative on Simply Wall St comes back into focus, where slower revenue trends, low historical return on invested capital and a relatively high P/E can limit how investors reward the story.
ICU Medical's current assumptions point to revenue of US$2.6b and earnings of US$171.5 million by 2029, based on analysts' expectations. That outlook reflects forecast yearly revenue growth of 5.6% and an earnings increase of roughly US$111 million from US$60.3 million today.
Uncover how ICU Medical's fair value indicates an 8% potential upside to its current price before that discount to ICU Medical closes.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your ICU Medical research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for ICU Medical. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ICU Medical's overall financial health at a glance.
Looking for more ICU Medical investment ideas?
Once you have a handle on ICU Medical, it can help to widen the lens and see how it stacks up against other companies with different risk and income profiles using the Simply Wall St Screener.
- If resilience matters most to you, start with a focused set of 31 resilient stocks with low risk scores that score well on financial strength and business stability.
- For investors who care about quality at a reasonable price, compare ICU Medical with a curated group of 32 high quality undervalued stocks that pair solid fundamentals with compressed valuations.
- If you prefer to hunt where fewer eyes are looking, scan through a targeted mix of 20 high quality undiscovered gems that combine cleaner balance sheets with underfollowed stories.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com