


EN
Restaurant Brands International (QSR) Stock May Be Fully Priced On Franchise Cash Flow
Restaurant Brands International has delivered a 57.1% share price gain over the past 5 years, which naturally puts the focus on whether its current US$75.41 price is properly anchored to the cash it can generate. With that sort of long run behind it, the question now is how well the stock lines up against an intrinsic value estimate built from the company’s own cash flows.
- A 57.1% return across 5 years puts real weight on the question of whether Restaurant Brands International's current valuation is still grounded in its cash generating power.
- The business relies heavily on franchised brands and royalty income, which can support relatively steady cash inflows and shapes how a Discounted Cash Flow (DCF) estimate behaves when growth or reinvestment assumptions change.
- If you'd rather focus on earnings, this one's for you. See why Restaurant Brands International's 16.2x P/E tells a different valuation story.
The stock's next move may depend on whether its present share price is well supported by the cash flows that feed into the Discounted Cash Flow (DCF) intrinsic value estimate.
If you are asking the same question of Restaurant Brands International that you ask of every holding, it can help to compare it with a wider set of companies through the 32 high quality undervalued stocks
Does Restaurant Brands International Look Fairly Valued on Cash Flow?
The Discounted Cash Flow (DCF) approach here takes Restaurant Brands International’s projected free cash flows and discounts them back to today in dollar terms. Latest twelve month free cash flow sits at about $1.57b, which gives the model a solid base rather than forcing it to lean on distant projections.
Analysts feeding into this DCF are assuming Restaurant Brands International continues to generate growing free cash flow over time, with estimates for the early 2030s remaining comfortably above current levels in absolute dollar terms. That path, combined with a mature franchised setup that does not require heavy new investment in every market, leads the model to an intrinsic value estimate that is broadly in line with the current US$75.41 share price. Find out what Restaurant Brands International could be worth using our Discounted Cash Flow (DCF) estimate.
The Restaurant Brands International Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation puzzle for Restaurant Brands International leaves off. They set out what would need to happen to future growth, profitability and earnings for the shares to trade materially higher or lower than today’s level, and place those scenarios on the Community page. Each narrative explains the assumptions behind its view of fair value in plain terms so you can later compare those inputs with the actual results the company reports.
One of the top narratives on Restaurant Brands International: 12% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"Rapid international expansion through a largely franchise-led model, including the plan for about 1,800 net new restaurants by 2028 with around 1,100 net adds in international markets and more than 200 net new Burger King China units backed by improving unit economics and double digit comps there, continues to support recurring, capital light royalty revenue and the potential for higher system-wide sales and earnings…"
Discover why this Narrative puts Restaurant Brands International at 12% undervalued.
One more question for Restaurant Brands International that the valuation does not answer
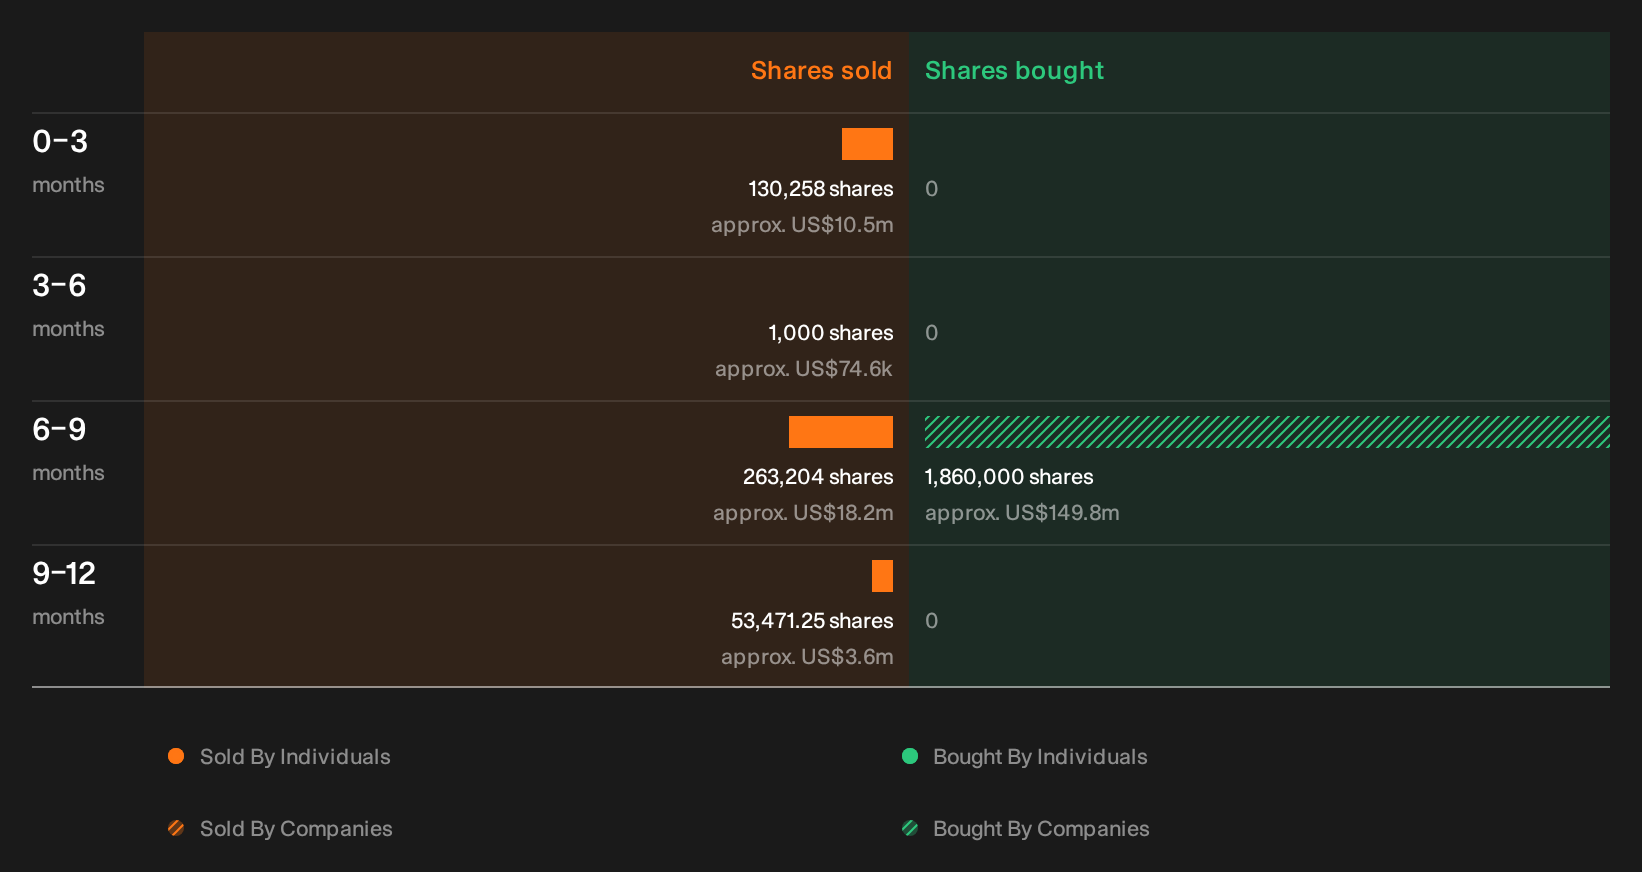
Cash flow and price can line up neatly while insider behavior quietly tells a different story, and recent transactions by key people at Restaurant Brands International are exactly the kind of detail worth checking. See the recent insider selling flagged for Restaurant Brands International.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com