


EN
MGM Resorts International (MGM) Could Be 29% Overvalued On Its Unified Sales Rollout
MGM Resorts International (MGM) has rolled out a unified sales model that gives convention planners one contact to coordinate space and rooms across its Las Vegas properties. Investors now have a fresh operational shift to assess.
MGM Resorts International sits at a share price of US$33.49, with a 30-day share price return of 15.64% that contrasts with a 90-day share price decline of 24.06%, so recent momentum has picked up after a weaker run. Over a longer horizon, total shareholder return of 3.14% over one year and a decline of 24.34% over five years suggests the latest rebound is still playing out against a mixed track record as investors weigh operational changes such as the unified sales model and recent service disruptions, including the Microsoft email outage in Las Vegas.
Scan other event driven opportunities by comparing MGM Resorts International with a curated 32 high quality undervalued stocks that pairs solid fundamentals with potential for a sharper rebound.
The swing from a 24% slide over 90 days to a 16% jump in a month leaves MGM Resorts International at an awkward middle ground. Does that recent reset still skew the risk reward toward buyers when you run the valuation numbers next?
Most Popular Narrative: 29% Overvalued
MGM Resorts International last closed at $33.49, while the bearish analyst Narrative on Simply Wall St anchors fair value closer to $26.00. As a result, the current quote sits well above that cautious mark and frames the next set of risks.
While MGM Resorts International highlights ongoing leverage from asset-light capital allocation and share repurchases funded by selling regional properties at higher EBITDA multiples than its implied trading multiple, the reported debt load of about US$30.02b against US$2.55b of cash and a net-debt-to-EBITDA ratio around 12x could constrain future buybacks or push more cash toward interest and principal payments instead of growth, which would pressure earnings and returns on invested capital.
See why 1 investors see MGM Resorts International as 29% overvalued.
Result: Fair Value of $26.00 (OVERVALUED)
Still, if MGM Resorts International manages to convert record net revenue into stronger earnings, or continues to lift regional property EBITDA, this bearish narrative could soften quickly.
Find out about the key risks to this MGM Resorts International narrative.
Another View: Cash Flows Point the Other Way
Analysts anchoring MGM Resorts International at a fair value of $26.00 lean on earnings and margin compression. A different lens tells a very different story. The SWS DCF model values MGM at $65.24 per share, almost double the current $33.49 quote. That framing presents the stock as undervalued instead of stretched. Which lens do you trust more when earnings are noisy and one off items are large?
To see how that long range cash flow view is built and where the key assumptions sit, Look into how the SWS DCF model arrives at its fair value.
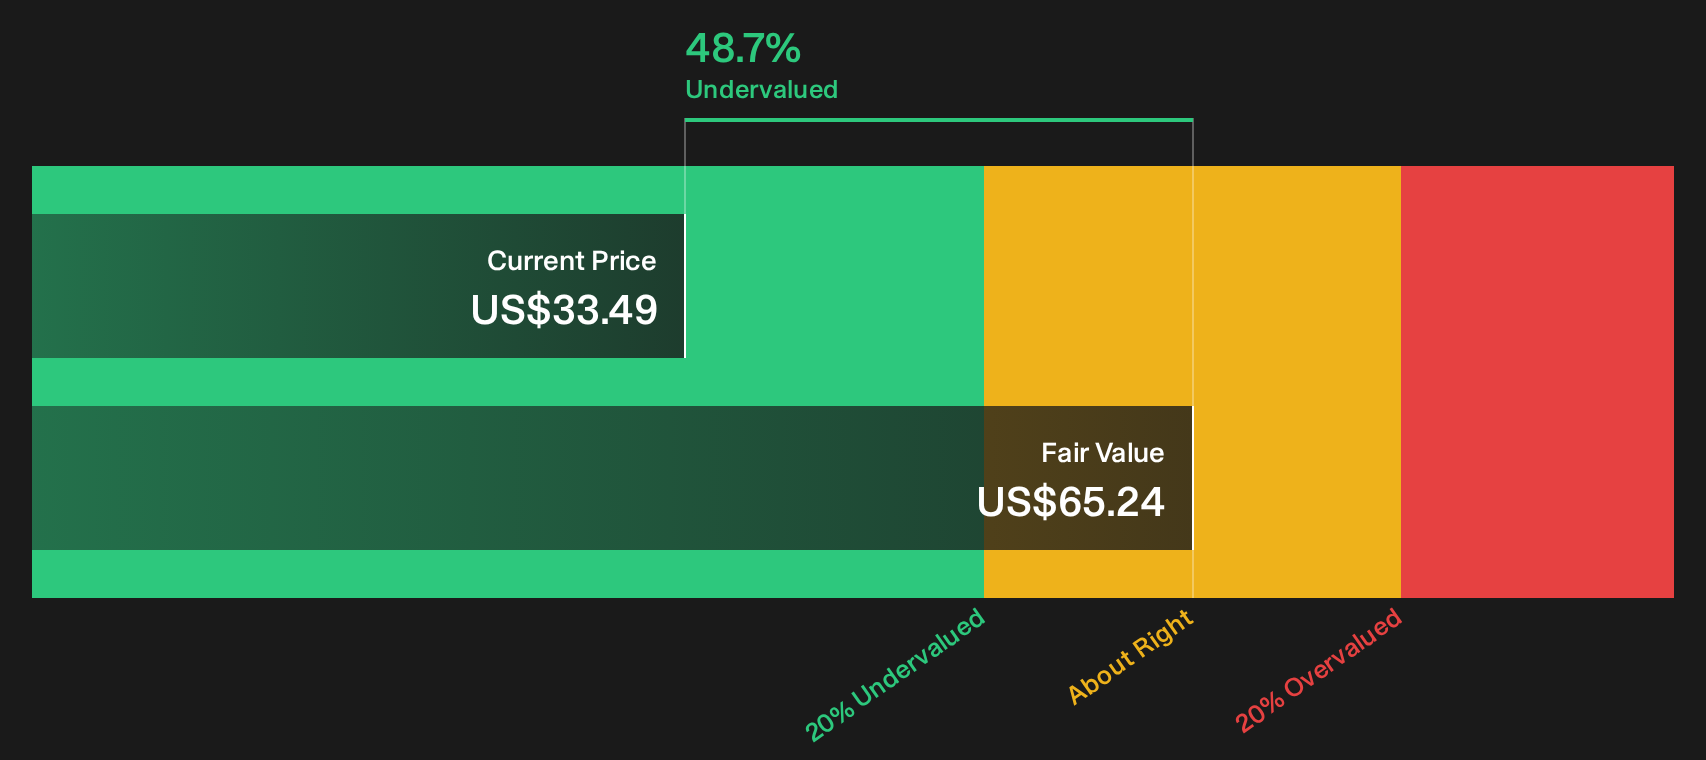
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out MGM Resorts International for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around MGM Resorts International is split, with clear risks on one side and meaningful potential on the other. Move quickly, review the underlying data, and weigh the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond MGM Resorts International?
If MGM Resorts International has sharpened your focus on valuation and risk, broaden your watchlist now with fresh opportunities built from clear, data driven filters.
- Target value with discipline by reviewing a curated set of high quality candidates screened for attractive pricing through the 32 high quality undervalued stocks.
- Prioritise resilience by scanning companies that pair sturdy finances with measured risk scores using the 31 resilient stocks with low risk scores.
- Hunt for potential future standouts before wider attention arrives by working through a focused pool of under the radar opportunities in the 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com