


EN
Top 3 Australian Uranium Stocks To Watch In November 2026
Artificial intelligence related goods have driven a large share of recent global trade growth, and that rush for electricity hungry data centres keeps attention on where reliable power will come from. Australian nuclear linked stocks sit at the crossroads of this shift, supplying fuel, technology and services to reactors worldwide. This article walks through three nuclear energy picks from our screener to help you size up the opportunity.
The three stocks highlighted here offer a compelling starting point if you want exposure to nuclear fuel, enrichment technology and reactor related services for reliable and sustainable power. However, if you want the standouts, these 16 nuclear renaissance stocks are the most outstanding.
Worley (ASX:WOR)
Overview: Worley provides engineering, project delivery and asset management services across global energy sectors, including specialist nuclear power and waste projects.
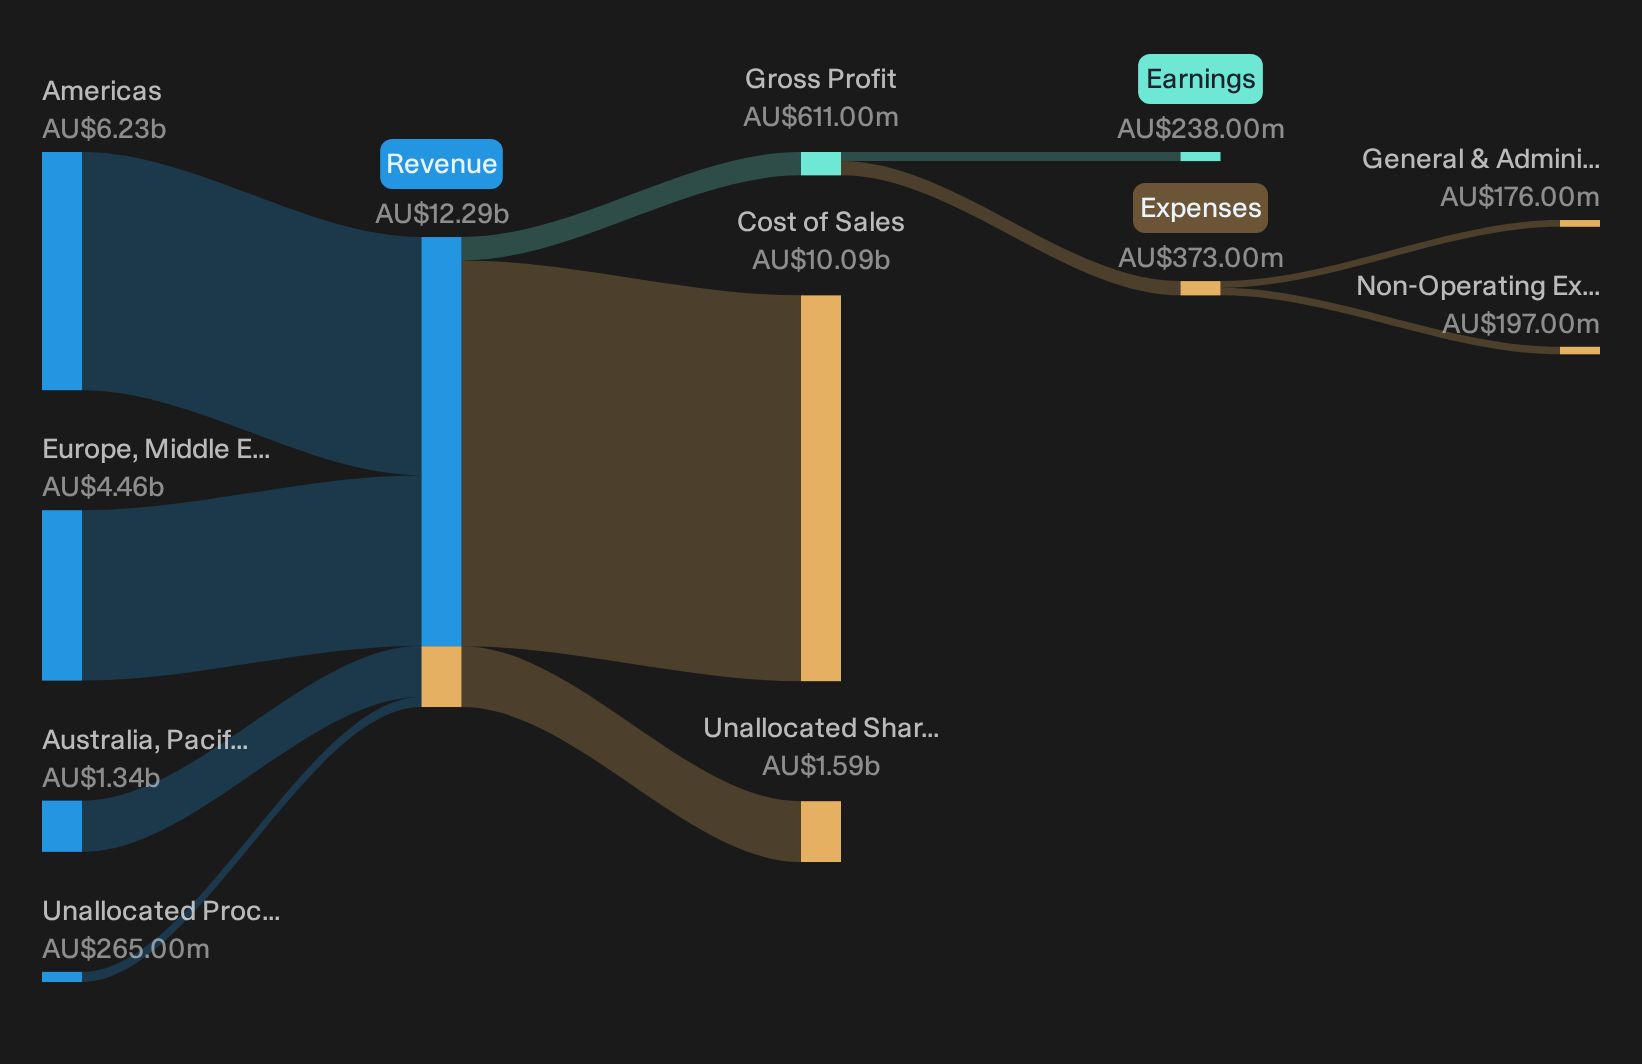
Operations: Worley generates most revenue from the Americas at about A$6.2b, with A$4.5b from EMEA and A$1.3b from APAC.
Market Cap: A$5.0b
Worley matters for this nuclear energy screen because its engineers work directly on reactor projects, lifecycle services and related low carbon infrastructure. The bearish analyst Narrative on Simply Wall St raises questions about how effectively that opportunity translates into durable earnings.
"Although Worley points to a larger factored sales pipeline and more reimbursable EPC and EPCM work in backlog, the recent pattern of aggregated revenue of $12.0b growing only modestly while underlying EBITA fell to $734m shows that turning awards into profitable delivery is not yet proven at scale."
Everything now turns on whether one unresolved pressure in Worley’s nuclear focused project delivery model ultimately lifts margins or keeps them capped.
That margin question is the real hinge, and the full narrative for Worley maps how Worley could shift from pressured delivery to accelerating value as project mix, risk sharing and capital intensity evolve.
Silex Systems (ASX:SLX)
Overview: Silex Systems develops and licenses SILEX laser enrichment technology for uranium fuel used in nuclear power, alongside quantum silicon and medical isotope projects.
Operations: The business generates about A$13 million from the Silex Systems segment and A$2 million from Translucent, with almost all revenue sourced from the United States.
Market Cap: A$858 million
Silex Systems matters for this nuclear energy screen because its SILEX laser uranium enrichment process targets the fuel bottleneck that can limit future reactor output. In addition, the analyst consensus Narrative on Simply Wall St describes how that technology could affect long term royalty flows.
"Progression from the completed TRL 6 pilot to the planned full scale TRL 7 uranium enrichment demonstration in Wilmington, targeted for the end of 2027, positions Silex Systems for potential future royalty revenue growth if commercial equipment performance supports an investment decision on an 8 million SWU facility."
What happens to Silex Systems’ valuation depends on how one unseen pressure around funding and licensing terms ultimately shapes those future royalties.
That pressure point is exactly where the full narrative for Silex Systems steps in, unpacking how funding, licensing and enrichment milestones could accelerate or cap the royalty stream story.

Paladin Energy (ASX:PDN)
Overview: Paladin Energy is a Perth based uranium producer and developer, supplying reactor fuel from its Langer Heinrich mine and Canadian projects.
Operations: Paladin Energy currently generates about $361 million from Namibia, reflecting revenue tied directly to its Langer Heinrich uranium operation.
Market Cap: A$3.2 billion
Paladin Energy matters for this nuclear focused screen because its producing Langer Heinrich mine and the Patterson Lake South development both feed directly into uranium supply for reactors. Tommyt, a Simply Wall St Community investor who wrote the Narrative, argues that contracted sales and a second high grade project give this miner real leverage to the fuel cycle.
"Paladin already has 22.3 million pounds contracted out to 2030 across 12 offtake agreements, with recent sales realised at US$69.90/lb. The ramp-up is tracking well, the contract book provides downside protection, and Fission Uranium adds a high-grade Canadian asset the market is yet to fully value."
What happens if a single key assumption about future uranium demand and project execution shifts will likely matter far more than day to day price moves.
If that assumption is what really moves Paladin Energy, the full narrative for Paladin Energy shows how contracted pounds, pricing and project risks could be quietly reshaping upside potential.
Seeking Fresh Alternatives Beyond Nuclear?
New themes are emerging while attention stays focused on a handful of tickers. Use curated shortlists to spot momentum early, before the broader market reacts.
- Capture strong cash flow momentum by scanning a curated 2 high quality undervalued stocks that combine sturdy balance sheets with earnings power investors have not fully priced in yet.
- Hunt for resilient compounders through a hand picked list of solid balance sheet and fundamentals (12 results) to focus on businesses built to withstand shocks while weaker peers are still adjusting.
- Zero in on dependable income streams with a filtered set of 4 dividend fortresses and identify opportunities before yield-focused investors reassess valuations.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com