


EN
Is Shake Shack (SHAK) Undervalued After Its Third Quarter Earnings Update?
Shake Shack (SHAK) just posted its third quarter update, reporting revenue of US$423.27 million and net income of US$16.49 million. These figures are often watched closely by investors for signs of operational momentum.
Shake Shack’s third quarter update has arrived against a backdrop of a 9.03% 1 month share price return and a 4.30% 7 day move, while the share price return year to date is down 10.17% and the 1 year total shareholder return has declined 17.19%. At the same time, the 3 year total shareholder return sits at 23.12%, suggesting short term optimism around recent earnings is appearing after a tougher stretch for longer term holders.
Scan beyond Shake Shack’s latest quarter and compare it with 32 high quality undervalued stocks, which currently pairs stronger value signals with solid fundamentals.
After a sharp short term rebound, Shake Shack now trades below both analyst targets and an estimated fair value. Is that a genuine discount, or is the market simply pricing in risk more clearly?
Most Popular Narrative: 7.9% Undervalued
On the analyst consensus Narrative on Simply Wall St, Shake Shack screens as modestly undervalued, with a fair value of $81.38 against a last close of $74.98. That gap reflects a detailed view of growth, profitability and risk that goes beyond the latest quarter.
The focus on urban expansion and faster roll out of both domestic company-operated Shacks and international licensed locations, including new formats such as drive thrus and smaller footprints, is being backed by reduced build costs to under US$2 million per unit and over 30% cash on cash returns on recent openings, which can support system wide revenue growth and improving earnings.
See why 15 investors see Shake Shack as 8% undervalued.
Result: Fair Value of $81.38 (UNDERVALUED)
Still, the Shake Shack story can be knocked off course if beef and operating costs continue to compress restaurant level margins or if heavier discounting drags on earnings expectations.
Find out about the key risks to this Shake Shack narrative.
Another View: Shake Shack Through The P/E Lens
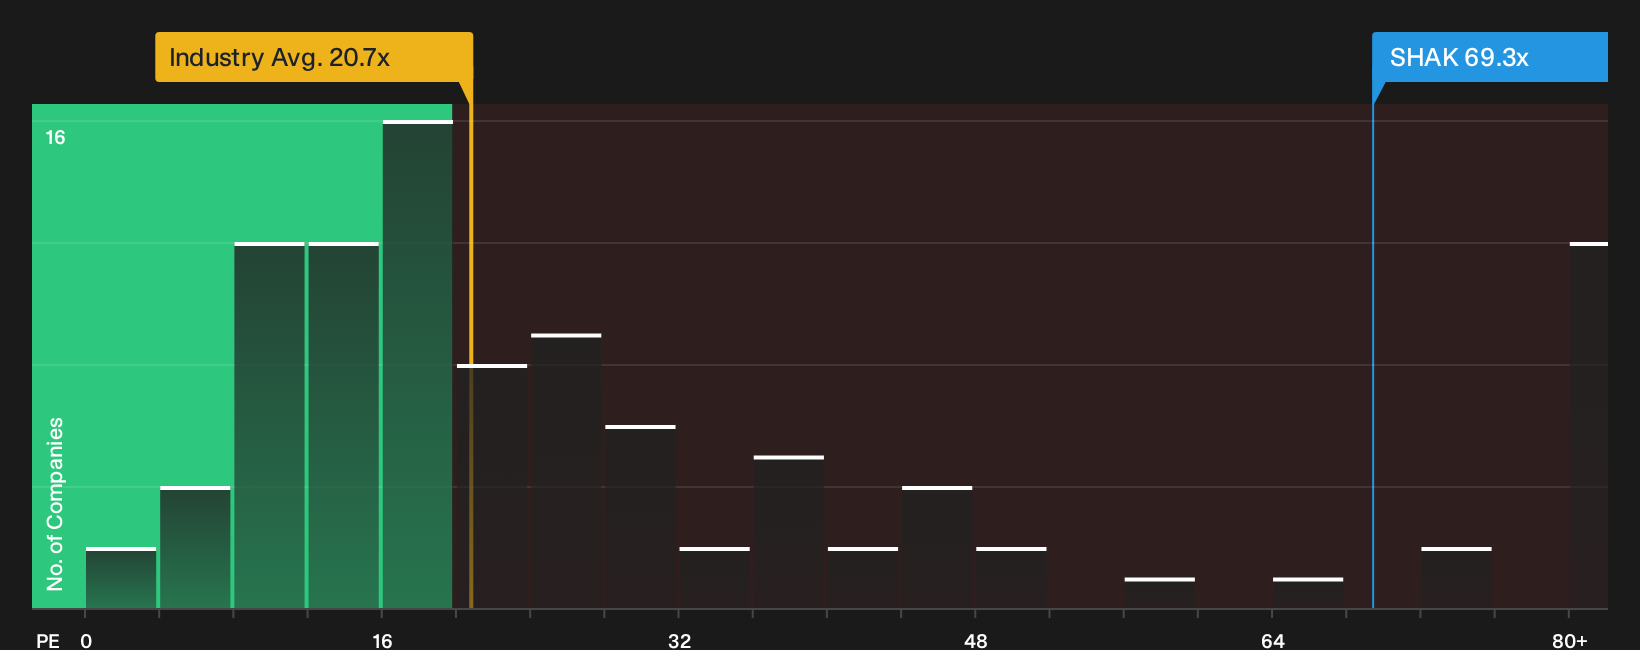
While the narrative presents Shake Shack as modestly undervalued on fair value, the P/E perspective is much tougher. The stock trades at 69.3x earnings, compared with 47.8x for peers and 20.7x for the wider US Hospitality group. The fair ratio sits at 23.3x, which suggests valuation risk if sentiment cools.
For a closer look at how that premium compares with cash generation, our valuation work breaks the numbers down in full, including what would need to change for the share price to better reflect earnings power over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty in this Shake Shack update points to optimism, yet some signals flag valuation risk, so it pays to inspect the details yourself and move early while sentiment is still split. To see exactly which potential upsides investors are focusing on, review the 3 key rewards.
Looking for more investment ideas beyond Shake Shack?
If Shake Shack has your attention, do not stop here. Fresh ideas matter. Broaden your watchlist now and give yourself more options to consider.
- Explore potential income anchors by reviewing stocks we group as potential income opportunities through the 6 dividend fortresses.
- Look for quality at a potential discount with companies that pair appealing value indicators with solid fundamentals using the 32 high quality undervalued stocks.
- Focus on capital preservation by assessing companies that carry lower risk profiles via the 31 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com