


EN
How Investors May Respond To Match Group Stock After Raised Guidance
- Match Group reported third quarter 2026 sales of US$891.23 million and net income of US$174.36 million, with higher basic and diluted earnings per share from continuing operations compared with the same period in 2025.
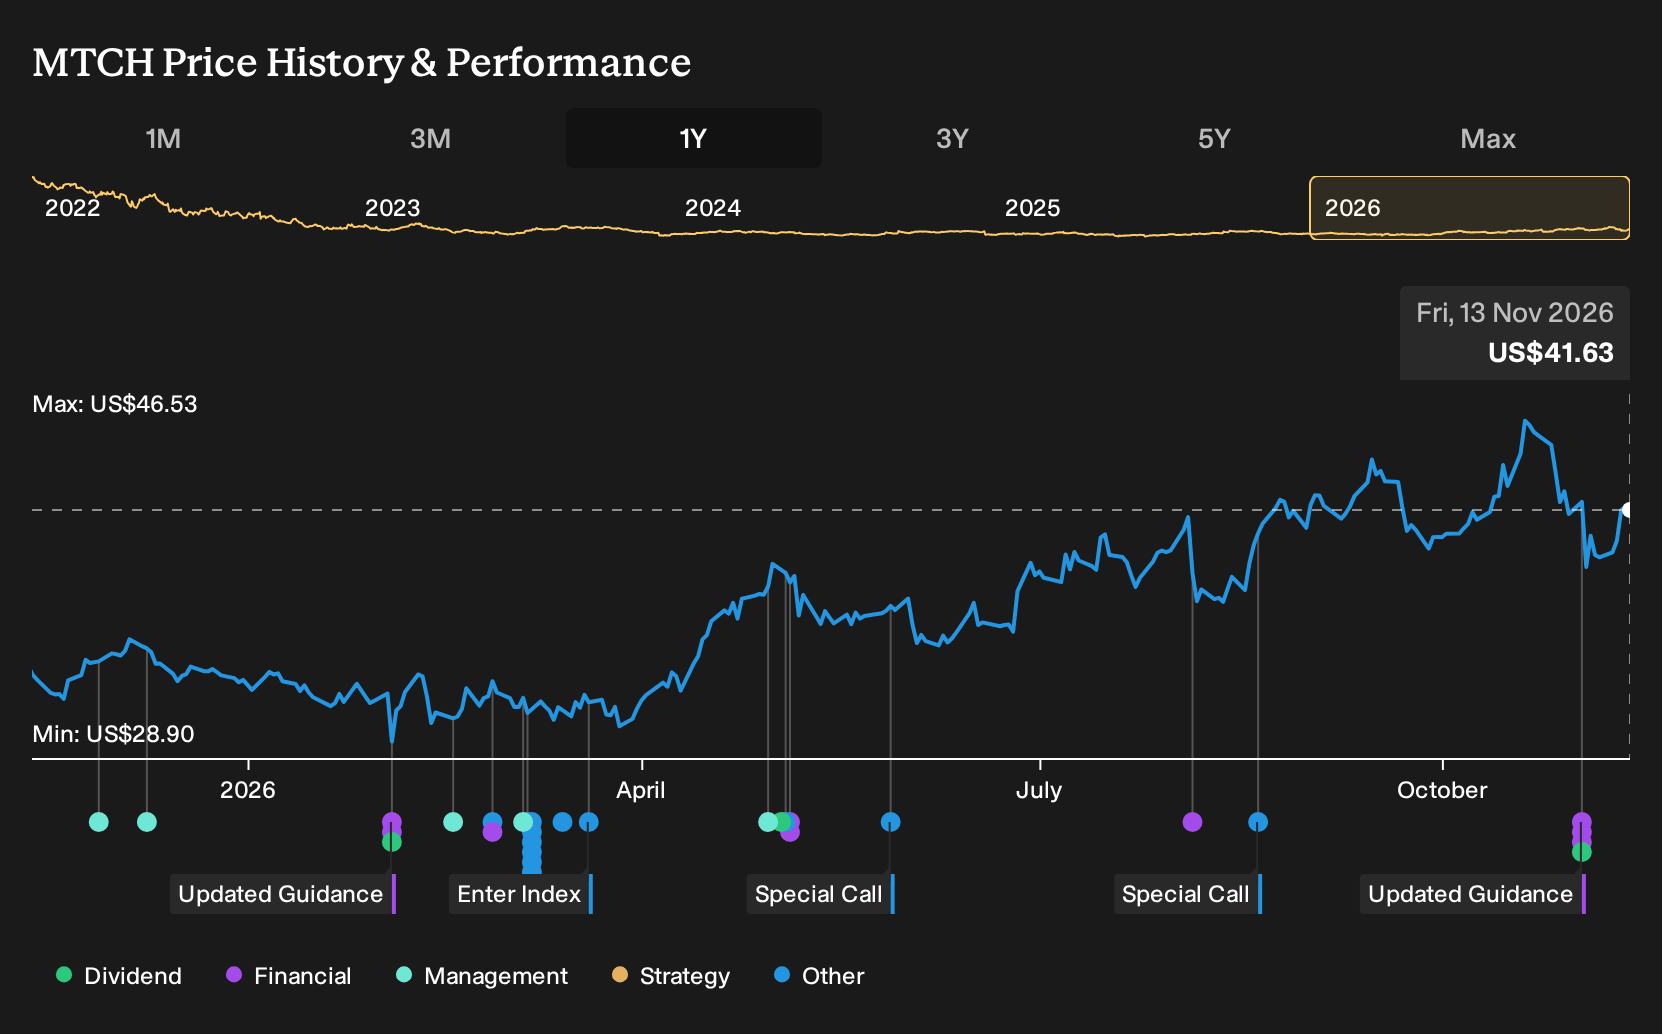
- The business kept revenue broadly steady for the first nine months of 2026 while lifting net income and earnings per share, then raised full year guidance slightly above its earlier range and affirmed a US$0.20 per share cash dividend payable in January 2027.
- Now the focus is on how Match Group's firmer earnings and slightly higher full year guidance may influence the broader investment narrative from here.
Compare Match Group's steady earnings story with other companies that pair resilient profits and balance sheets using our hand picked list of solid balance sheet and fundamentals (24 results).
Match Group Investment Narrative Recap
To hold Match Group, you need to believe its dating brands can stabilise usage and payers while product work at Tinder and Hinge, highlighted in the analyst consensus Narrative on Simply Wall St, gradually feeds through to steadier earnings. The third quarter showed that this scenario is still plausible, with roughly flat nine-month revenue and higher profitability.
The key near-term factor is whether recent product changes can offset competitive apps and pressure on payer metrics called out in earlier quarters. The biggest risk remains that softness in usage and drag from the Everyone and Everything portfolio keep revenue flat or weaker, which would limit the benefit of efficiency gains.
The most relevant recent news is Match Group's guidance for the fourth quarter of 2026. Management is planning for total revenue of US$865 million to US$875 million, which it describes as down 1% to flat year over year, together with net income of US$172.5 million to US$177.5 million and a 20% net income margin at the midpoint.
For investors, that guidance outlines both the potential catalyst and the risk. If Tinder and Hinge product work begins to show up in steadier payers and supports that 20% margin, it aligns with the earnings resilience that the analyst consensus Narrative on Simply Wall St focuses on. If competitive pressure or portfolio weakness undercuts those targets, the outlook relies more heavily on cost control than on stronger engagement.
Match Group's narrative projects US$3.9b revenue and US$822.4m earnings by 2029. This assumes 4.2% yearly revenue growth and an earnings increase of about US$101m from current earnings of US$721.4m.
Uncover why Match Group's fair value indicates a 9% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One bullish twist on Match Group focuses on a possible upside surprise in engagement from AI driven features and Hinge expansion. Before this earnings update and raised 2026 guidance, the most optimistic analysts were already pencilling in US$4.0b of revenue and US$836.7m of earnings by 2029. Those views may shift. Compare them with your own expectations.
Explore 5 other Match Group fair value estimates, including one that suggests as much as 100% upside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Match Group research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Match Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Match Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Match Group?
Once you have a view on Match Group, it can help to compare that opinion against a broader watchlist of companies with different strengths, income profiles and risk levels using the Simply Wall St Screener.
- For investors hunting for potential mispriced opportunities with strong fundamentals, scan the market using our curated 32 high quality undervalued stocks.
- If income reliability is a priority and you want candidates with higher yields, focus on potential cash generators with the 6 dividend fortresses.
- For a calmer ride through market swings, filter for sturdier balance sheets and lower risk profiles using the 31 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com