


EN
Top 3 Australian Founder Led Stocks With Revenue Growth Over 7%
Artificial intelligence is suddenly at the top of global financial stability worries, with central banks flagging complex funding structures and stretched expectations around AI infrastructure. That kind of scrutiny puts leadership quality squarely in focus. Founders who still run their Australian businesses often have more at stake than any hired executive. This article walks through three founder-led stocks from our local screener that may warrant closer examination at this time.
The three stocks highlighted here offer a compelling starting point if you want exposure to founder led businesses where leadership is personally tied to long term results. However, if you want the strongest names, these 8 top founder-led companies are at the top of the list.
Flight Centre Travel Group (ASX:FLT)
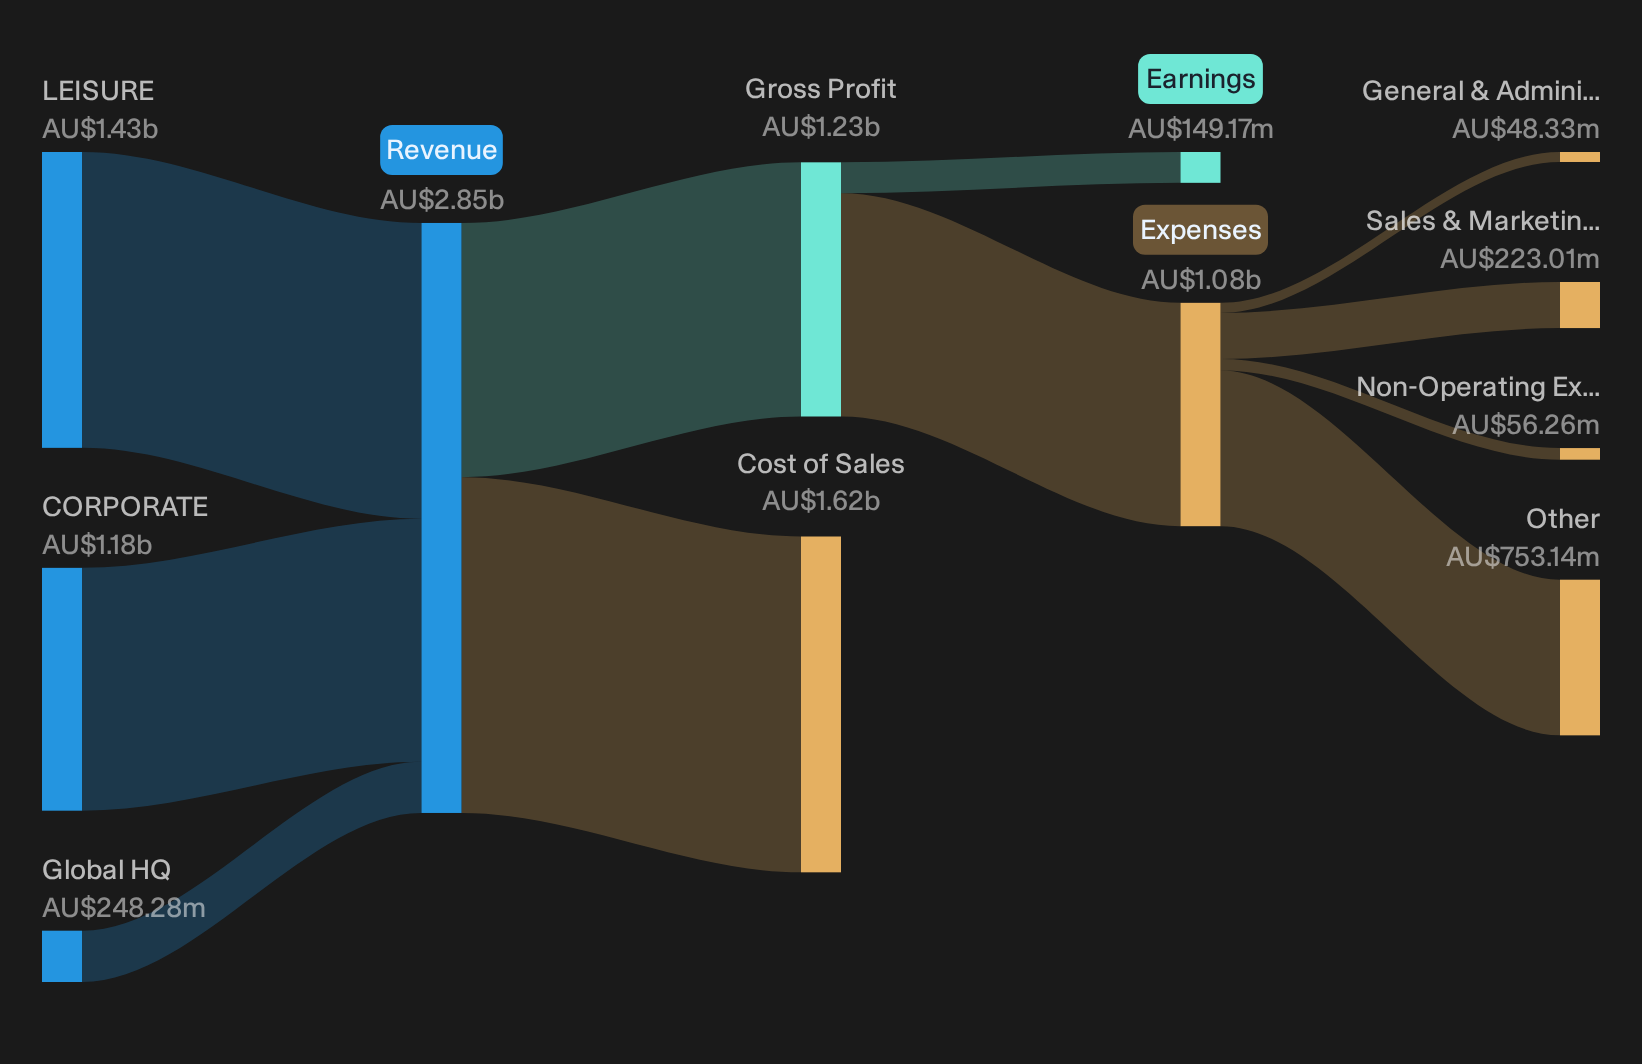
Overview: Flight Centre Travel Group runs founder-influenced leisure and corporate travel agencies worldwide, connecting customers to airlines, hotels, tours and related services.
Operations: Flight Centre generates A$1.43b from leisure travel, A$1.18b from corporate operations, and A$248 million from global head office functions.
Market Cap: A$2.44b
For the Founder-Led Companies theme, Flight Centre Travel Group matters because the founding influence still shapes how capital is allocated, risk is taken and growth is pursued. This is exactly what the bearish analyst Narrative on Simply Wall St is testing in its most cautious scenario.
"Although Flight Centre is reallocating capital toward cruise, luxury, Meetings & Events and foreign exchange, the recent guidance cut linked to a mix shift toward lower margin carriers highlights a risk that product mix and supplier choice continue to dilute yield, which can cap revenue per transaction and keep operating margins under pressure."
The real swing factor for Flight Centre Travel Group now is whether one quiet shift in its business mix ultimately widens or squeezes profitability.
That mix shift risk is only half the story, and the full narrative for Flight Centre Travel Group explains where founder-led decisions could either accelerate returns or keep profitability stuck in low gear.
Mesoblast (ASX:MSB)
Overview: Mesoblast develops founder-led regenerative medicine therapies based on mesenchymal lineage cells, aiming to commercialize treatments for severe inflammatory and cardiac conditions.
Operations: Mesoblast generates about $120 million in revenue from developing and commercializing its allogeneic cellular medicines platform.
Market Cap: A$2.51b
Mesoblast catches the eye in this founder-led screen because the original scientific vision still shapes which cell therapies move toward market and how quickly commercial execution is pushed. This is a focus that the bullish analyst Narrative on Simply Wall St leans into when sizing up what could go right from here.
"The planned “Generation 2” manufacturing process that adds a proprietary recombinant growth-factor supplement, together with automation and US onshoring of production, points to a step change in cell yields and cost of goods. This could widen gross margins as higher volume indications come through."
What really matters now for Mesoblast is how one quietly shifting balance between volume growth and capital discipline eventually reshapes earnings power.
That earnings power question is exactly what the full narrative for Mesoblast tackles, mapping how clinical traction and funding decisions could accelerate or stall the next phase for Mesoblast.

Harvey Norman Holdings (ASX:HVN)
Overview: Harvey Norman Holdings runs founder-controlled retail, franchise and property operations, with Gerry Harvey’s majority influence anchoring long-term decisions and governance.
Operations: Harvey Norman earns about A$951.9 million in New Zealand, A$787.2 million in Singapore and Malaysia, A$776.9 million in Ireland, plus contributions from Slovenia and Croatia, the UK and other non-franchised retail activities.
Market Cap: A$5.57b
Harvey Norman Holdings gives this founder-led screener real teeth, since Gerry Harvey’s controlling stake links big retail and property calls directly to long-term owner incentives. Robbo, a Simply Wall St Community investor who wrote the Narrative, uses this as context for a key earnings quality reminder.
"It is worth noting, however, that just over 20% of 2025 profit can be attributed to property revaluations, non-cash gains that can be volatile and are not recurring operational earnings."
For investors, what happens when one quiet driver of cash returns shifts will likely matter more than any headline P/E comparison or yield figure.
That quiet driver is exactly what the full narrative for Harvey Norman Holdings unpacks, revealing where earnings quality, cash generation and founder control could be decoupling from the headline numbers.

Seeking Fresh Alternatives Before They Fly
Fresh opportunities often move first and then get crowded. Look for potential breakouts while information is still relatively under the radar and momentum has not fully developed.
- Identify cash generative outliers before they are widely discussed by screening for list of solid balance sheet and fundamentals (12 results) that can keep funding growth when conditions tighten.
- Explore income-focused ideas with strong cash return profiles by scanning 4 dividend fortresses built to prioritise reliable cash returns while prices are dropping out of favour.
- Monitor fast-moving exposure to digital assets through 23 cryptocurrency and blockchain stocks before the next sentiment shift draws more attention to the sector.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com