


EN
DocuSign (DOCU) Stock Trades At A Premium To Its Earnings
DocuSign has ridden a powerful rebound in recent years, which puts fresh attention on a simple question for anyone looking at the stock today. Do the company’s earnings justify where the shares now trade, or has sentiment moved further than its profit profile supports?
- Over the past 3 years the stock has delivered a total return of 88.0%. As a result, a lot of future earnings expectations are now effectively embedded in the price you see on screen.
- Recent moves into AI powered procurement intelligence and contract analytics may support expectations for how efficiently DocuSign can turn agreement workflows into earnings over time, and therefore what kind of profit stream investors are implicitly paying for.
- Your read on DocuSign is one view; the desks covering it have another. See what analysts think DocuSign's shares could be worth.
The issue now is whether the current share price can be fully explained by DocuSign’s earnings when set against the Fair Ratio benchmark.
If you are weighing DocuSign against other AI focused contract and automation plays, it can help to compare it with 38 AI small caps.
Is DocuSign Getting Expensive on Earnings?
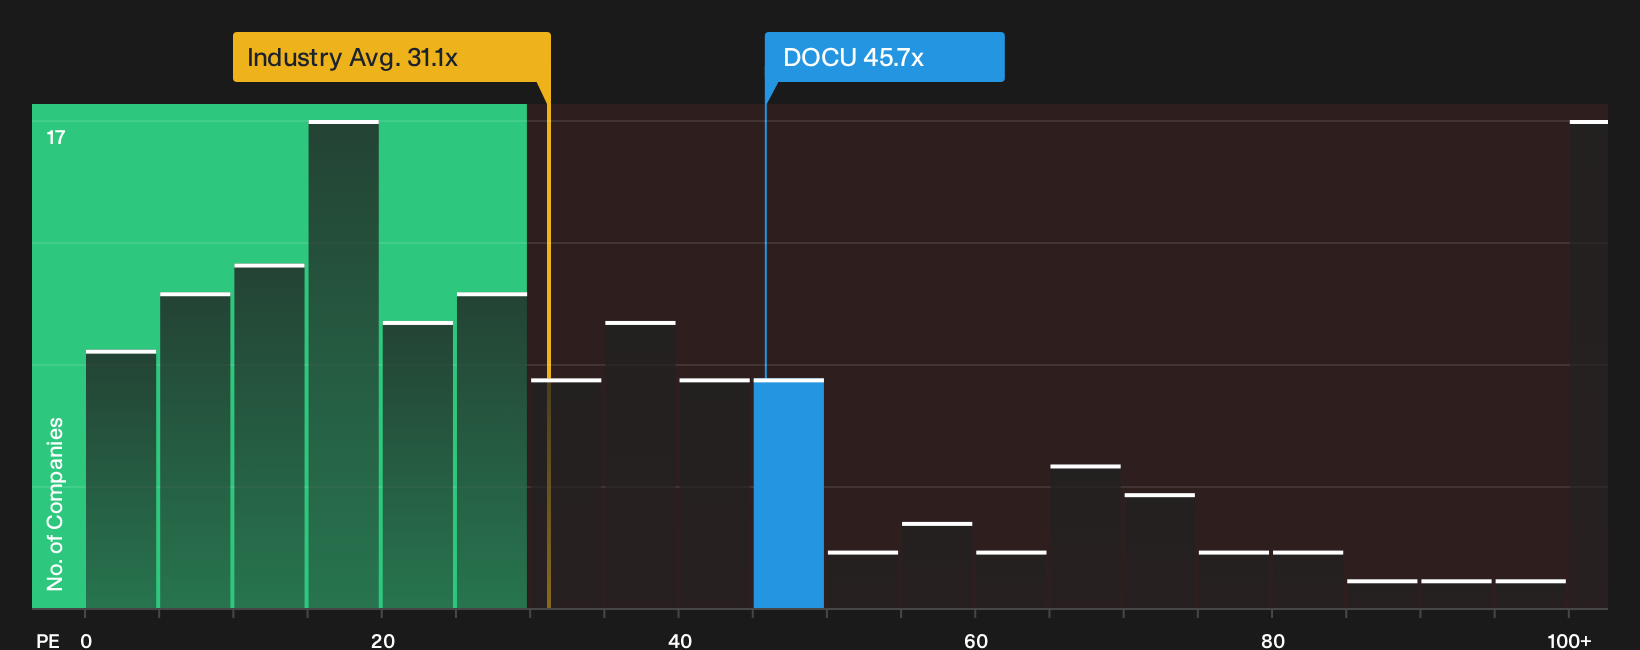
The P/E ratio works well for DocuSign because the discussion revolves around how much investors are paying for each dollar of earnings from its agreement and AI platforms. On this lens, the stock trades at about 45.7x earnings, compared with roughly 31.1x for the broader Software industry and about 43.5x for peers. That puts the multiple at a premium to both the sector backdrop and a group of similar businesses.
The Fair Ratio, which reflects what a more tailored P/E might look like once growth quality, margins, size and risk are baked in, points to DocuSign stock being priced above that reference point, so it screens as overvalued on this framework. Because DocuSign has been pushing hard into AI powered procurement intelligence and contract analytics through deals like the Suplari acquisition and partnerships around contract intelligence, enthusiasm for those efforts already shows up in how much investors are willing to pay for current earnings. Explore the numbers behind DocuSign's P/E valuation.
The DocuSign Narrative: What Would Justify Today's Price?
DocuSign Narratives pick up where the valuation puzzle leaves off and outline what kind of future for growth, margins and earnings would need to occur for the stock to be worth materially more or less than today’s market price. All of this is hosted on Simply Wall St’s Community page. Each scenario links its numbers to a specific view on how DocuSign's scale, profitability and risk profile could evolve, which you can track as fresh information is released.
The two live Narratives on DocuSign split on how much upside is left in Intelligent Agreement Management and the current earnings multiple.
Bull case: 6% undervalued
The bullish analyst Narrative on Simply Wall St sees DocuSign’s AI agreement layer and capital returns as underappreciated by the market today.
"As DocuSign expands Intelligent Agreement Management from 15.1% of ARR using over 300 million ingested documents and materially lower AI processing costs, there is room for IAM-centric workflows to reshape the revenue mix toward higher value agreement intelligence rather than basic eSignature volume…"
Discover why this Narrative puts DocuSign at 6% undervalued.
Bear case: 12% overvalued
The analyst consensus Narrative on Simply Wall St argues that expectations around AI driven agreement workflows already sit high in the current price.
"DocuSign is reporting high single digit revenue growth even as IAM gains share of ARR, so if investors continue to see this as the weakest guidance profile among productivity peers then the stock may be priced for lower growth, which could pressure future revenue expectations and limit support for earnings multiples…"
Explore why this Narrative puts DocuSign at 12% overvalued.
One unresolved question on DocuSign that could change the picture
DocuSign’s pricing on earnings tells only part of the story, because Simply Wall St’s checks have also flagged specific areas of concern that investors may want to weigh before getting comfortable with the risk profile. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com