


EN
Why Suzuken (TSE:9987) Is Back In The Spotlight
Suzuken (TSE:9987) has put shareholder perks in focus after a recent stock split, with a 12 November 2026 board meeting scheduled to expand its benefit program for both existing and new investors.
Suzuken’s recent board decision comes after a sharp rebound in the share price. The 30 day share price return is 10.17% and the 90 day gain is 15.94%, even though the year to date share price performance is still down 6.74% and the 1 year total shareholder return is slightly negative at 0.51%. By contrast, longer term total shareholder returns of 20.84% over three years and 109.01% over five years point to much stronger historical compounding for long term holders.
Compare Suzuken’s perk-focused move with other potential opportunities by scanning a curated set of 19 high quality undervalued stocks that also combine solid balance sheets with disciplined cash generation.
Bulls view Suzuken’s richer perks and long record of compounding as a setup for further upside. Bears see a perk-fueled bounce that already prices in the good news. Which case do the numbers support as valuation comes into focus?
Preferred Price-to-Earnings of 10.4x: Is it justified?
Suzuken screens as inexpensive on earnings. The stock closed at ¥2,898.5 while trading on a P/E of 10.4x, which is flagged as good value against both peers and the wider JP Healthcare sector.
The P/E ratio shows how much investors are paying for each ¥1 of Suzuken's profit. For a distributor with steady but modest forecast earnings growth of 1.96% per year, a lower multiple can signal that the market wants more proof that recent profit expansion is durable, especially with large one off items in the latest 12 month figures.
On the numbers provided, the discount looks clear. Suzuken trades on a P/E of 10.4x compared with an estimated fair P/E of 17.5x and an industry average of 14.7x. This is a sizeable gap that the market could move towards if confidence in earnings quality and growth firms up.
Explore the SWS fair ratio for Suzuken.
Result: Price-to-Earnings of 10.4x (UNDERVALUED)
Still, Suzuken’s thin 1.96% forecast earnings growth and reliance on Japan as its sole reported market leave the story sensitive to margin pressure or domestic policy shifts.
Find out about the key risks to this Suzuken narrative.
Another view on Suzuken using cash flows
The earnings multiple paints Suzuken as cheap. The SWS DCF model goes further and values future cash flows at ¥9,078.26 per share, compared with the current ¥2,898.5 price. That is a very wide gap on paper, so how much faith should you place in a single long term model?
Look into how the SWS DCF model arrives at its fair value.
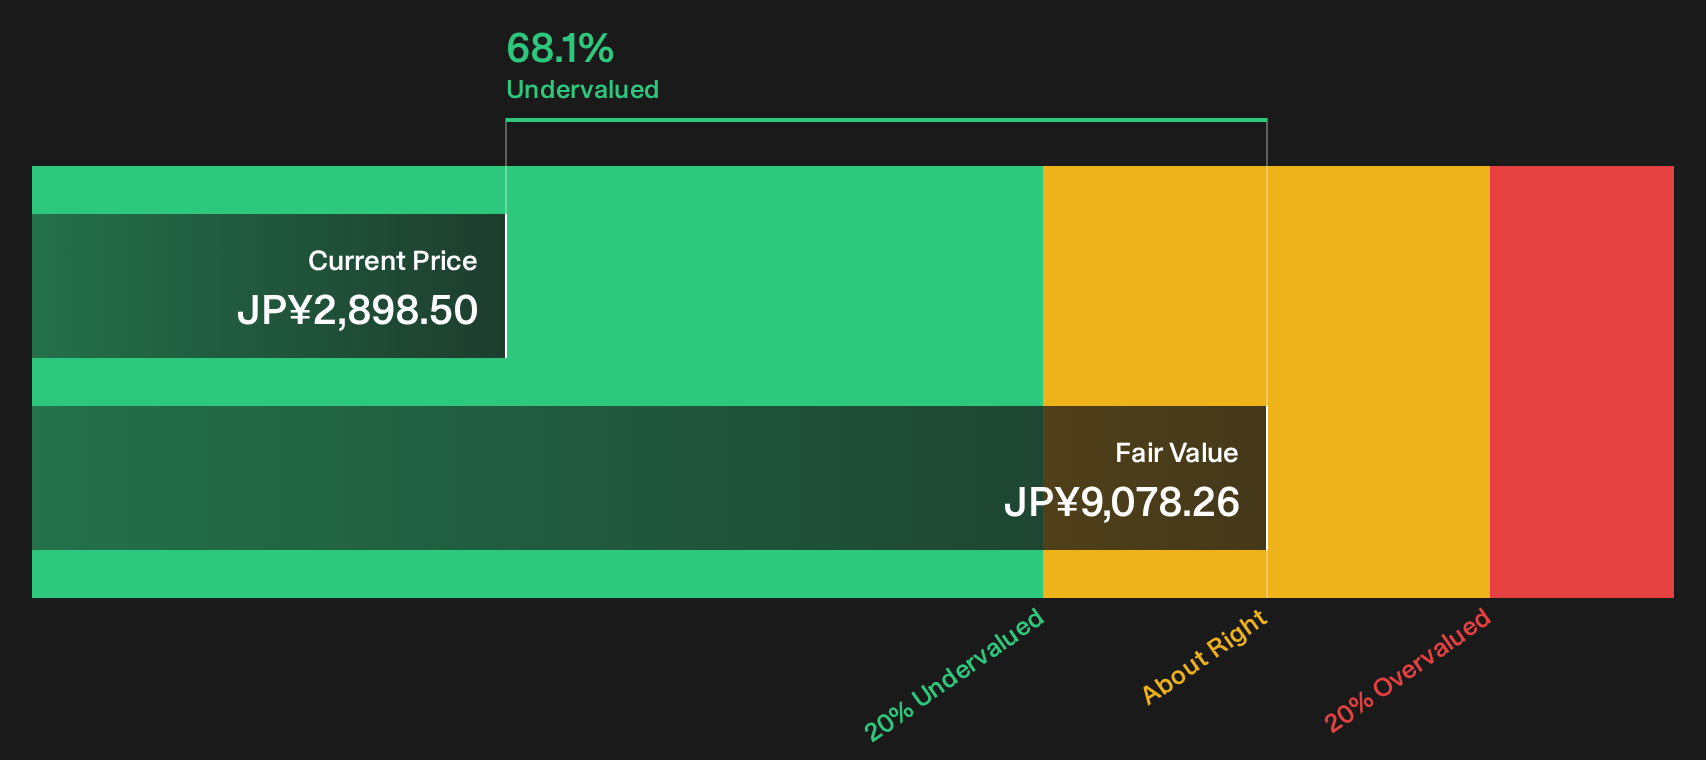
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Suzuken for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 19 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
The mix of upbeat and cautious signals around Suzuken only matters if you weigh them yourself and act while the data is fresh. To see both sides of that story in one place, review the 5 key rewards and 1 important warning sign
Looking for more investment ideas beyond Suzuken?
If Suzuken has your attention, do not stop there. Fresh ideas can sharpen your edge and keep your watchlist focused on quality and risk control.
- Target potential mispricing and widen your opportunity set by scanning a curated pool of 19 high quality undervalued stocks that pair appealing valuations with fundamental strength.
- Strengthen your income stream by reviewing a focused group of 28 dividend fortresses that combine higher yields with an emphasis on resilience.
- Dial down portfolio stress by concentrating on a 20 resilient stocks with low risk scores that highlights companies with sturdier financial profiles and lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com