


EN
Foraco International And 2 Canadian Lithium Stocks To Watch
AI related goods now drive most of global trade growth, and that surge needs huge volumes of battery metals. Canadian lithium mining stocks sit close to this supply story, feeding processing hubs that support data centers, electric vehicles, and grid storage. If you care about where that money flows next, this list highlights three lithium miners and processors from our screener that many investors are watching closely.
The three lithium stocks below are just a starting sample, and the full screen surfaced 11 more companies with equally compelling narratives that are not covered here.
If you want to go wider and deeper on global lithium miners and processors, head straight into the Lithium Mining screener to identify, analyze, and prioritize your highest conviction ideas.
Foraco International (TSX:FAR)
Overview: Foraco International provides contract drilling services for lithium and other minerals, supporting resource discovery and production for mining clients worldwide.
Operations: The group generates about US$255 million from mining drilling and US$45 million from water services across North America, South America, Asia Pacific, and EMEA.
Market Cap: CA$221 million
Foraco International matters to this Lithium Mining theme because its rigs and drilling crews help turn potential lithium deposits into defined projects, and the bearish analyst Narrative on Simply Wall St frames what could happen if strong activity struggles to convert into healthier profitability.
"Although Foraco International is benefiting from stronger metals exploration activity and described an overflowing global tender pipeline, the drop in gross margin from 20.5% to 15.5% in Q2 2026 and from 18% to 13% for H1 shows that higher labor, consumables, mobilization costs, and early-stage contract inefficiencies could keep future contract wins from translating into the revenue and net margin uplift many investors expect."
The optimistic case for Foraco International in lithium drilling really hinges on one unresolved pressure that could sharply reset how future work gets priced.
Pricing pressure is only half the story, and the full narrative for Foraco International shows how contract structures, fleet mix, and lithium exposure could still accelerate Foraco International from here.

Altius Minerals (TSX:ALS)
Overview: Altius Minerals is a royalty and streaming company that earns payments from lithium linked and other commodity producing mines across its portfolio.
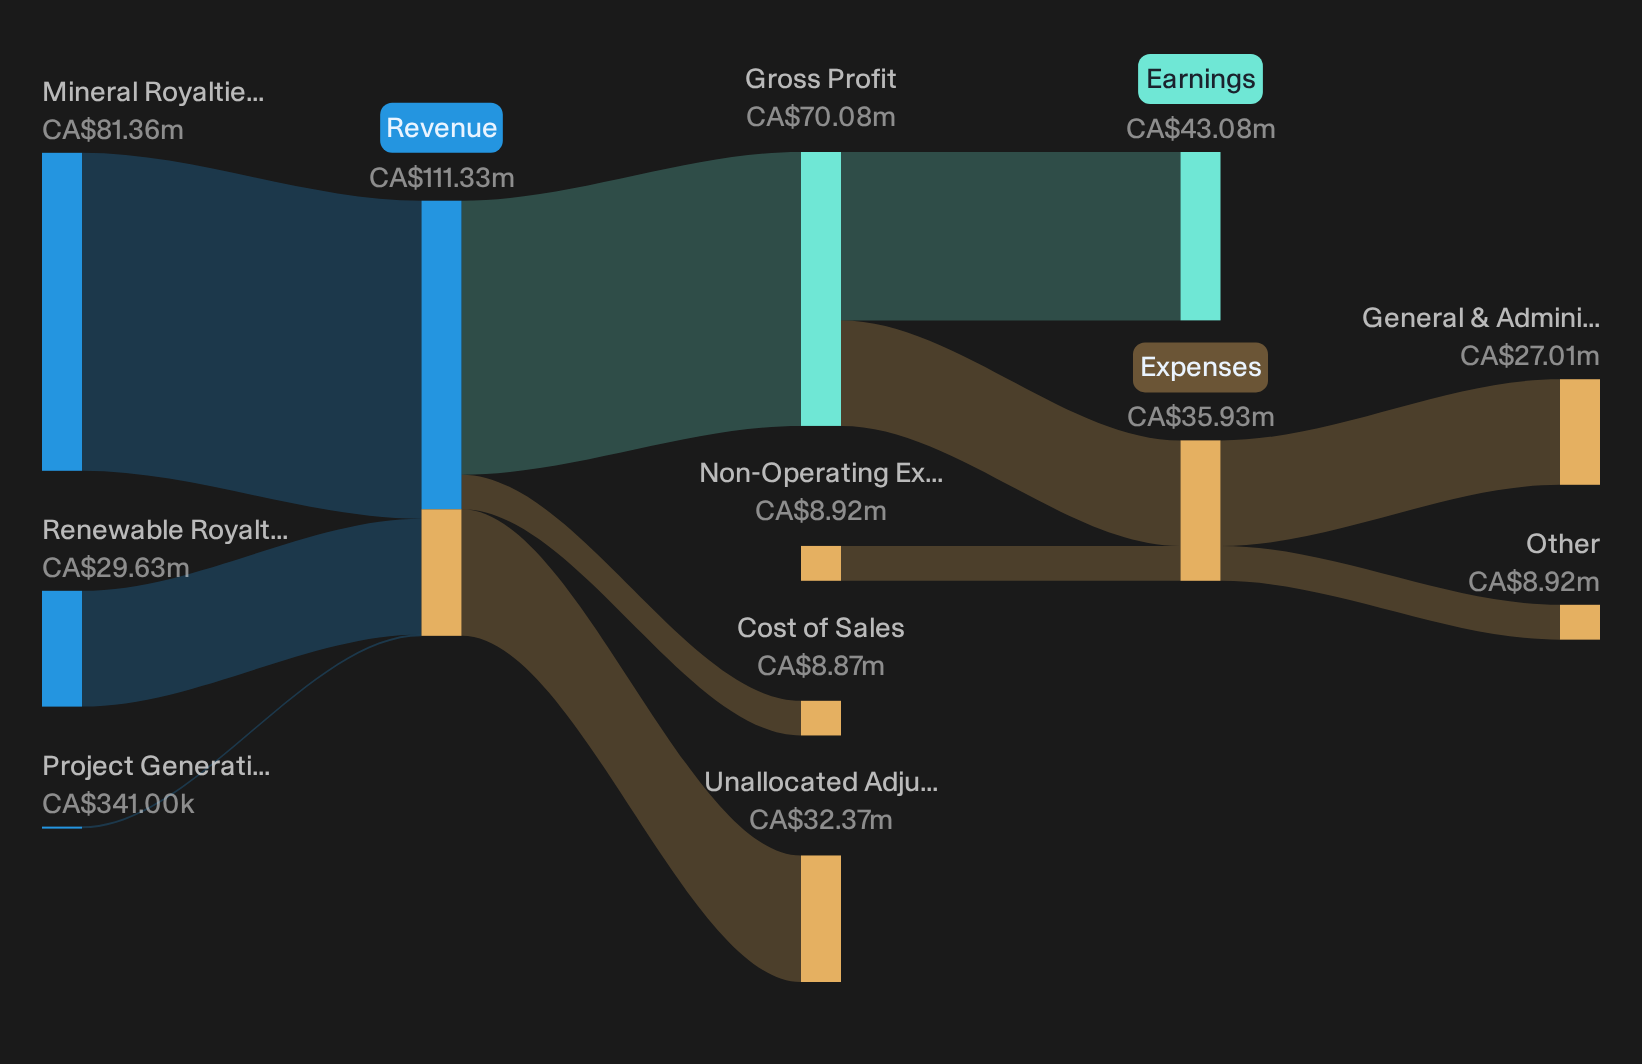
Operations: The business generated about CA$81 million from Mineral Royalties, CA$30 million from Renewable Royalties and a small amount from Project Generation, partly offset by joint venture adjustments.
Market Cap: CA$2.79 billion
Altius Minerals gives you lithium exposure through royalty checks rather than drill rigs. The bullish analyst Narrative on Simply Wall St focuses on that model as operators talk about expanding production and adding new projects under its umbrella.
"Growing global adoption of lithium ion batteries for EVs and grid storage, along with commentary that lithium battery shipments and energy storage shipments are increasing, points to a larger addressable market for Altius Minerals lithium royalty portfolio."
What really matters now is how one hard to forecast royalty stream source shapes the balance between high margins and future growth capacity.
That hard to forecast stream is only the start, and the full narrative for Altius Minerals maps how expanding royalty checks, capital allocation, and risk could be quietly decoupling for Altius Minerals.
Evolve Royalties (CNSX:EVR)
Overview: Evolve Royalties is a copper focused royalty and streaming company that holds interests in base and critical metal projects, including lithium linked assets.
Operations: Evolve Royalties generated about CA$3.7 million from acquiring and managing royalty and similar interests, mostly tied to Canadian projects.
Market Cap: CA$144 million
Evolve Royalties provides lithium exposure through royalty interests on brine and hard rock projects, in addition to broader base metal streams. The company has reported recent profitability and has discussed double digit revenue growth forecasts and a planned CA$14.2 million royalty portfolio acquisition focused on the lithium theme. However, a significant portion of the outlook is still dependent on how one future cash flow source performs relative to expectations.
That concentration risk is exactly why the 4 key rewards and 2 important warning signs (1 is major!) could be the key to understanding how Evolve Royalties handles its next leg of growth.

Seeking Alternatives Before Momentum Flies
Fresh ideas move first. By the time every headline catches up, early entry points are already dropping away. Scan these curated lists while it matters and get in early.
- Spot robust cash generators before the crowd by scanning the 7 high quality undervalued stocks that balance healthy balance sheets with solid cash flows while expectations still look caught on yesterday’s prices.
- Track the AI infrastructure backbone that keeps data demand flying using the 53 AI infrastructure stocks so you can filter for businesses supporting the chips, servers, and networks behind the boom.
- Zero in on power grid upgrades gaining momentum with the 43 power grid technology and infrastructure stocks and focus on companies positioned for rising investment in transmission, substations, and smart-grid technology under the radar for now.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com