


EN
Firefly Aerospace (FLY) Wins Fresh Contracts, Is It Still Below Fair Value?
Firefly Aerospace (FLY) has become a focus for investors after third quarter results, an updated revenue outlook for 2026, and a series of new multi year commercial and government contracts.
Firefly Aerospace has ridden a sharp swing in sentiment, with a 48.12% 30 day share price return and a 21.44% gain over the past week. However, the 90 day share price return is down 5.47%, while the 1 year total shareholder return is 9.85%. This suggests that short term momentum has picked up as investors react to new contracts and the higher 2026 revenue outlook, set against an already expectations-heavy valuation backdrop.
Scan Firefly Aerospace’s peers riding similar contract momentum and high expectations with our hand picked list of 20 high quality undiscovered gems.
Firefly Aerospace has just sprinted higher on fresh contracts and a richer 2026 outlook, which leaves a simple fork in the road. Do you lean into this surge now or wait for the valuation to cool?
Most Popular Narrative: 31% Undervalued
Firefly Aerospace is trading at $25.21 against an analyst consensus Narrative fair value of about $36.64, which points to a sizeable valuation gap that the analyst consensus Narrative on Simply Wall St ties directly to long run defense and lunar contract potential.
A growing focus on national security space and missile defense, including the planned US$175b Golden Dome program, positions Firefly’s Alpha, Elytra and SciTec software to compete across launch, space interceptors and fire control. This can influence long term revenue visibility and backlog conversion.
See why 48 investors see Firefly Aerospace as 31% undervalued.
Result: Fair Value of $36.64 (UNDERVALUED)
Still, Firefly Aerospace carries real execution risk, ranging from ongoing net losses of $133.4 million to launch reliability setbacks that could unsettle customers and delay contract revenue.
Find out about the key risks to this Firefly Aerospace narrative.
Another View: Firefly Aerospace Looks Expensive On Sales
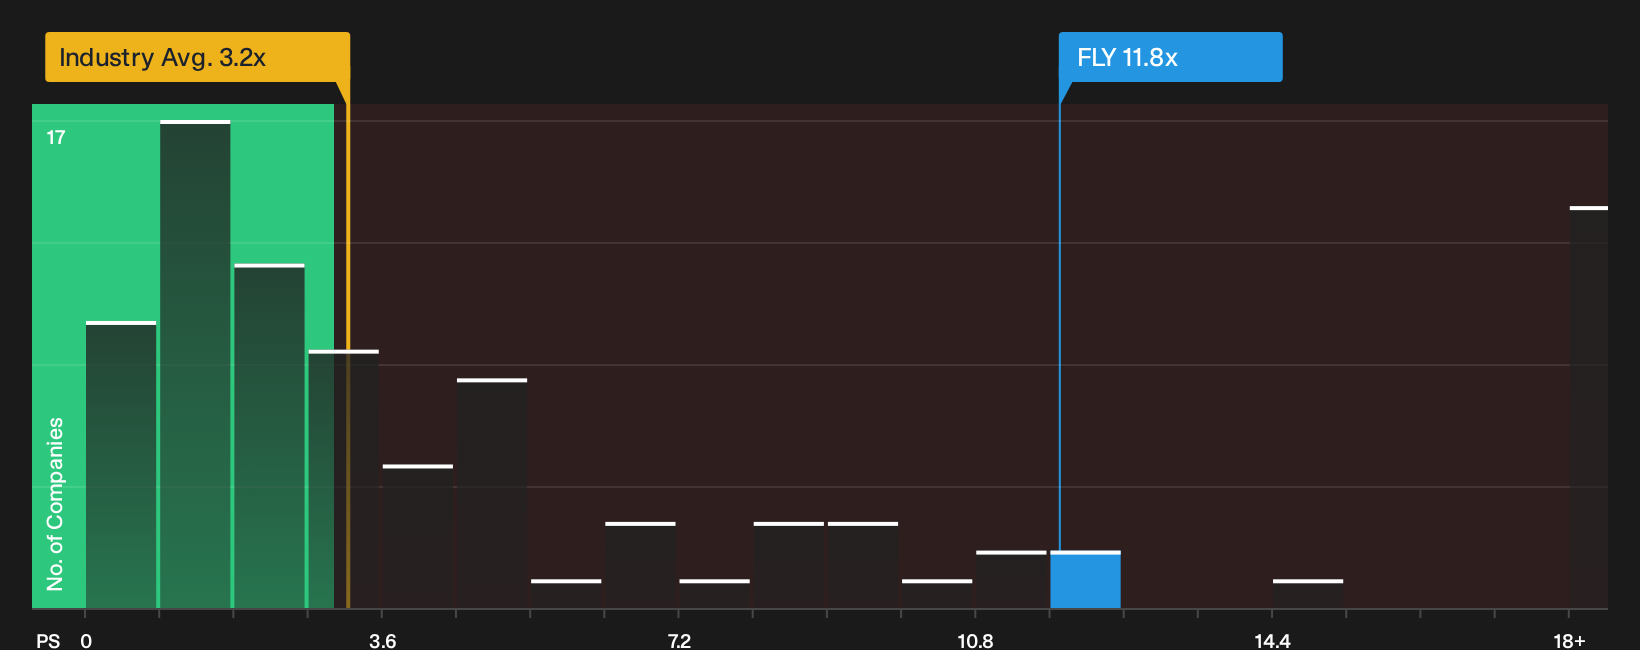
The fair value narrative and analyst target point to upside for Firefly Aerospace, yet the current P/S ratio of 11.8x tells a different story. That figure is more than double the fair ratio of 5.7x, and far above the US Aerospace & Defense average of 3.2x and peer average of 2.2x.
Paying roughly four to five times the peer and industry multiples concentrates a lot of expectation into each dollar of Firefly Aerospace revenue. If sentiment or growth assumptions change, how comfortable are you owning a stock that far above the sales multiples the market could move toward?
See what the numbers say about this price in our valuation breakdown with See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment on Firefly Aerospace is clearly split, and that kind of tension rarely lasts long once fresh data lands and expectations reset. Act sooner rather than later by weighing both sides of the story through 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Firefly Aerospace?
If you stop with Firefly Aerospace, you risk missing other opportunities that match your goals. Cast a wider net and let the data do the heavy lifting.
- Target potential bargains by reviewing companies with strong fundamentals and attractive valuations through the 32 high quality undervalued stocks.
- Prioritise resilience by scanning businesses that feature healthier finances using the list of solid balance sheet and fundamentals (24 results).
- Build a more defensive income stream by checking out companies paying higher yields via the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com