


EN
TORM (CPSE:TRMD A) Could Be 13% Undervalued As Q3 Earnings And Dividend Land
TORM (CPSE:TRMD A) is back in focus after reporting third quarter 2026 results along with an interim cash dividend of US$1.35 per share, tying earnings directly to shareholder payouts.
TORM’s Q3 announcement lands after a powerful stretch for the shares, with the latest price at DKK247.4 and a 1-day share price return of 1.81% and 7-day share price return of 6.45%, even though the 30-day share price return is down 7.55% from a recent high. Over a longer horizon, momentum has been strong, with a 90-day share price return of 27.86%, a year-to-date share price return of 97.60%, and a 1-year total shareholder return of 96.60% supported by dividends. The 5-year total shareholder return of roughly 9x highlights how the current earnings and dividend news fits into an already very strong multi-year run.
Scan other shipping and energy plays showing strong earnings and cash returns by running the curated 198 high quality undervalued stocks following TORM’s Q3 momentum and dividend news.
TORM now trades at a clear discount to analyst targets after a sharp run, which raises a simple question: Is the market rightly cautious about sustaining this earnings and dividend pace, or is the gap mispriced?
Most Popular Narrative: 13% Undervalued
TORM’s last close at DKK247.4 sits below the analyst consensus Narrative fair value of DKK285.40, implying a discount that the analyst consensus Narrative on Simply Wall St links to earnings power, margins and capital allocation.
TORM’s integrated platform, consistent TCE outperformance and ability to secure above market long term charters even for older vessels position the company to monetize strong market conditions more effectively than peers, improving net margins and cash generation.
See why 10 investors see TORM as 13% undervalued.
The Narrative applies a 6.09% discount rate to analysts’ assumptions for shrinking revenue and earnings over time, yet still arrives at DKK285.40 as a central estimate of worth. That fair value sits above both the current share price and the DKK269.31 level used in earlier research, so the implied upside has widened even as forecasts build in declining top line and profit.
Analysts in that Narrative expect revenue to contract by about 16.4% per year and earnings to fall from US$625.1m to US$353.2m by around October 2029, while profit margins ease only modestly from 35.5% to 34.4%. To reconcile those lower earnings with the price target of roughly DKK285.40, the valuation framework assumes the market is willing to pay a P/E of 16.9x on 2029 profits compared with 7.1x used today, a step up that would place TORM above the current 7.0x P/E level cited for the GB Oil and Gas industry.
For readers tracking this tanker stock, the key question is whether such a rerating from 7.1x to 16.9x on lower earnings is realistic given the sector’s cyclicality and the risks flagged in the same Narrative, including potential easing of trade route disruptions, a growing order book and changing energy consumption patterns. The fair value uplift to DKK285.40 reflects those moving parts, not a one way call, so it is worth stress testing your own expectations for freight rates, fleet supply and dividend policy against the Narrative’s inputs before treating the current 13% discount as a cushion.
Result: Fair Value of DKK285.40 (UNDERVALUED)
Still, this narrative can break if trade routes shorten as Red Sea disruptions ease, or if the incoming product tanker order book materially outpaces demand.
Find out about the key risks to this TORM narrative.
Another View: Cash Flows Point Lower For TORM
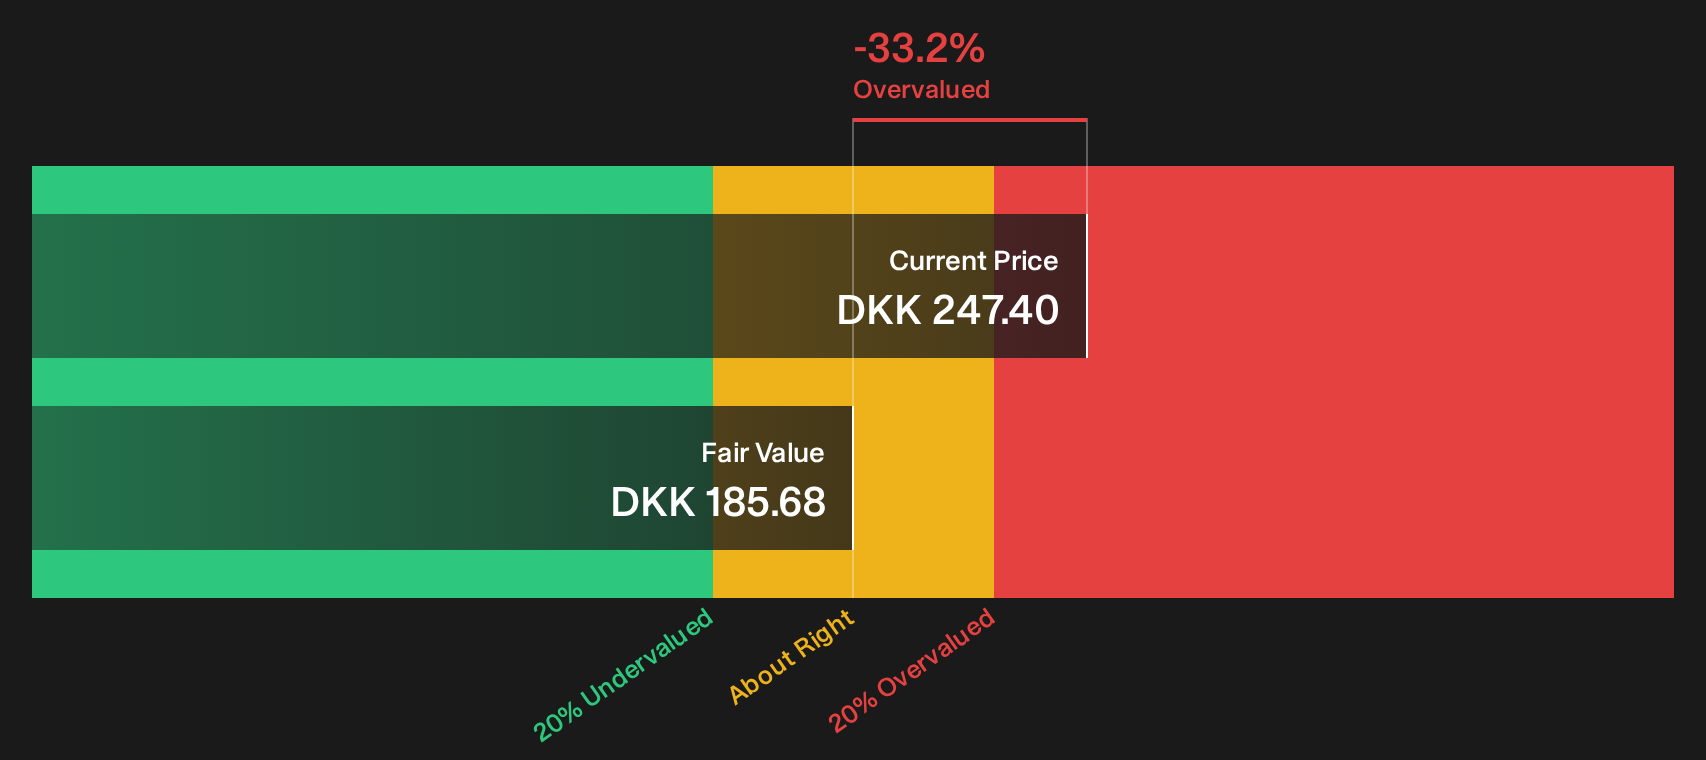
While the analyst Narrative for TORM leans on earnings and a future P/E of 16.9x to argue for a fair value of DKK285.40, the Simply Wall St DCF model paints a different picture. On that cash flow view, TORM at DKK247.4 screens as overvalued against an estimate of DKK185.68.
The spread between a DKK285.40 earnings based estimate and a DKK185.68 cash flow value is wide enough to matter. It effectively asks you to decide whether reported profits or long run cash generation deserve more weight in judging what TORM is worth.
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out TORM for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 198 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals in TORM’s valuation story make this a good moment to check the raw numbers yourself and decide how comfortable you feel with the current trade off between risks and upside. To get a concise snapshot of both sides of the argument, start with the 2 key rewards and 4 important warning signs.
Looking for more ideas beyond TORM?
If TORM’s mixed signals leave you wanting a broader watchlist, use this moment to widen your opportunity set before the next move passes you by.
- Target resilient cash generators by scanning a list of solid balance sheet and fundamentals (198 results) that can support operations through a wide range of conditions.
- Hunt for quality at attractive prices by reviewing a 198 high quality undervalued stocks that blend strong fundamentals with appealing valuations.
- Spot potential rising stars early by checking a 559 high quality undiscovered gems before they attract wider market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com