


EN
How Investors Are Reacting To Advanced Energy Industries Stock After An Earnings Beat
- Advanced Energy Industries reported third quarter 2026 sales of US$696.4 million and net income of US$115.6 million, alongside a US$0.10 per share quarterly dividend declared for payment on December 4, 2026 to shareholders of record on November 23, 2026.
- The business paired strong year over year gains in revenue and earnings with fourth quarter 2026 revenue guidance of US$735 million, plus or minus US$25 million. This reinforces that current demand strength is flowing through both the income statement and near term outlook.
- We will look at how Advanced Energy Industries' sharp year over year earnings jump reshapes the earlier investment narrative built around stress tested assumptions.
Advanced Energy Industries Investment Narrative Recap
To own Advanced Energy Industries, you need to believe its precision power business can keep supplying complex semiconductor tools and data center hardware at high reliability and attractive economics. According to John_Eric, an investor in the Simply Wall St Community, the key short term swing factor is whether current demand for semiconductor equipment and AI focused data center power holds up. The biggest operational risk is that customers ease ordering or stretch lead times, which would quickly show up in revenue and margins.
The latest earnings and guidance tighten that focus. Third quarter 2026 sales of US$696.4 million and net income of US$115.6 million indicate current demand is flowing through the income statement. Management’s fourth quarter 2026 revenue outlook of US$735 million, plus or minus US$25 million, keeps the near term story intact. It does not remove exposure to a softer semiconductor or data center spending cycle.
The most relevant recent announcement is the third quarter 2026 earnings release. Those figures confirm that the operating setup John_Eric described, with strong data center and semiconductor activity, is still visible in the reported numbers. Sales of US$696.4 million and basic EPS from continuing operations of US$2.90 give investors fresh reference points to test any earlier assumptions about Advanced Energy Industries.
That update also sharpens the catalyst and risk picture. The new fourth quarter 2026 revenue range of US$735 million, plus or minus US$25 million, concentrates attention on order flow and capacity execution over the next few months. Any sign that this guidance is hard to meet would challenge the recent momentum. In contrast, delivery against it would reduce uncertainty around the current earnings power, even though share price volatility remains a separate consideration.
In John_Eric’s narrative, the US$567.86 fair value for Advanced Energy Industries comes from a discounted cash flow framework that applies 34.2% annual revenue growth and a 10.8% future profit margin. It then checks that outcome against a required margin of safety before treating the figure as usable.
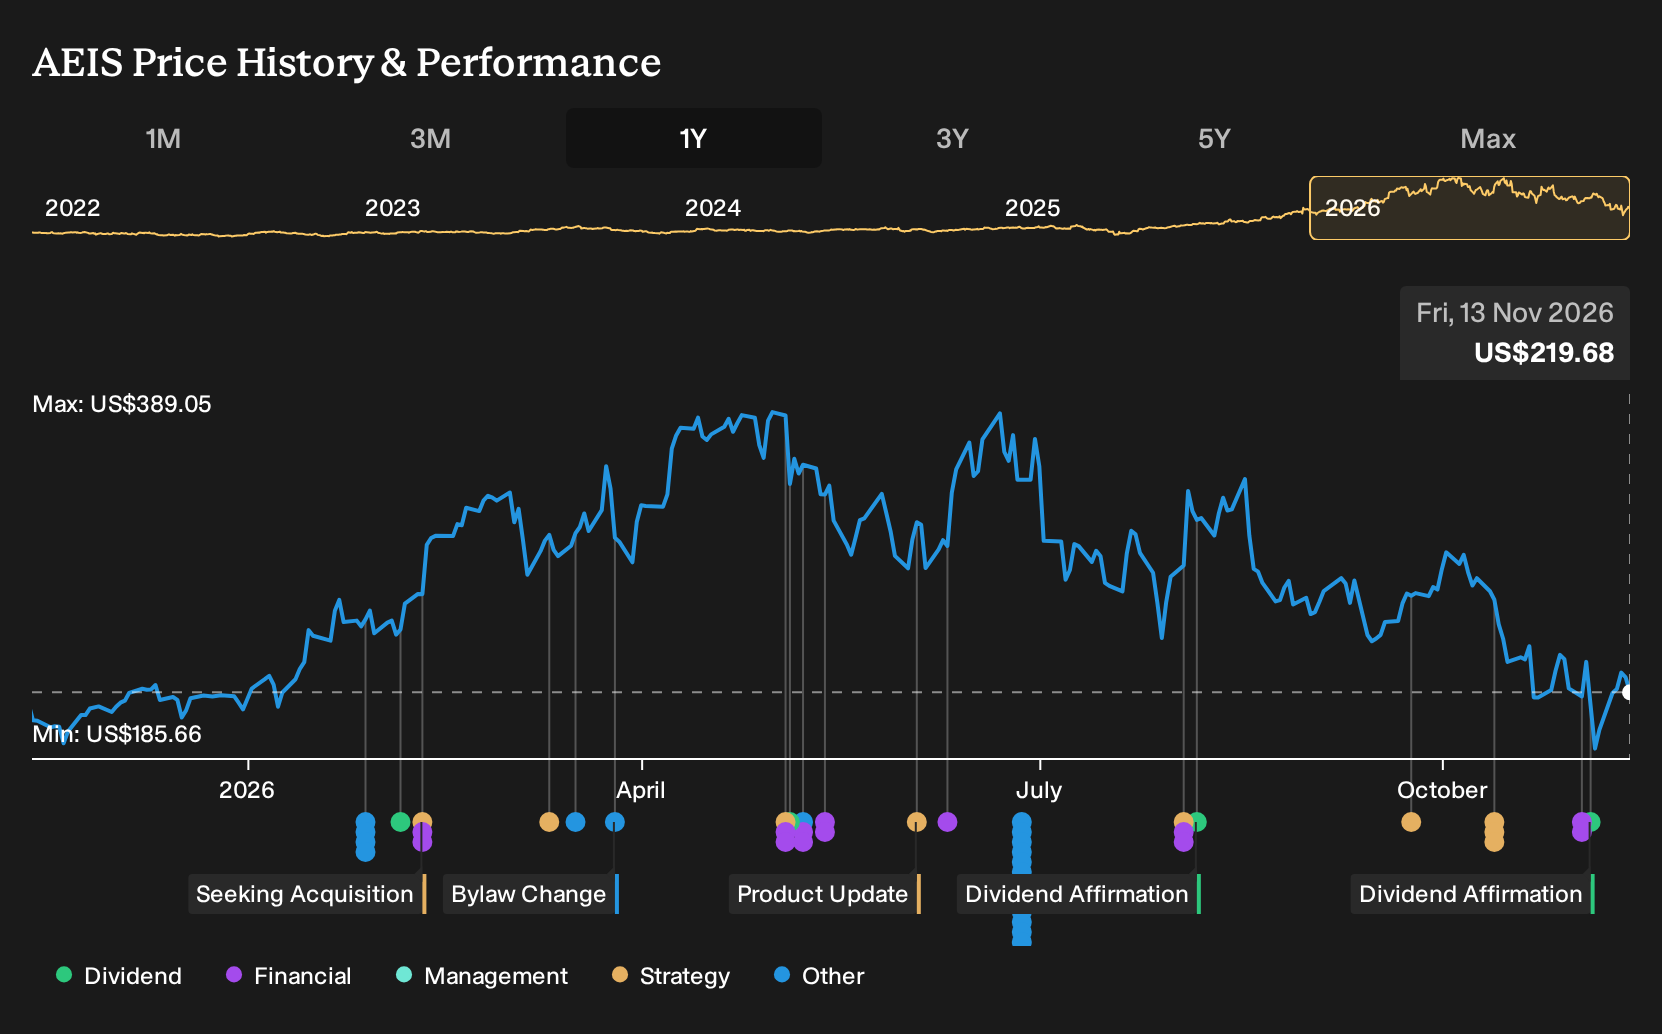
Discover how Advanced Energy Industries' fair value indicates a 158% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view treats capacity risk as the main story for Advanced Energy Industries. The most cautious analysts were penciling in about US$4.0b of revenue and US$923.0 million of earnings by 2029, yet still only saw a US$360 price target. That is a much more pessimistic framing. Use it as a reminder that sensible forecasts can differ a lot and that this fresh dividend and earnings news may shift those expectations over time.
Explore 5 other Advanced Energy Industries fair value estimates, including one that suggests it could be worth just $360.00!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis and judgment.
- A useful starting point for your Advanced Energy Industries research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Advanced Energy Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which helps you evaluate Advanced Energy Industries' overall financial health at a glance.
Looking for more investment ideas beyond Advanced Energy Industries?
Once you have a view on Advanced Energy Industries, it can help to line it up against a wider field of potential opportunities using the Simply Wall St Screener. That way you see how this stock compares with others that have different risk profiles, balance sheets, or income characteristics.
- If you want resilient businesses that aim to keep risk in check, start with a curated set of 31 resilient stocks with low risk scores and see how their profiles differ from Advanced Energy Industries.
- For investors who care most about steady financial footing and clean fundamentals, review a focused list of solid balance sheet and fundamentals (24 results) to benchmark balance strength against what you see at Advanced Energy Industries.
- When you are hunting for potential mispricing, compare your thesis here with a carefully filtered 20 high quality undiscovered gems that may not yet be widely followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com