


EN
Is Automatic Data Processing (ADP) Fully Priced After Its Dividend Increase?
Automatic Data Processing (ADP) drew fresh attention after its board approved a higher quarterly cash dividend, lifting the annual payout to US$7.60 per share and signaling management’s stance on shareholder returns.
At a share price of US$309.93, Automatic Data Processing has seen firm positive momentum, with a 30-day share price return of 10.56% and a year-to-date share price gain of 22.56%. The 1-year total shareholder return of 26.01% suggests income and price gains have both contributed to recent interest following the dividend increase.
Scan for other dividend focused opportunities with payout profiles similar to Automatic Data Processing by checking our 6 dividend fortresses in the same income oriented corner of the market.
For Automatic Data Processing, a higher dividend and a fast run-up in the share price can point to two very different stories. Is this mainly a stronger business being recognised, or is sentiment stretching the valuation?
Most Popular Narrative: 16% Overvalued
On the numbers from the Simply Wall St Community, the narrative fair value for Automatic Data Processing sits at $268, compared with the recent $309.93 close. This puts valuation firmly in the premium camp and makes the dividend uplift only part of the story according to DKDGI, an investor in the Simply Wall St Community who set out a detailed view.
Fair value USD 268: three-stage dividend discount model (current dividend USD 6.80, 8% growth for 10 years, fading to 3% over the next 10 years, 7.5% required return). Buybacks are not included, so the estimate is described as conservative.
See why 1 investors see Automatic Data Processing as 16% overvalued.
Result: Fair Value of $268 (OVERVALUED)
Still, Automatic Data Processing’s story could be tested if client retention weakens or if earnings outside client fund interest fail to keep up with its dividend ambitions.
Find out about the key risks to this Automatic Data Processing narrative.
Another View: Cash Flows Point The Other Way
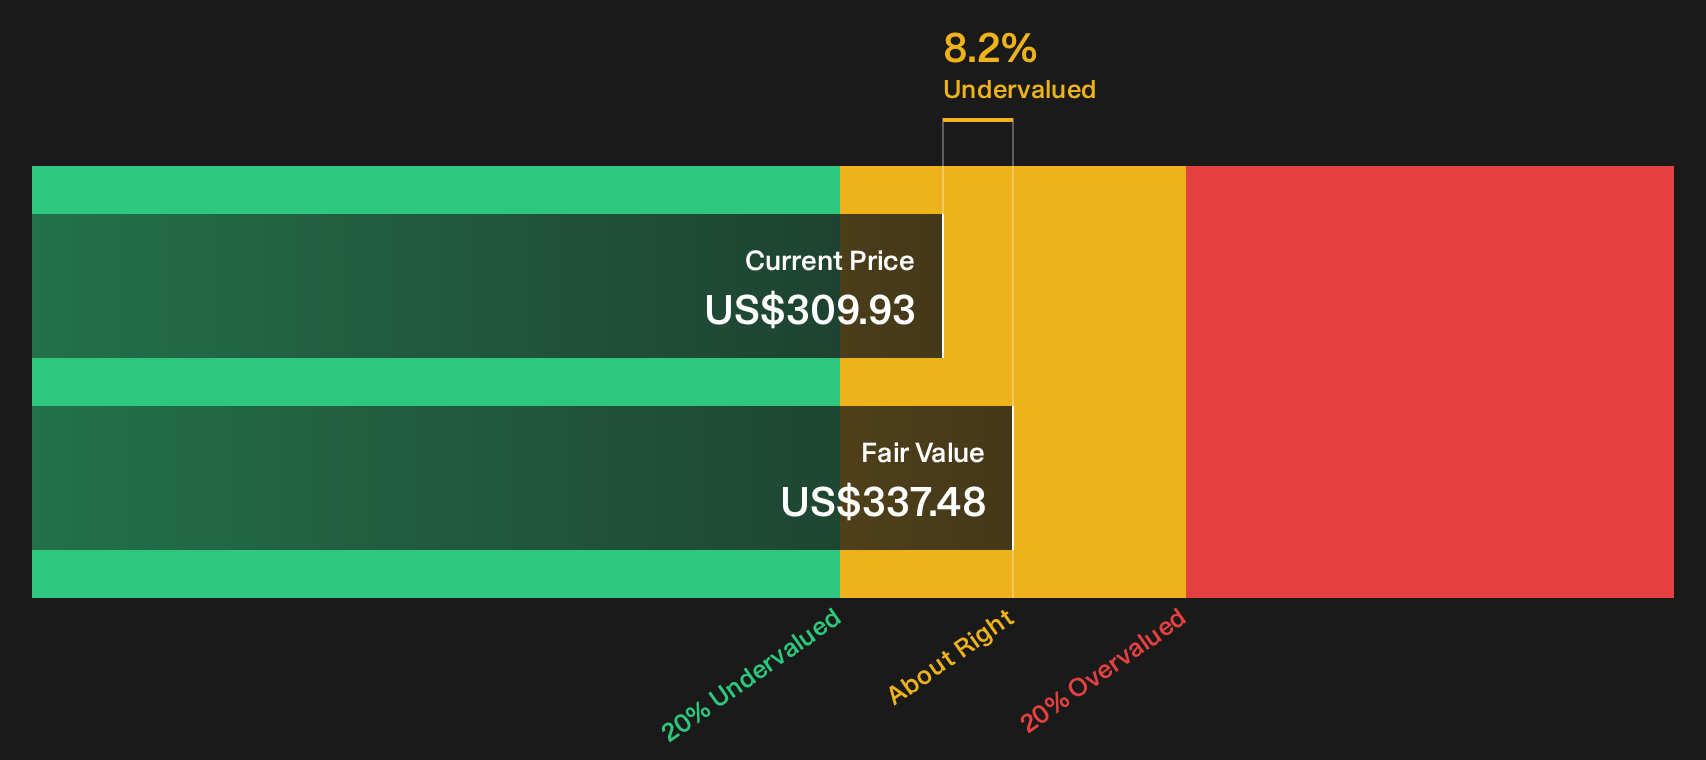
That community fair value of $268 for Automatic Data Processing leans on a dividend model, yet the SWS DCF model tells a different story. In that framework, ADP at $309.93 screens about 8.2% below an estimated future cash flow value of $337.48, which frames today’s price as a possible discount rather than a stretch. Which lens do you trust more when both are built on reasonable assumptions but point in opposite directions?
For readers who want to see the moving parts behind that cash flow view, check how the SWS DCF model treats ADP’s assumptions and sensitivity in more detail with Look into how the SWS DCF model arrives at its fair value..
Next Steps
Conflicted by a rich yield story and mixed valuation signals around Automatic Data Processing, or already leaning one way after the recent dividend move? Act while the data is fresh, review both the potential upside and flagged issues, then ground your own view in the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Automatic Data Processing?
If Automatic Data Processing sharpened your focus on income and valuation trade offs, broaden your watchlist now so you are not reacting after opportunities move.
- Target resilient balance sheets and steadier fundamentals by scanning our list of solid balance sheet and fundamentals (24 results) that filters for financially grounded companies built to handle tougher conditions.
- Hunt for potential value gaps by reviewing the 32 high quality undervalued stocks that highlights shares with strong quality markers priced below their implied worth.
- Stack your income ideas by comparing payouts in the 6 dividend fortresses and see which yields line up with the stability you want.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com