


EN
Ezaki Glico (TSE:2206) Could Be 46% Below Fair Value As Nine Month Earnings Land
Ezaki Glico (TSE:2206) has released its nine-month earnings to September 30, 2026, providing investors with updated figures that show sales of ¥281,008 million and net income of ¥7,719 million compared with the prior year period.
Ezaki Glico’s latest trading update comes after a mixed price pattern, with the 1-day share price return of 0.93% and 7-day gain of 1.77% partly offset by the share price being down 4.59% year to date. The 5-year total shareholder return of 50.92% points to momentum that has built over a longer horizon as investors react over time to periods of stronger and weaker perceived earnings power.
Compare Ezaki Glico’s latest earnings momentum with other food and consumer stocks by scanning our hand picked 19 high quality undervalued stocks that also pair cash generation with balance sheet strength.
Ezaki Glico’s share price has slipped this year even as nine month sales and earnings have moved higher. Is the latest uptick a reset toward business fundamentals or just sentiment swinging back after a weak spell, and what does that mean for valuation next?
Preferred P/E of 55.4x: Is it justified?
Ezaki Glico closed at ¥5,117, while the latest data shows the stock trading on a P/E of 55.4x that sits well above several key benchmarks. The premium valuation level contrasts with weaker recent share returns compared with the broader JP market and the JP Food sector over the past year.
The P/E ratio measures how much investors are paying today for each unit of current earnings. This is especially important for a consumer staples group like Ezaki Glico where growth is usually steadier rather than explosive. A P/E of 55.4x implies buyers are accepting a high price for each yen of profit, which suggests expectations for future earnings improvement are carrying more weight than the recent headline profit track record.
That premium is clear when you line it up against peers. Management is working with a P/E of 55.4x compared with a JP Food industry average of 16.1x and a peer group around 17x, which is a very wide gap. The estimated fair P/E of 30.4x is also far lower than the current multiple. This points to a level the market could move toward if sentiment cools or earnings delivery does not match the optimism implied today.
Explore the SWS fair ratio for Ezaki Glico.
Result: Price-to-Earnings of 55.4x (OVERVALUED)
Still, the share price decline of 4.6% year to date and the discount of around 33% to the ¥3,850 analyst target highlight that mood can flip fast.
Find out about the key risks to this Ezaki Glico narrative.
Another view on Ezaki Glico’s value
The rich 55.4x P/E paints Ezaki Glico as expensive, yet the SWS DCF model points in the opposite direction. On that framework, the shares trade around 46.1% below an estimated future cash flow value of ¥9,487.57, which frames current pricing as discounted rather than stretched.
For investors weighing which signal to trust, this clash between earnings based pricing and cash flow estimates raises a simple question: Is the story here driven more by near term profit pressure or by longer term cash generation potential, and which one matters more for your own timeframe?
Look into how the SWS DCF model arrives at its fair value.
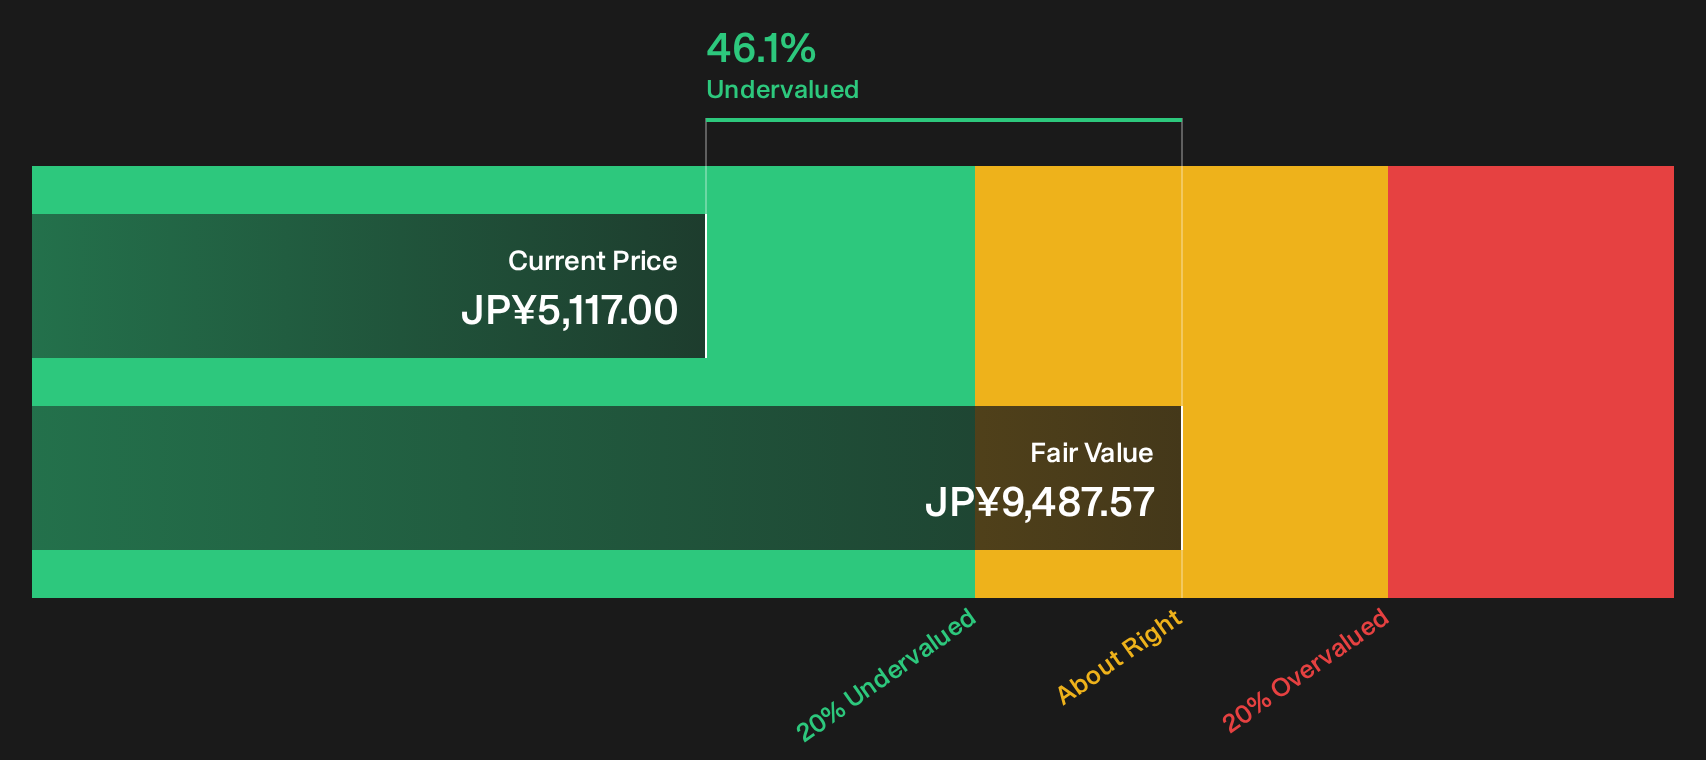
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Ezaki Glico for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 19 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Ezaki Glico’s price and fair value can feel confusing, so move quickly from headlines to hard numbers and shape your own stance. For a balanced view of both the upside and the red flags currently flagged by our model, start with the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Ezaki Glico?
If Ezaki Glico has caught your eye, do not stop here. The wider market holds plenty of other opportunities that could better match your goals.
- Target resilience by scanning a 20 resilient stocks with low risk scores that focuses on companies with financial profiles built to handle tougher conditions.
- Hunt for mispriced quality using a 72 high quality undiscovered gems that filters for strong fundamentals hiding outside the usual watchlists.
- Strengthen capital protection by reviewing a list of solid balance sheet and fundamentals (24 results) that highlights businesses with healthier debt levels and robust assets.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com