


EN
Why Cloetta (OM:CLA B) Is Getting Attention Today
Cloetta (OM:CLA B) reported third quarter 2026 earnings, with sales of SEK 2,233 million and net income of SEK 246 million, alongside higher earnings per share from continuing operations versus the prior year period.
Recent trading suggests investors are warming to Cloetta, with a 1 month share price return of 17.98% and a year to date share price gain of 56.02%. The 1 year total shareholder return of 89.16% points to strong momentum building around the stock.
Scan how Cloetta’s earnings-led momentum compares with other consumer-focused stocks showing strong fundamentals using the curated 198 high quality undervalued stocks list.
Bulls see Cloetta’s profit uptick and powerful 1 year return as evidence the rerating still has room to run, while bears call it overheated. Which story do the current valuation markers support?
Most Popular Narrative: 3% Undervalued
Cloetta’s last close at SEK63 sits below the SEK65 fair value outlined in the analyst consensus Narrative on Simply Wall St. This assessment leans on detailed revenue and earnings forecasts as well as an explicit discount rate of 5.45%.
The company is expanding beyond core geographies into the U.K., Germany and North America, including the CandyKing concept store and local organization in the U.S. If scaled prudently, this could widen the revenue base while fixed cost absorption supports earnings.
See why 4 investors see Cloetta as 3% undervalued.
Result: Fair Value of SEK65 (UNDERVALUED)
Still, the Cloetta story can break if expansion into markets like the U.S. and Germany increases costs without generating scale, or if seasonal and new candy concepts lose consumer appeal.
Find out about the key risks to this Cloetta narrative.
Another View: Cloetta Through The P/E Lens
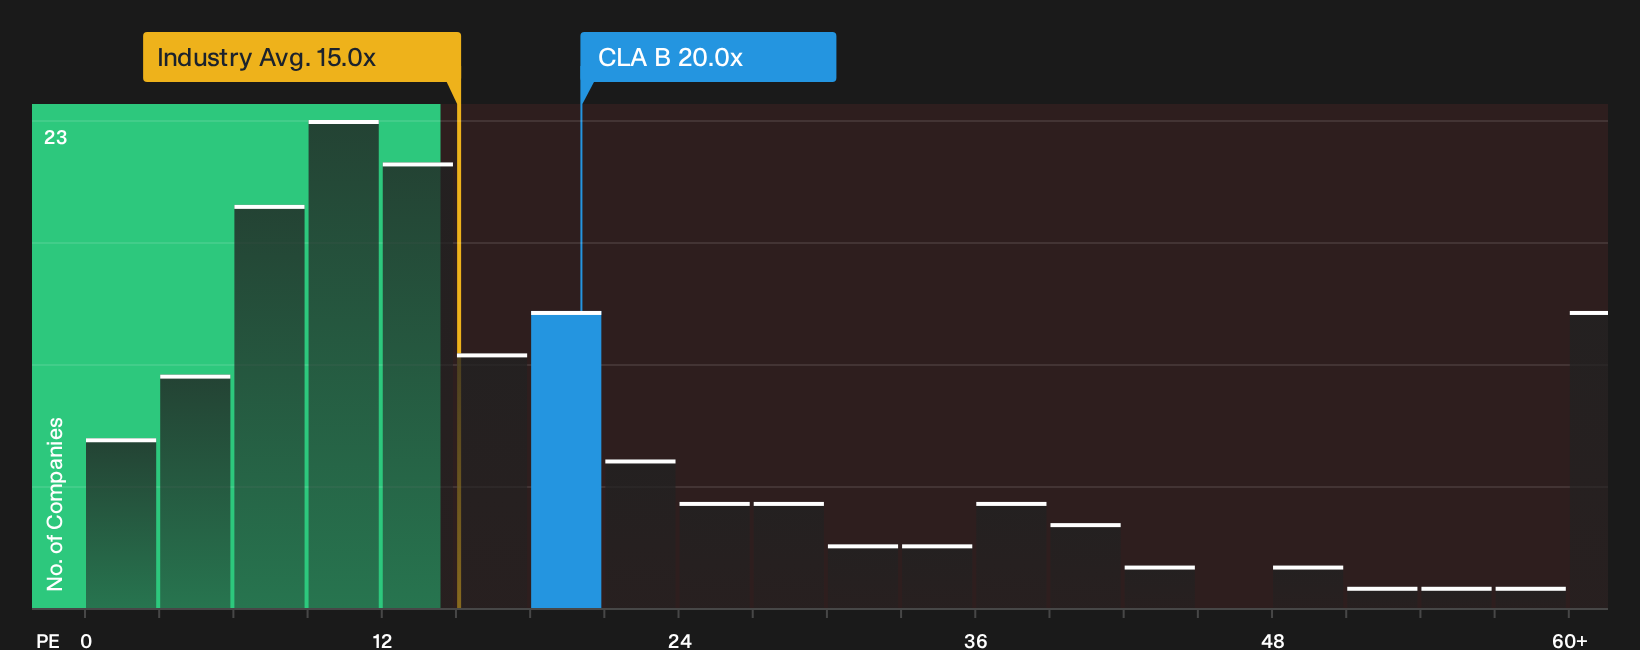
The cash flow fair value narrative paints Cloetta as 20.1% below intrinsic value, yet the earnings multiple tells a different story. At roughly 20x P/E, the stock trades well above the European Food industry on 14.5x and a peer average of 16.4x, and even above its own 15.3x fair ratio. Is the market simply paying up for quality, or stretching the risk side of the equation?
Investors weighing this richer earnings tag against the cash flow upside can use the detailed multiple breakdown as a cross check before acting on either signal, through the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If this mix of enthusiasm and caution around Cloetta feels familiar, treat it as your cue to stress test the story yourself using the 3 key rewards and 1 important warning sign.
Ready for more ideas beyond Cloetta?
Do not stop with a single story. Broaden your watchlist with fresh candidates filtered by quality, income, and resilience so you always have options ready.
- Target dependable income streams by reviewing a shortlist of companies offering robust payout potential through the 220 dividend fortresses.
- Hunt for quality at a reasonable price by scanning companies that appear mispriced on fundamentals using the 198 high quality undervalued stocks.
- Prioritize capital protection by focusing on businesses screened for stability and low risk profiles in the 210 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com