


EN
Dillard's (DDS) Following Earnings Beat Is The Stock Starting To Look Fully Valued
Dillard's (DDS) just posted third quarter results that topped earnings expectations, supported by a 1% lift in comparable store sales, higher year over year revenue and net income, and a gain from a payment card settlement.
The earnings surprise and settlement gain have come alongside a mixed share price pattern for Dillard's, with the stock up 3.97% on the day of the release and showing an 11.01% 90 day share price return, yet down 7.10% over 30 days. That near term pullback contrasts with a modest 2.49% total shareholder return over the past year and a very large 3 year total shareholder return of 115.38%, suggesting that longer term holders have still seen substantial value creation even as shorter term momentum has cooled.
Scan how Dillard's compares to other retailers by reviewing our hand-picked group of 32 high quality undervalued stocks that pair balance sheet strength with solid cash generation.
Dillard's is now trading above the average analyst price target after a strong multi year run, but it also just surprised on earnings and comps. Is most of the easy upside already in the rearview, or do the numbers still point to room ahead?
Preferred P/E of 13.7x: Is it justified?
Dillard's trades on a P/E of 13.7x while the last close sits at $622.64, so the question is whether that earnings multiple reflects the quality and durability of its cash generation or stretches what those profits can reasonably support.
The P/E ratio compares the share price to earnings per share and gives you a quick yardstick for what the market is willing to pay for each dollar of profit. For a department store chain like Dillard's, which operates in a cyclical and highly competitive retail space, that lens often captures how investors weigh near term earnings forecasts against past profitability and capital returns.
Here the signals point in different directions. On one side, the stock trades below the North American Multiline Retail industry average P/E of 22.2x, which suggests the market is paying a lower headline multiple than the sector. On the other side, this 13.7x ratio is slightly higher than the peer average of 13.4x and above an estimated fair P/E of 10.9x. This implies the current pricing could be richer than what a regression based view might support and that the multiple has room to compress toward that fair level if sentiment cools.
Explore the SWS fair ratio for Dillard's.
Result: Price-to-earnings of 13.7x (OVERVALUED)
Still, the story around Dillard's can change quickly if annual net income growth continues to decline by 12.1% or if revenue growth stalls near 0.8%.
Find out about the key risks to this Dillard's narrative.
Another view on Dillard's value
The P/E discussion presents Dillard's as slightly stretched relative to a fair ratio of 10.9x. In contrast, the SWS DCF model suggests a different perspective. From that viewpoint, the shares at $598.89 were about 4.2% below an estimated future cash flow value of $625.17, which indicates a modest undervaluation. Which signal should be treated as the anchor when they disagree?
Look into how the SWS DCF model arrives at its fair value.
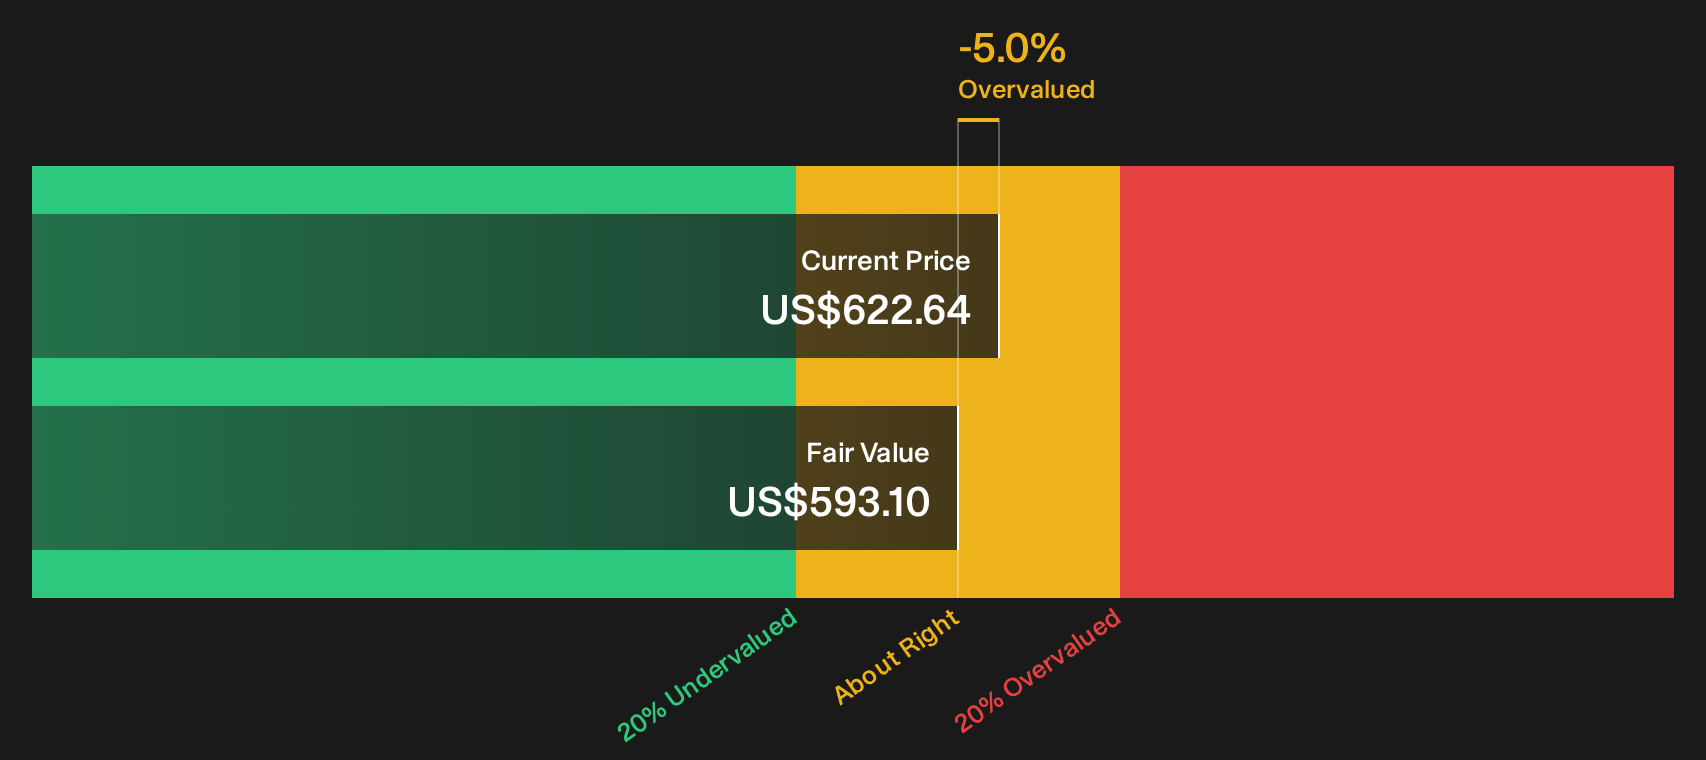
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Dillard's for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Dillard's value and risk profile can feel messy, which is exactly why checking the underlying metrics yourself matters. If you want a clear picture of what could go right and what might go wrong from here, start by weighing the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Dillard's?
If Dillard's has sharpened your eye for value and risk, do not stop here. Broader research now can shape much better decisions later.
- Target resilient balance sheets and steady fundamentals by scanning our list of solid balance sheet and fundamentals (24 results), which filters for financial strength first.
- Hunt for mispriced quality by reviewing the 32 high quality undervalued stocks, which surfaces businesses combining robust cash flows with disciplined capital structures.
- Spot potential future leaders early by checking the 20 high quality undiscovered gems, which highlights under-the-radar stocks with strong underlying metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com