


EN
What SBM Offshore (ENXTAM:SBMO)'s Raised Guidance Means For Shareholders
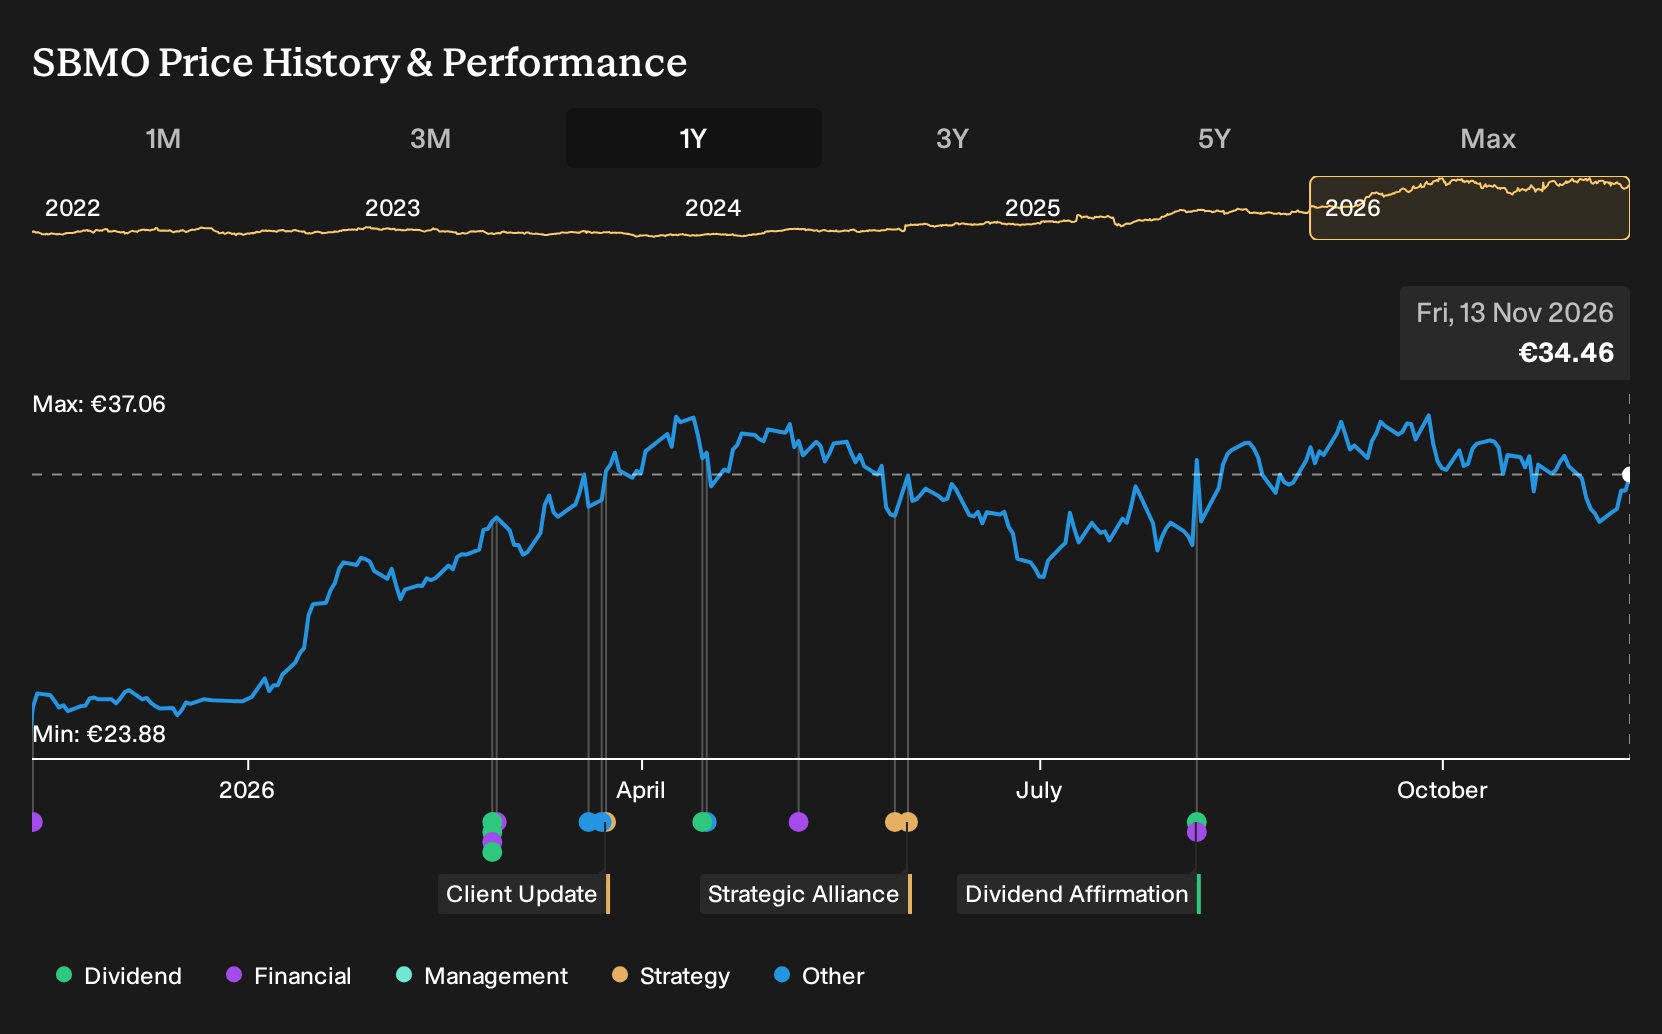
- SBM Offshore reported a 77% rise in year to date 2026 Directional revenue, raised full year revenue and EBITDA guidance, announced an interim cash dividend, and continued a US$270m share repurchase that is about 72% complete, supported by around 99% fleet uptime and steady progress on Longtail FPSO and SEAP I and II.
- The combination of higher Directional revenue guidance, substantial contracted project execution and active cash returns indicates that SBM Offshore is leaning on visible cash flow rather than short term headline earnings to frame its capital allocation.
- We will now see how SBM Offshore's investment narrative is affected by the stronger Directional revenue outlook flagged in the latest update.
Scan other offshore energy plays with similar cash generation profiles by reviewing the hand picked list of solid balance sheet and fundamentals (198 results), which may handle capital returns in a comparable way to SBM Offshore.
SBM Offshore Investment Narrative Recap
To own SBM Offshore, you need to believe the contracted backlog and cash generation from FPSOs outweigh the complexity of reported earnings. Ivoed, an investor in the Simply Wall St Community who wrote the original narrative, argues that the real story sits in long dated cash flows and balance sheet de risking. The latest jump in Directional revenue and higher guidance support that view, with the main short term catalyst now being clean execution on Longtail and SEAP I and II.
The biggest operational risk remains heavy project debt and construction exposure, especially with earnings and revenue forecast to decline over the next three years. Strong fleet uptime around 99% helps, but any schedule slippage, cost pressure or weaker offshore award flow could still hit sentiment faster than the growing backlog can offset.
The interim cash dividend announced alongside the Q3 update looks most relevant to this catalyst and risk mix. Management is choosing to return money while still heavily invested in Turnkey and lease projects. This puts a spotlight on how quickly Directional net debt can be reduced from here and how smooth cash conversion is from the enlarged backlog.
That payout also intersects with two flagged weaknesses. The dividend track record has been described as unstable and the group still carries a high level of debt. For you as a shareholder, the question is whether rising Directional revenue and Operational EBITDA, together with the share buyback and dividend, can comfortably coexist without squeezing financial flexibility if offshore conditions or project execution worsen.
Ivoed’s narrative reaches a fair value of €44.50 for SBM Offshore by combining 15.4% yearly revenue growth with a future 15.6% profit margin. It then applies those cash flows to a backlog-based framework that weights long-dated earnings power more heavily than short-term reported profit complexity.
Uncover why SBM Offshore's fair value indicates a 29% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some bullish analysts focus less on working capital swings and more on SBM Offshore’s capacity to keep winning complex Sale and Operate FPSOs. Before this Q3 call they were modeling revenue of about US$7.4b and earnings of US$847.5m by 2029, which supports a higher P/E and a more optimistic story than the baseline. These views were all formed before the latest trading statement, so treat them as moving pieces and compare several angles before deciding how you see the company.
Explore 4 other SBM Offshore fair value estimates, including one that suggests as much as 59% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your SBM Offshore research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for SBM Offshore. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate SBM Offshore's overall financial health at a glance.
Looking for more investment ideas beyond SBM Offshore?
Once you have a view on SBM Offshore, it can help to compare it with other businesses that share similar quality or risk traits, so you can judge whether the opportunity really stacks up against the rest of your watchlist.
- If you want potential upside with a focus on resilience, scan for companies that pair stronger fundamentals with appealing valuations by reviewing the 198 high quality undervalued stocks.
- For income focused investing, look at businesses that combine higher yields with balance sheet strength through the 220 dividend fortresses.
- When capital preservation matters most, narrow your watchlist to companies that score well on financial robustness and risk metrics using the 210 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com