


EN
Learn Why The Bull Case For Omeros (OMER) Could Change Following EU Drug Setback
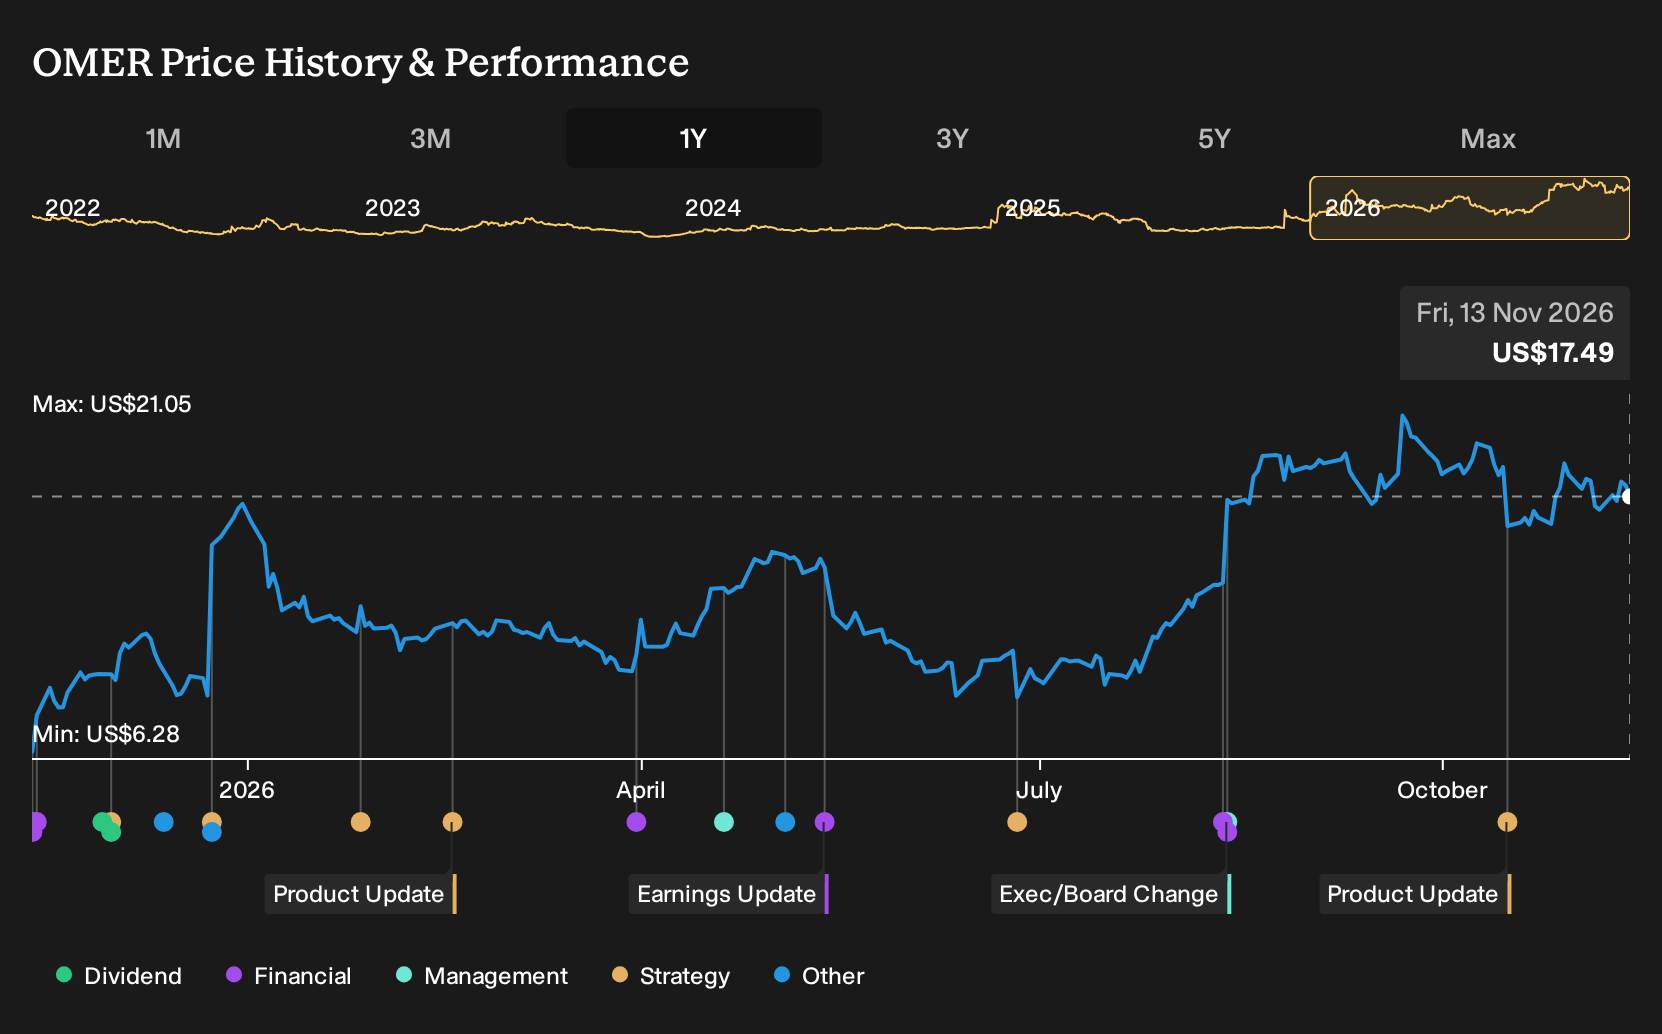
- Omeros received negative opinions from the European Medicines Agency's CHMP on narsoplimab for TA TMA, which were followed by a securities law investigation focused on whether management misrepresented business risks tied to this asset.
- The scrutiny around narsoplimab challenges a key pillar of Omeros's complement franchise and raises questions about future cash generation from one of its lead programs, even as some metrics suggest the shares may not fully reflect remaining pipeline potential.
- This article examines how Omeros's investment narrative around complement assets is being tested by the EMA's negative narsoplimab opinion and the subsequent investigation.
Scan beyond Omeros and this investigation driven volatility to compare it with a curated 32 high quality undervalued stocks list that the market may be pricing cautiously despite solid fundamentals.
Omeros Investment Narrative Recap
To own Omeros, you need to believe the complement franchise can translate into real-world usage despite setbacks around narsoplimab and YARTEMLEA. The analyst consensus narrative on Simply Wall St highlights forecast growth in revenue and earnings, while the recent EMA opinion and related investigation place more emphasis on execution quality and near-term regulatory clarity.
The most important short-term catalyst is regulatory and commercial progress for YARTEMLEA in TA TMA, together with the expected closing of the Novo Nordisk deal. The biggest current threat is liquidity pressure if those cash inflows are delayed or impaired, particularly given past quarterly losses and negative shareholders’ equity that already limit financial flexibility.
The Novo Nordisk agreement around Zaltenibart is the key recent development most directly connected to this situation. It is structured to bring US$240 million upfront and up to US$2.1 billion in potential milestones and royalties. These amounts, if received as planned, would help address debt obligations and extend the funding runway at a time when narsoplimab is under scrutiny.
That transaction also narrows some antibody and alternative pathway options for Omeros. As a result, execution in the remaining MASP 2 and MASP 3 small molecule programs, alongside YARTEMLEA, becomes more important. For a shareholder, the practical question is whether this reshaped portfolio and the anticipated cash inflow can offset regulatory risk on narsoplimab and align with the earnings growth that analysts are still modeling.
Omeros' current narrative points to forecast revenues of $375.5 million and projected earnings of $165.9 million by 2029. This implies revenue growth of 113.8% per year and an earnings increase of about $49.4 million from $116.5 million today.
Uncover why Omeros' fair value indicates a 57% potential upside to its current price before that gap starts to close.
Exploring Other Perspectives
One alternate Omeros storyline focuses on earnings rather than cash runway. The most cautious analysts were only modeling about $292.5 million of revenue and $71.9 million of earnings by 2029 before this EMA driven investigation emerged. That is far below the consensus figures and shows how sharply opinions can diverge. You are seeing competing stories in real time, so it can help to explore several viewpoints before deciding how this new information might reshape your own perspective.
Explore another Omeros fair value estimate, including one that suggests it could be worth just $27.50!
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Omeros research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Omeros. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Omeros' overall financial health at a glance.
Looking for more Omeros style investment ideas?
If the Omeros story has you thinking about position sizing, risk and upside across your portfolio, it can help to line it up against a wider set of listed businesses with clear financial profiles and different return drivers.
- If capital protection comes first for you, scan a 31 resilient stocks with low risk scores that score well on resilient balance sheets and lower overall risk indicators.
- If balance sheet strength is your priority, compare Omeros with a list of solid balance sheet and fundamentals (24 results) to see which companies pair financial stability with consistent fundamentals.
- If you prefer overlooked opportunities, broaden your watchlist with a 20 high quality undiscovered gems that have solid underpinnings yet still fly under most investors' radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com