


EN
Is Omnicom Group (OMC) Undervalued After Its Omnicom Health CEO Appointment?
Omnicom Group (OMC) has put fresh leadership at the center of its healthcare push by appointing Tom Schwenger as CEO of Omnicom Health's marketing business, a move that refocuses attention on the stock.
Recent trading in Omnicom Group reflects a pick up in momentum, with a 1-month share price return of 12.21% and a year to date share price gain of 8.19%, while the 1-year total shareholder return of 26.86% points to stronger longer term gains that pre date Schwenger’s appointment. The smoother 3-year and 5-year total shareholder returns of 23.72% and 56.71% suggest investors have been rewarded over time. The latest leadership shift in healthcare marketing now feeds into an already constructive shift in sentiment around the stock.
Capitalize on Omnicom Group’s healthcare and data momentum by weighing it against a curated set of resilient communicators and marketers in our 31 resilient stocks with low risk scores.Bulls see Omnicom Group’s healthcare and data push and Schwenger’s appointment as underappreciated strengths, while bears focus on cyclicality and agency saturation. Where do the current valuation markers appear to lean next?
Most Popular Narrative: 14% Undervalued
On the numbers, the analyst consensus Narrative on Simply Wall St marks Omnicom Group’s fair value at $102, compared with the latest close at $87.98. This uses an 11.0% discount rate that already bakes in a higher required return for risk.
The current numbers for growth, margin expansion, earnings guidance and share repurchases imply a share price that treats Omnicom Group as still facing material integration, interest cost and regional risk, even as this narrative views the stock as undervalued and bullish.
The expanded cost reduction and portfolio pruning program, which now targets disposals of about US$3.5b to US$3.6b of largely lower growth revenue and gross cost synergies of US$1.5b by mid 2028, is designed to support higher Core Operations margins and EBITA growth as remaining businesses scale.
See why 48 investors see Omnicom Group as 14% undervalued.
Result: Fair Value of $102 (UNDERVALUED)
Still, the narrative can crack if higher borrowing costs eat into profit or if weaker regions like Asia Pacific and the Middle East fail to stabilise.
Find out about the key risks to this Omnicom Group narrative.
Another View: Omnicom Group Through Market Multiples
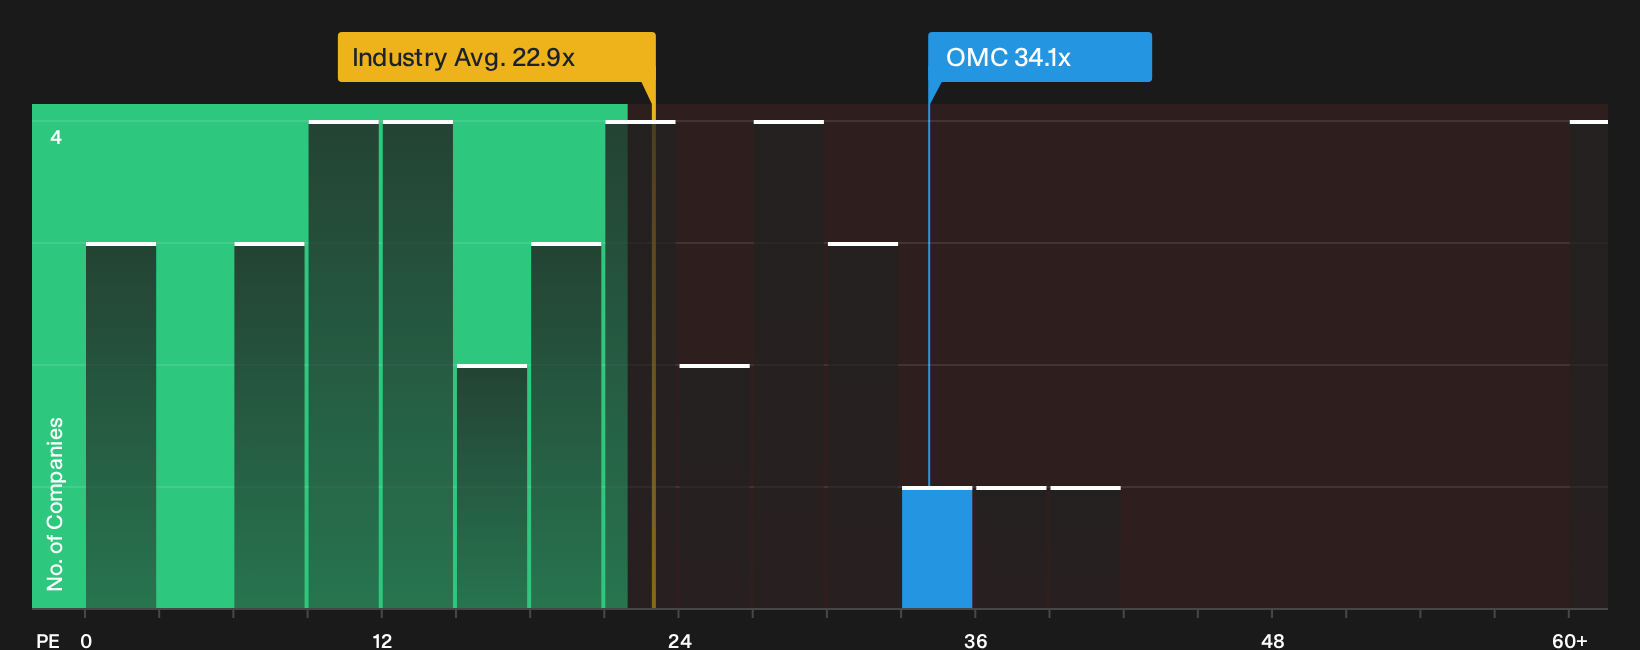
There is a different message once you look at Omnicom Group through its P/E ratio. The stock trades on 34.1x earnings, which is higher than the US Media industry at 22.2x and above a fair ratio of 26.3x. That gap points to less room for error. Are investors being paid enough for that premium?
See what the numbers say about this price in our valuation breakdown, starting with the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on Omnicom Group so far. If you want your view to move faster than the next headline, consider both the upside and downside in the 2 key rewards and 5 important warning signs.
Looking for more investment ideas beyond Omnicom Group?
Omnicom Group might be front of mind today, but your portfolio can benefit when you keep new ideas coming from different parts of the market.
- Explore potential value by scanning companies that pair quality fundamentals with possible mispricing through the 32 high quality undervalued stocks.
- Review a curated list of higher-yielding payers to support your income goals using the 6 dividend fortresses.
- Filter for businesses with robust finances and stronger balance sheets to focus on durability in the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com