


EN
Is SEGRO (LSE:SGRO) Fairly Valued As Institutions Build New Positions?
Fresh interest in SEGRO (LSE:SGRO) has been stirred by disclosures showing Millennium International Management LP and Natixis SA building positions through relevant securities tied to the UK logistics landlord.
The recent disclosures arrive after a strong run for SEGRO, with the share price up 28.96% year to date to £9.19, even though the 90 day share price return is down 4.35% and the 5 year total shareholder return has declined 21.98%. This suggests momentum has cooled in the short term compared with the longer record of mixed gains and setbacks.
Scan how SEGRO compares with other real estate and infrastructure landlords attracting fresh institutional interest by reviewing the hand picked list of solid balance sheet and fundamentals (9 results) in the same space.
The share price near £9.19 now sits only modestly below analyst targets, while one intrinsic estimate points much higher. So where does fair value for SEGRO really land on that spread?
Most Popular Narrative: 2% Undervalued
SEGRO closed at £9.19, while the most watched narrative on the stock pins fair value slightly higher at £9.39, leaving only a small valuation gap for investors to interpret.
According to Composite_Research, an investor in the Simply Wall St Community who authored the narrative, SEGRO is in the middle of a shift that hinges less on warehouses and more on energy rich digital infrastructure, and they frame that as a key driver of value.
The company has the potential to develop 24 data center sites with a total capacity of 1.2 GW in the long term. The commissioning of this full capacity would multiply SEGRO''s rental revenues from its current level (~£700 million annually), with an additional £200-300 million coming from data centers alone. Its current dominance in Slough and new projects make SEGRO one of Europe''s largest data center landlords.
See why 14 investors see SEGRO as 2% undervalued.
Result: Fair Value of £9.39 (UNDERVALUED)
Still, the SEGRO narrative could be knocked off course if data center build outs run into grid, planning or cost hurdles, or if refinancing conditions tighten materially.
Find out about the key risks to this SEGRO narrative.
Another View: SEGRO Looks Expensive On Earnings
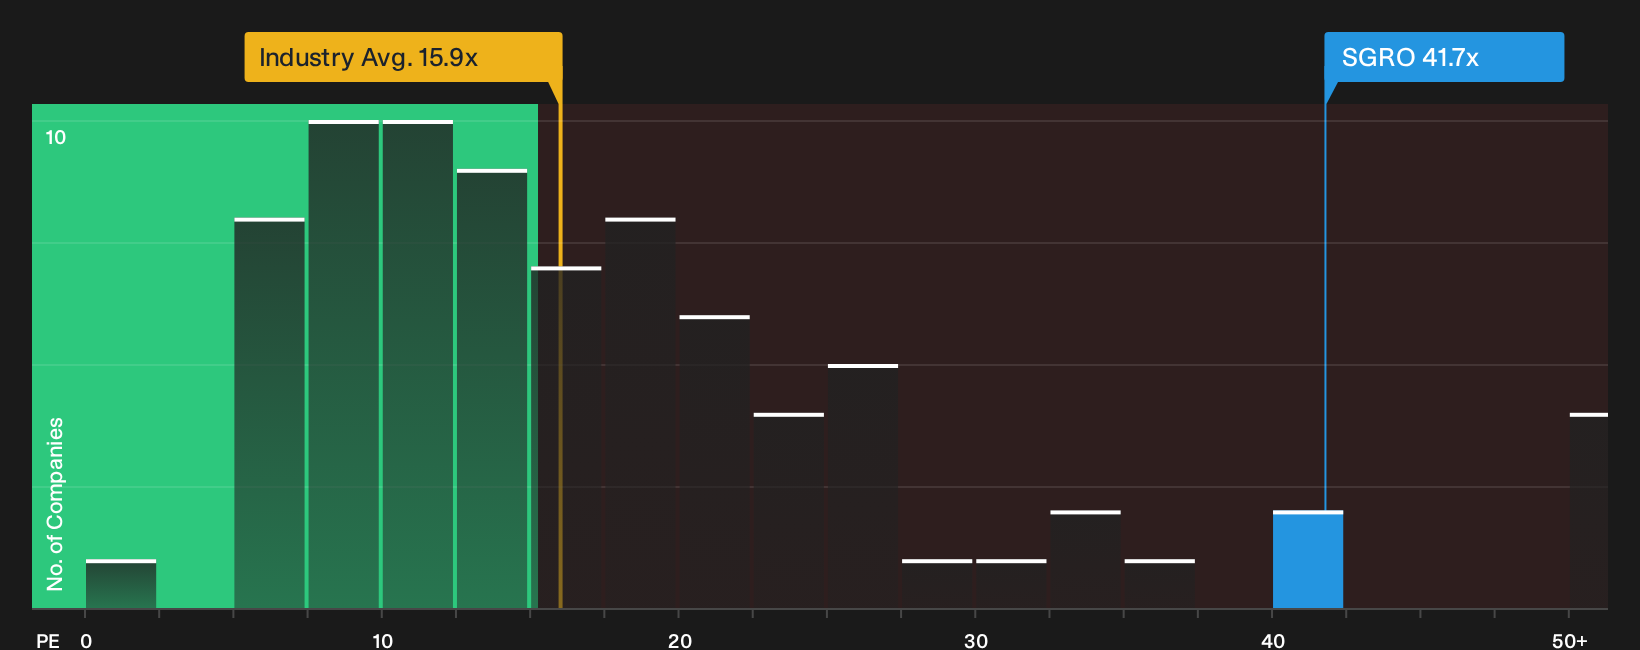
SEGRO might look modestly undervalued against the £9.39 narrative fair value, yet the P/E story is very different. The shares trade on 41.7x earnings, compared with 15.7x for global industrial REITs and 14.4x for peers, while the fair ratio sits at 18.5x.
That kind of gap loads more valuation risk onto anyone buying the current price. If earnings stumble or simply come in line with sector norms, how confident are you that this richer multiple holds up?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals rarely resolve themselves. With SEGRO presenting both risk flags and potential bright spots, consider acting promptly to review the data and weigh the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond SEGRO?
If SEGRO has your attention, do not stop here. Broaden your watchlist now so you can compare opportunities and spot better fits for your portfolio.
- Target long term compounders by scanning a curated pool of quality candidates that currently look attractively priced with the 15 high quality undervalued stocks.
- Prioritise resilience first and focus on companies screened for stronger balance sheets and fundamentals through the list of solid balance sheet and fundamentals (9 results).
- Hunt for under the radar potential by reviewing the 5 high quality undiscovered gems before these businesses gain wider attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com