


EN
How Investors Are Reacting To ONEOK (OKE) Permian NGL Expansion
- ONEOK has outlined plans to expand its natural gas liquids pipeline system across the Permian and into New Mexico, linking new third party processing plants in the northern Delaware to its network and targeting completion in the third quarter of 2027.
- The planned NGL expansion is aligned with ONEOK’s Texas City LPG export terminal, expected to start operations in early 2028, which could tighten the connection between upstream volumes in the Permian and downstream export capacity on the Gulf Coast.
- We will now look at how ONEOK’s Permian NGL buildout, including the extension into New Mexico, could reshape the overall investment narrative.
Scan more midstream opportunities aligned with ONEOK's buildout by zeroing in on infrastructure focused energy players in the 43 power grid technology and infrastructure stocks that are positioned to benefit from rising throughput and export demand.
ONEOK Investment Narrative Recap
To own ONEOK, an investor needs to be comfortable with a midstream model that leans on steady fee based cash flows, incremental volume growth and disciplined capital allocation. The analyst consensus Narrative on Simply Wall St leans on earnings that are forecast to grow 5.4% per year, supported by projects like Brazos Midland and Texas City. The new Permian NGL expansion fits that build and does not radically change the near term business setup.
The key short term swing factor stays execution against current guidance while managing margin pressure in NGLs and softer Natural Gas Pipelines earnings as Waha to Katy spreads narrow. The biggest risk remains that volume, mix or contract terms on new Permian infrastructure, including Brazos and Cassidy II, do not support the extra capital that ONEOK is already committing.
The Texas City LPG export joint venture is the announcement most tightly linked to this NGL pipeline buildout. It is being constructed for 200,000 barrels per day of capacity and is already 80% contracted with long term customers, which ties directly into how incremental Permian liquids can be pulled through to the Gulf Coast over time.
For you as a shareholder, the combination of Texas City and the new Permian NGL extension concentrates execution risk into a few large projects, but it also clarifies the operating story. If ONEOK delivers these assets on time and on budget, they may support higher utilization across the integrated system. If schedules slip or returns fall short, the added leverage and capital outlay could weigh on future flexibility.
ONEOK's narrative projects US$40.4b revenue and US$4.4b earnings by 2029. This assumes revenue remains fairly flat over the next few years and implies an earnings increase of roughly US$0.7b from current earnings of about US$3.7b.
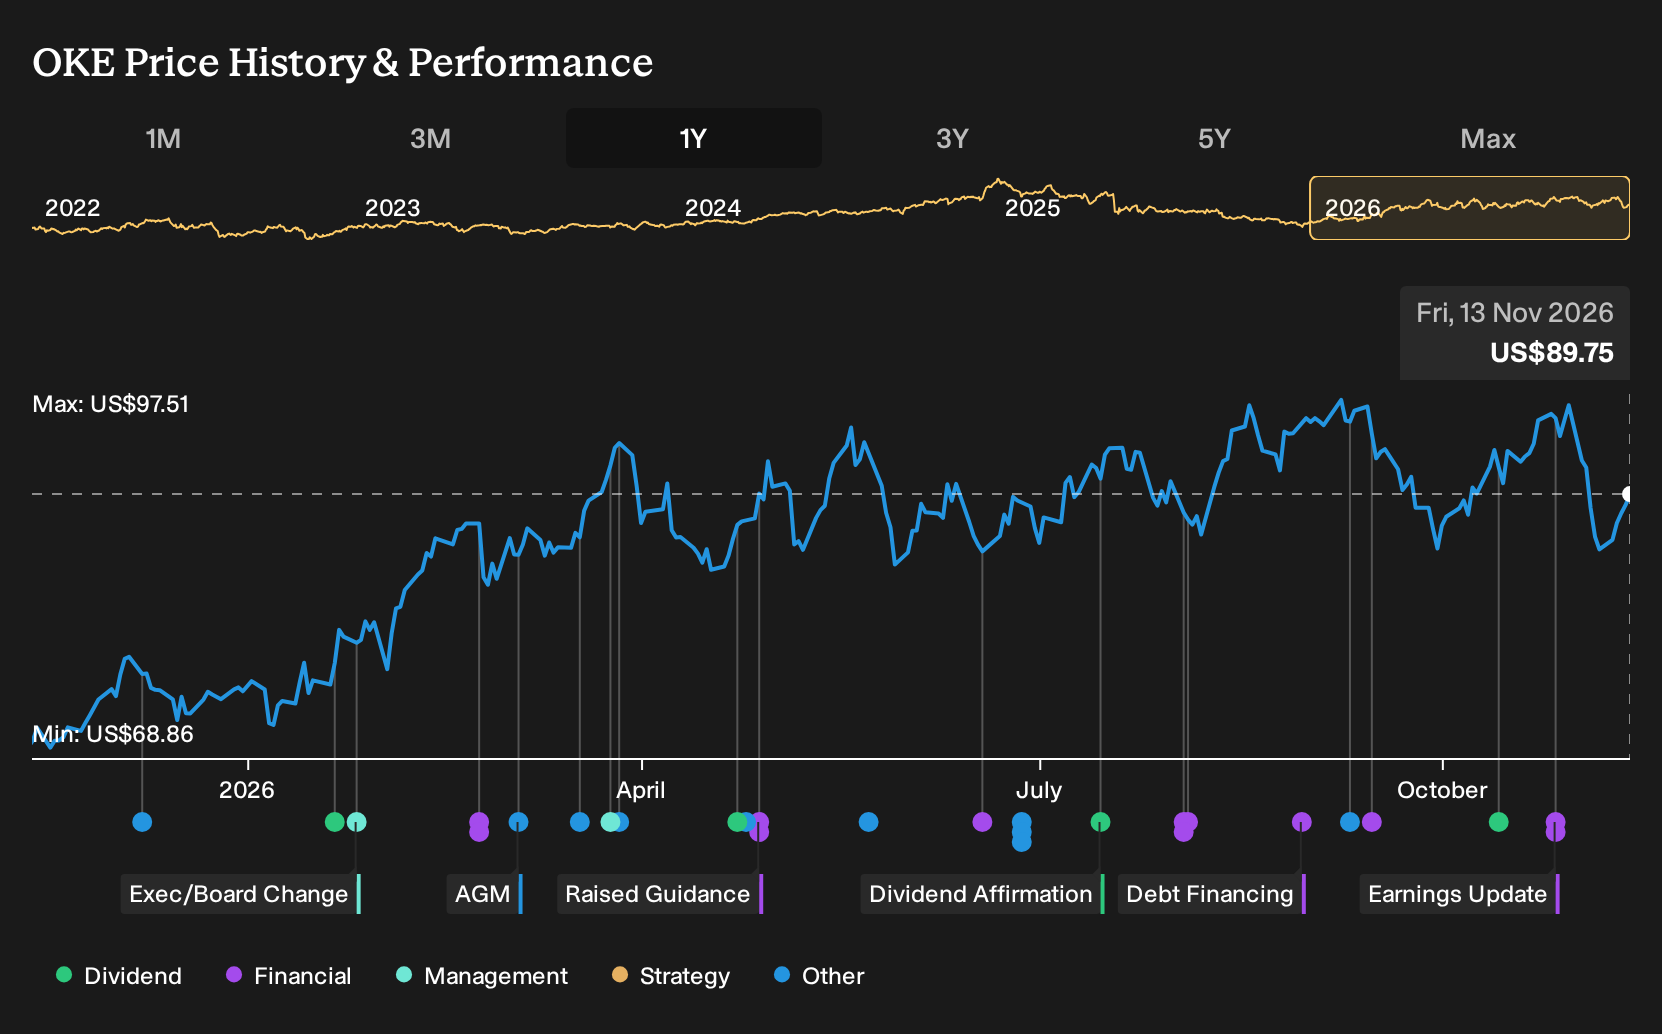
Discover why ONEOK's fair value indicates a 13% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view on ONEOK focuses on a risk that all this new Permian and export capacity simply earns less than it costs to build. The most cautious analysts were assuming revenue would decline about 6.1% a year and earnings would stay around US$4.1b, so their pre news narrative was already far more restrained. This fresh NGL expansion could push those assumptions to shift, which is why it helps to compare several competing narratives before you decide what feels reasonable.
Explore 4 other ONEOK fair value estimates, including one that suggests it could be worth just $93.00.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your ONEOK research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for ONEOK. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easy to evaluate ONEOK's overall financial health at a glance.
Looking for more ONEOK style investment ideas?
Once you have a view on ONEOK, it can help to compare it with other candidates that fit different roles in your portfolio, from higher yield to lower risk to potential mispricing.
- For investors who want potential mispriced opportunities with solid quality markers, scan our 32 high quality undervalued stocks and see which businesses fit your checklist.
- If capital preservation and steadier profiles matter most to you, narrow your focus to the 31 resilient stocks with low risk scores and compare how their balance sheets and risk scores line up.
- When you want to widen the opportunity set beyond well known midstream operators, review the 20 high quality undiscovered gems and see which overlooked companies deserve a closer look.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com