


EN
Japanese Growth Stocks To Watch In November 2026
AI infrastructure exports have become a powerful growth engine for East Asia, with AI related goods accounting for most of global trade expansion this year. That kind of demand puts fast growing Japanese companies in the spotlight, especially those expected to grow earnings over the next few years while keeping their balance sheets in reasonable shape. This article highlights three such Japanese growth stocks from our screener and explains what makes each worth a closer look.
The three stocks highlighted here offer a compelling starting point if you want exposure to healthy high growth potential businesses that still keep an eye on balance sheet strength. However, if you want the standouts, these 19 best high growth potential stocks are the most outstanding.
Sansan (TSE:4443)
Sansan runs a cloud platform that helps corporate clients manage business cards, contact data and related workflows. This ties directly into the screener theme through subscription-based software that can scale earnings. Most revenue comes from the Sansan and Bill One segment at ¥48,865 million, with a smaller Eight unit at ¥7,143 million, and the group is valued at about ¥275 billion.
Sansan links neatly to the Healthy high growth potential theme, with earnings forecast to rise about 23.39% a year and net profit margins recently at 14.3%. That level of earnings power can have a significant impact if there is any change in how effectively those subscriptions convert into sustained profit growth.
That kind of earnings acceleration makes it worth reading the 3 key rewards and 1 important warning sign before those margins either widen further or start to compress.

Micronics Japan (TSE:6871)
Micronics Japan focuses on semiconductor test and inspection gear such as probe cards, wafer probers and test sockets, which ties directly into the Healthy high growth potential theme. This core probe card unit generates about ¥84,868 million, far outweighing its ¥1,391 million TE segment, and the group is valued at roughly ¥414 billion.
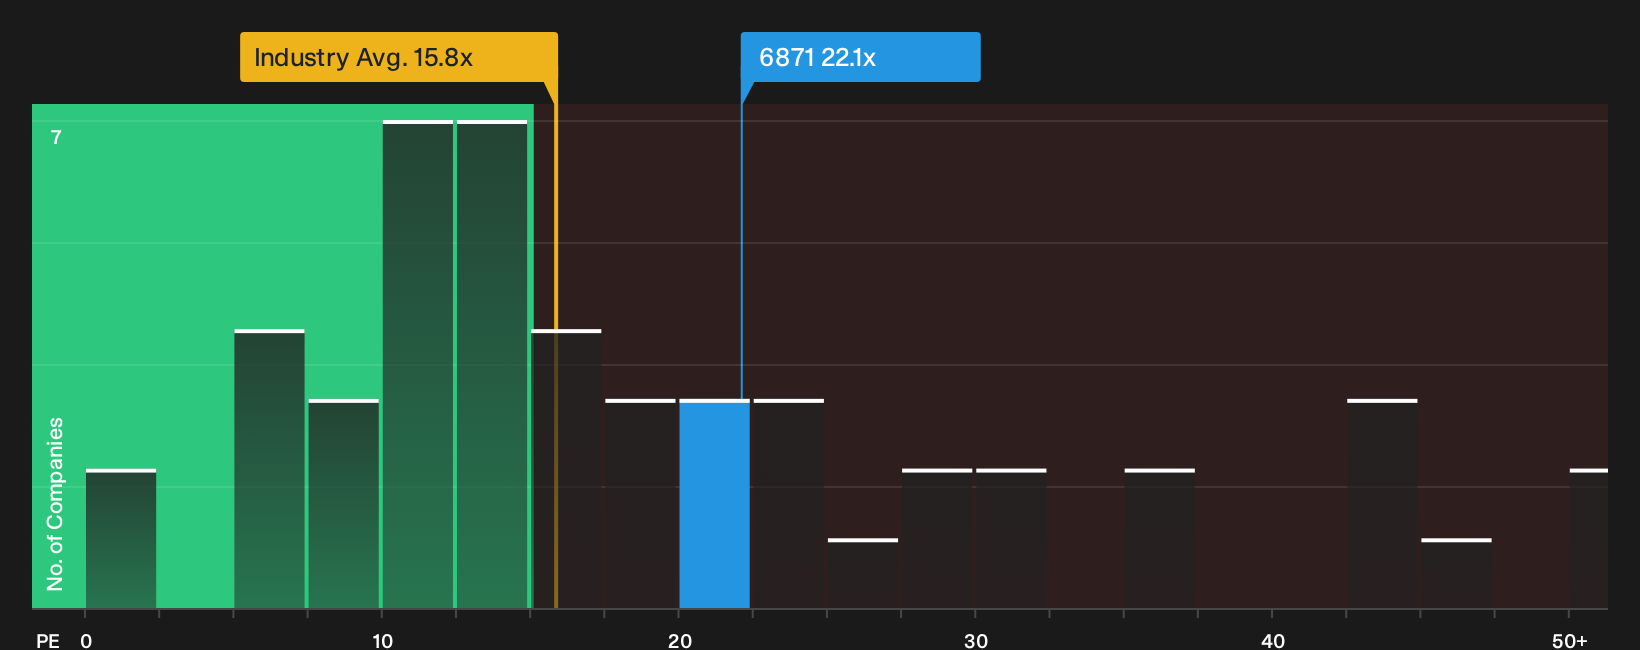
Micronics Japan illustrates the purpose of this screener, with earnings forecast to grow about 24.88% a year and revenue expected to rise around 23% as chip testing demand expands. A P/E of 22.1x reflects much of that optimism, so the main consideration is how far returns on that capital can stretch before buyers hesitate.
That valuation tension is exactly why checking the 2 key rewards and 1 important major warning sign can help you see whether Micronics Japan’s growth story is stretching too far or still has room.
freee K.K (TSE:4478)
freee K.K. runs cloud-based accounting, HR and related tools for Japanese businesses, tying directly into the Healthy high growth potential theme through subscription SaaS that aims to drive earnings expansion. The group is valued at about ¥230.0b based on its current market capitalization.
freee K.K. aligns closely with this screener because analysts expect earnings to grow rapidly over the next 3 years, supported by a subscription model that focuses on accounting and HR software for Japanese corporates. The attraction is clear for growth investors. However, what happens if one unseen pressure changes how efficiently that recurring income turns into lasting profit improvements could matter a lot.
That profit conversion risk is exactly where the 3 key rewards and 1 important major warning sign can sharpen your view before freee K.K’s earnings trajectory decouples from the story you think you own.

Seeking Alternatives Before The Crowd
Fresh opportunities move fast. Breakout stories build momentum, laggards get caught dropping, and under the radar for now ideas do not stay quiet forever. Act now.
- Spot durable income plays while yields still look reasonable by scanning a curated pool of 28 dividend fortresses before yield hunters rush in.
- Ride the build out of next generation computing by tracking curated 25 quantum computing stocks before institutional money starts chasing the theme.
- Get ahead of infrastructure momentum by zeroing in on 43 power grid technology and infrastructure stocks before grid upgrades move from quiet planning to front page stories.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com