


EN
SI BONE (SIBN) Stock May Be Fully Valued Despite Strong Q3 Growth
SI-BONE has put up a strong 1 year share-price run, yet the real test for investors is whether that kind of move lines up with what the business is generating in sales. With the stock now trading around US$23.44, the question is how well the current price reflects the revenue profile that underpins the story.
- The share price is up 34.6% over the past year, which raises the question of whether that gain is fully grounded in the company’s current and expected sales base.
- Recent revenue growth and a smaller loss suggest the business may support higher sales over time, which can influence how much investors are willing to pay for each dollar of turnover.
- The analysts covering SI-BONE have run their own numbers. See what analysts think SI-BONE's shares could be worth.
The issue now is whether SI-BONE’s present share price is justified by the level of sales it is generating and what that implies for its valuation on a pure revenue lens.
If you want to test the same sales driven valuation question beyond SI-BONE, you can benchmark it against a wider field using the 32 high quality undervalued stocks.
Is SI-BONE Getting Expensive on Sales?
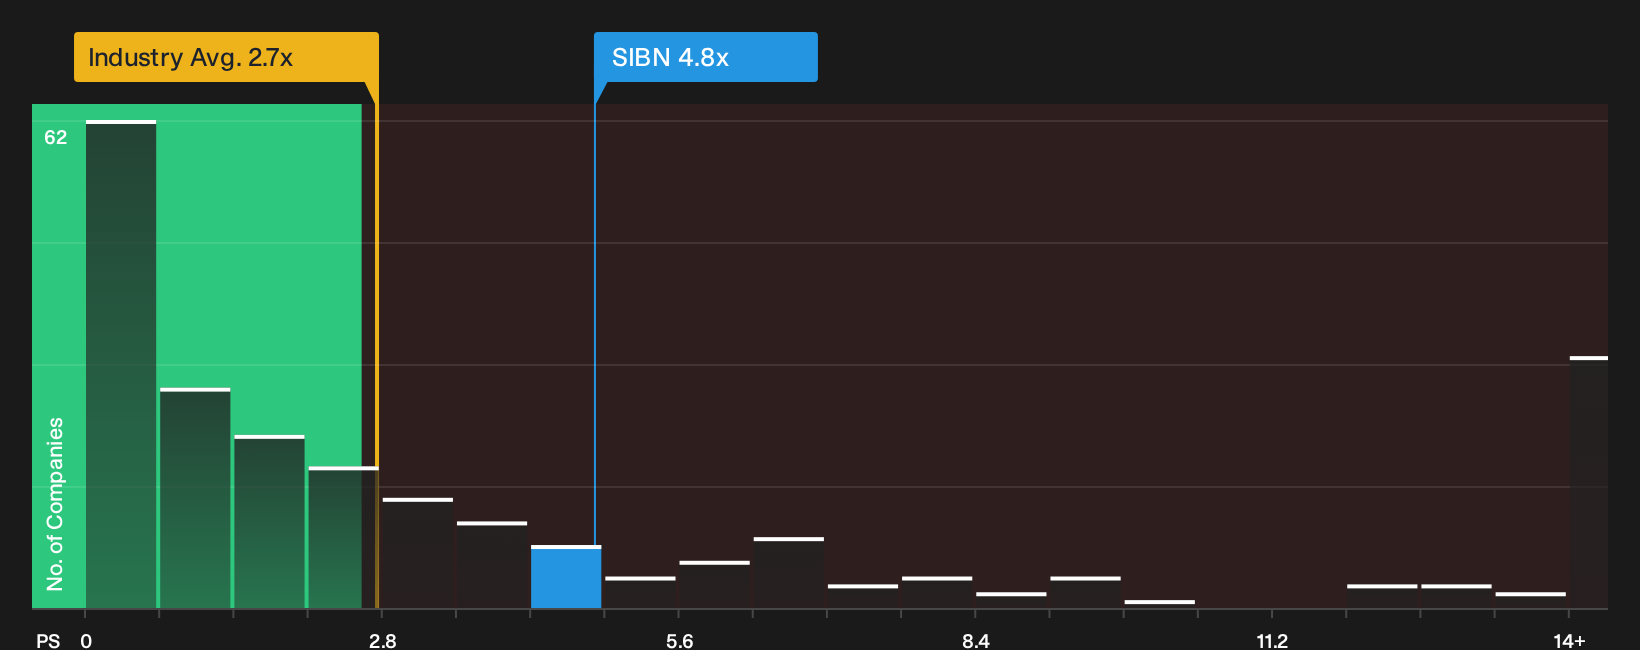
P/S is a useful lens for SI-BONE because investors are currently focused on how much they are paying for its revenue base rather than its earnings. At a P/S of roughly 4.8x, the stock trades above the medical equipment industry average of about 2.7x and also above peers around 4.2x. This means buyers today are accepting a richer price tag for each dollar of SI-BONE’s sales than is typical in the sector.
The fair multiple implied by the valuation model points to a level below the current 4.8x, so the shares screen as overvalued on this P/S framework once growth, margins, size and risk are taken into account. Despite the strong Q3 2026 update with 15% revenue growth and a narrower loss, the current P/S already appears to incorporate much of that progress, so you would need to be confident that SI-BONE can keep converting its sales story into sustained business quality to justify paying this kind of premium. Explore the numbers behind SI-BONE's P/S valuation.
The SI-BONE Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where that P/S discussion for SI-BONE leaves off by spelling out which combinations of future growth, profitability and eventual earnings strength would need to play out for the stock to be worth materially more or materially less than today’s price. Each one treats fair value as a hypothesis about SI-BONE’s business that you can watch over time rather than a frozen snapshot on a single date.
For SI-BONE, the bullish lens leans into physician adoption and new spine products, while the cautious view worries the current price already bakes in a lot of that progress.
Bull case: 8% undervalued
This view comes from the analyst consensus Narrative on Simply Wall St, which ties the upside to a few concrete growth levers.
"Continued expansion of SI-BONE’s physician base, with 1,715 unique physicians performing procedures in Q2 2026 and higher case volumes among repeat users, points to further utilization gains…"
Discover why this Narrative puts SI-BONE at 8% undervalued.
Bear case: roughly fairly valued
The bearish analyst Narrative on Simply Wall St argues that execution risk and cost pressure already look embedded in where SI-BONE trades today.
"While SI-BONE continues to report high gross margins near 79%, management now guides medium-term gross margin to 77 to 78% because of higher non-cash depreciation from added surgical capacity that is coming online ahead of the newer product and partnership revenue ramp…"
Explore why this Narrative puts SI-BONE at roughly fairly valued.
One more SI-BONE check that sits outside the valuation math
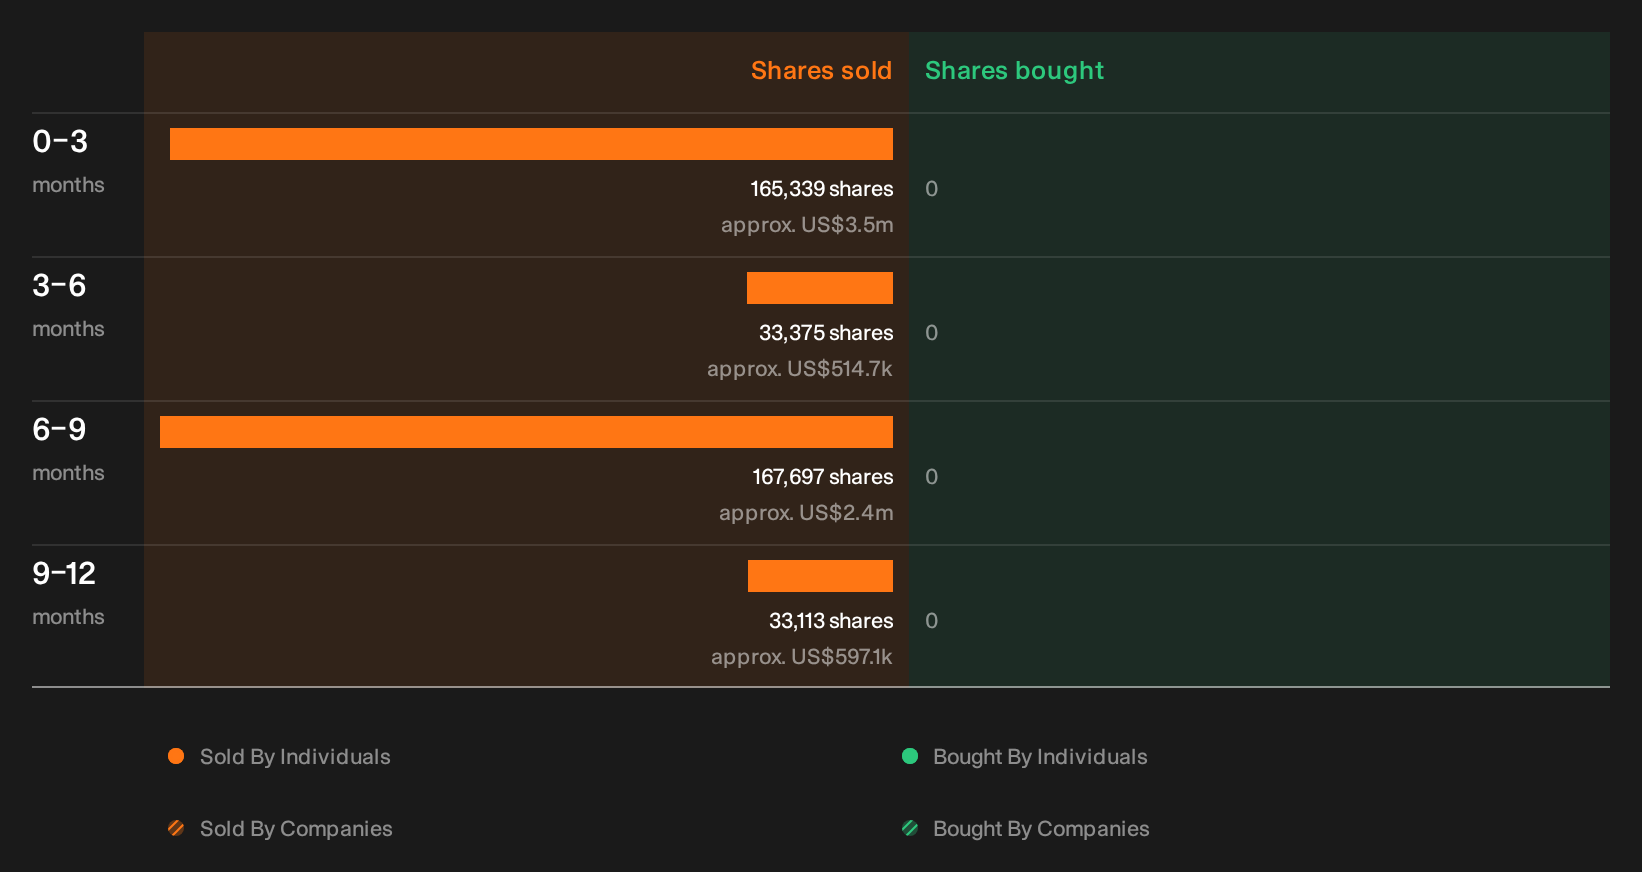
Price tags and growth stories only tell part of it, because recent director and executive share sales also sit on the record, with the individuals, sizes and possible signals left for you to review. See the recent insider selling flagged for SI-BONE.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com