


EN
G Mining Ventures (TSX:GMIN) Reaffirmed Guidance, Is The 27% Discount Still There?
G Mining Ventures (TSX:GMIN) just posted its third quarter 2026 results, highlighting higher gold production at the Tocantinzinho mine, firm free cash flow, and reaffirmed output guidance that keeps the Oko project timeline in focus.
The latest earnings update landed alongside a sharp 1 day share price gain of 9.89%, yet the stock is still down 7.54% on a 90 day share price basis, which suggests sentiment has only recently improved. Even so, G Mining Ventures has a 21.06% year to date share price return and a 1 year total shareholder return of 61.12%. The 3 year total shareholder return above 8x and a very large 5 year total shareholder return point to strong long term momentum that recent volatility has not erased.
Scan G Mining Ventures alongside other gold-focused operators and see how it stacks up against 33 elite gold producer stocks in terms of production scale, costs, and market performance.
After a 1 day jump and a powerful multi year run, G Mining Ventures now forces a simple question: Is the bigger upside still ahead, or did most of it already happen before this quarter?
Most Popular Narrative: 27% Undervalued
Against a last close of CA$46.21, the analyst consensus Narrative on Simply Wall St frames G Mining Ventures with a fair value of CA$63.46, using a 7.85% discount rate and detailed revenue and earnings forecasts built into that view.
The TZ mine is operating with total cash costs of $748 per ounce and all in sustaining costs of $1,155 per ounce in 2025, which are described as peer leading. Management aims to keep focusing on productivity and cost management, which could help protect margins and earnings if industry wide cost pressures persist.
See why 16 investors see G Mining Ventures as 27% undervalued.
That framework points to a valuation that sits about CA$17 above where G Mining Ventures trades today. It rests on analysts modelling strong revenue expansion, high profit margins and a future P/E of 17.2x by 2029, all discounted back at 7.85% to reach the CA$63.46 figure.
Result: Fair Value of CA$63.46 (UNDERVALUED)
Still, the G Mining Ventures story leans heavily on unhedged gold prices and tight Oko West construction budgets, so weaker bullion or cost overruns could quickly challenge this upbeat narrative.
Find out about the key risks to this G Mining Ventures narrative.
Another View: What G Mining Ventures' Current P/E Implies
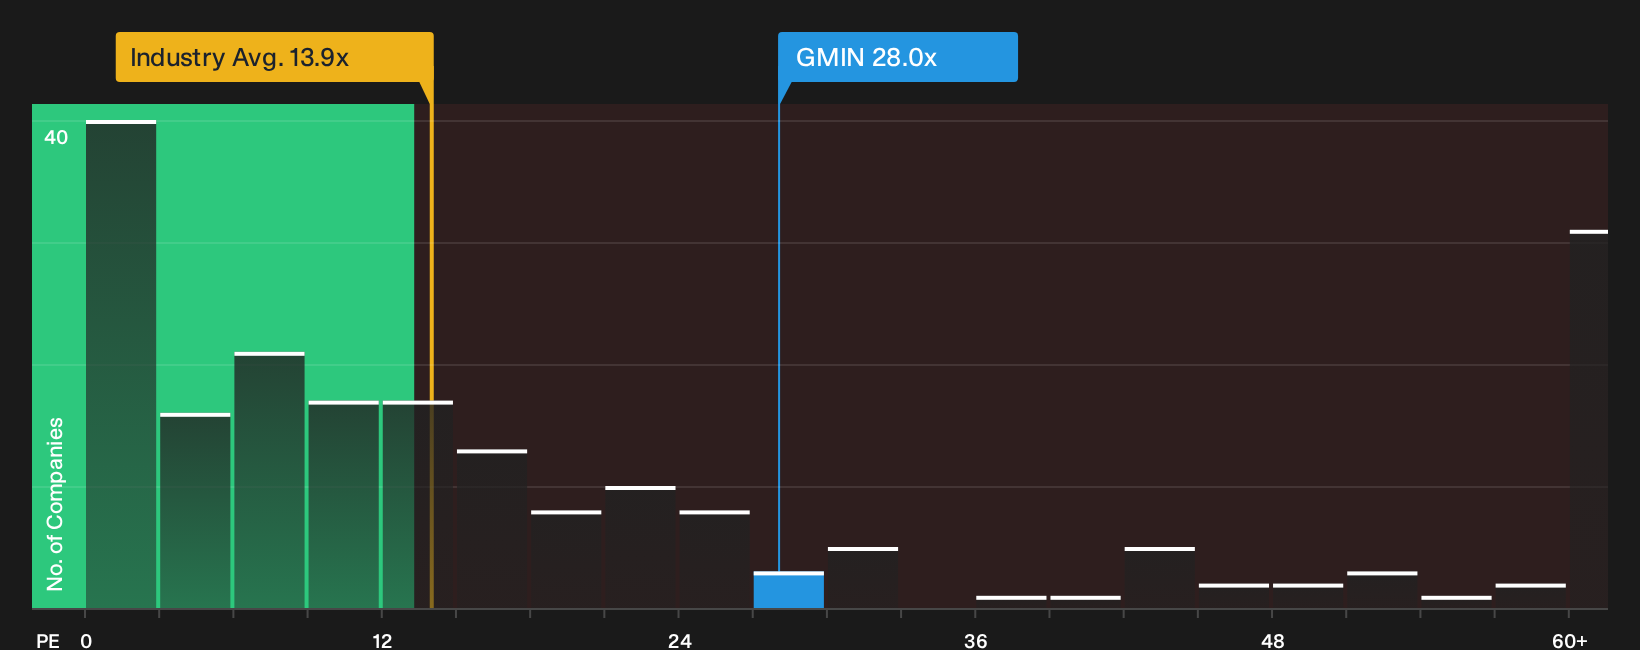
G Mining Ventures screens as expensive on its current P/E of 28x, compared with a fair ratio of 24.3x, the Canadian metals and mining group at 13.9x and peers at 10.8x. That premium can signal confidence, but it also raises the question of how much valuation risk you are comfortable carrying if sentiment cools.
Before leaning too heavily on the analyst fair value, it helps to see what the underlying earnings multiple is really saying about expectations for G Mining Ventures, and how that compares with other miners in detail. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and caution around G Mining Ventures feels familiar, treat it as a signal to check the numbers yourself and move quickly while sentiment is still resetting. To see how the balance of concerns and potential upsides lines up with your own view, start with the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond G Mining Ventures?
If G Mining Ventures has your attention, do not stop there. The real edge often comes from lining up a few strong, differentiated opportunities side by side.
- Target reliable compounding potential by scanning a 3 dividend fortresses that focuses on income streams which can complement more growth tilted holdings.
- Hunt for quality at a sensible entry point through a 6 high quality undervalued stocks that filters for fundamentals first, not hype.
- Prioritise resilience in tougher markets with a 9 resilient stocks with low risk scores that screens for sturdier balance sheets and steadier business profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com