


EN
Will Wellness Partnerships Change Ulta Beauty Stock Narrative
- Oura, WHOOP, PROYA and KSECRET have each announced partnerships that bring health wearables and new global skincare lines into Ulta Beauty’s stores and online channels across the U.S.
- These additions deepen Ulta Beauty’s wellness and prestige skincare mix, giving shoppers more reasons to visit stores, engage with loyalty rewards and build multi category baskets.
- We will now look at how Ulta Beauty’s push into wellness wearables and global skincare could influence its broader investment narrative.
Scan beyond Ulta Beauty and spot other retailers leaning into wellness, loyalty ecosystems, and higher value baskets through our hand picked 32 high quality undervalued stocks today.
Ulta Beauty Investment Narrative Recap
To own Ulta Beauty, you need to believe the wellness, prestige skincare and marketplace efforts described in the analyst consensus Narrative on Simply Wall St can keep feeding steady comparable sales and earnings, even as competition in beauty and social commerce stays intense. The clearest near term catalyst is the 2026 earnings report on December 3, where investors focus on comps, margin mix and loyalty engagement.
The biggest risk right now comes from store productivity and margins if traffic softens while Ulta Beauty carries rising rent, payroll and wellness build out costs. The new wearables and global skincare launches look directionally helpful to baskets and loyalty, but on their own they do not radically change that near term risk reward balance.
The Oura Ring 5 partnership is the cleanest operational link to this wellness story. It plugs a high visibility health wearable into about 1,000 Ulta Beauty stores and Ulta.com, all inside the Wellness by Ulta Beauty concept that management has described as a potential next billion dollar category. It also leans on that 47 million member rewards base, since members can earn points on qualifying Oura purchases.
For catalysts, the key question is whether Oura can drive incremental trips, not just one time gadget sales. Strong adoption would support the wellness thesis in the analyst consensus Narrative on Simply Wall St, help store traffic and reinforce Ulta Beauty’s data and media engines such as UB Media. Weak in store attachment or low repeat engagement would leave wellness more niche and keep margin pressure and competitive promotion as the bigger focus.
Ulta Beauty's current analyst narrative points to revenues of US$15.1b and earnings of US$1.4b by 2029. This outlook is built on an assumed 5.2% yearly increase in revenue and an earnings rise of about US$0.2b from US$1.2b today.
Uncover why Ulta Beauty's fair value indicates a 4% potential downside to its current price, which leaves little room for error.
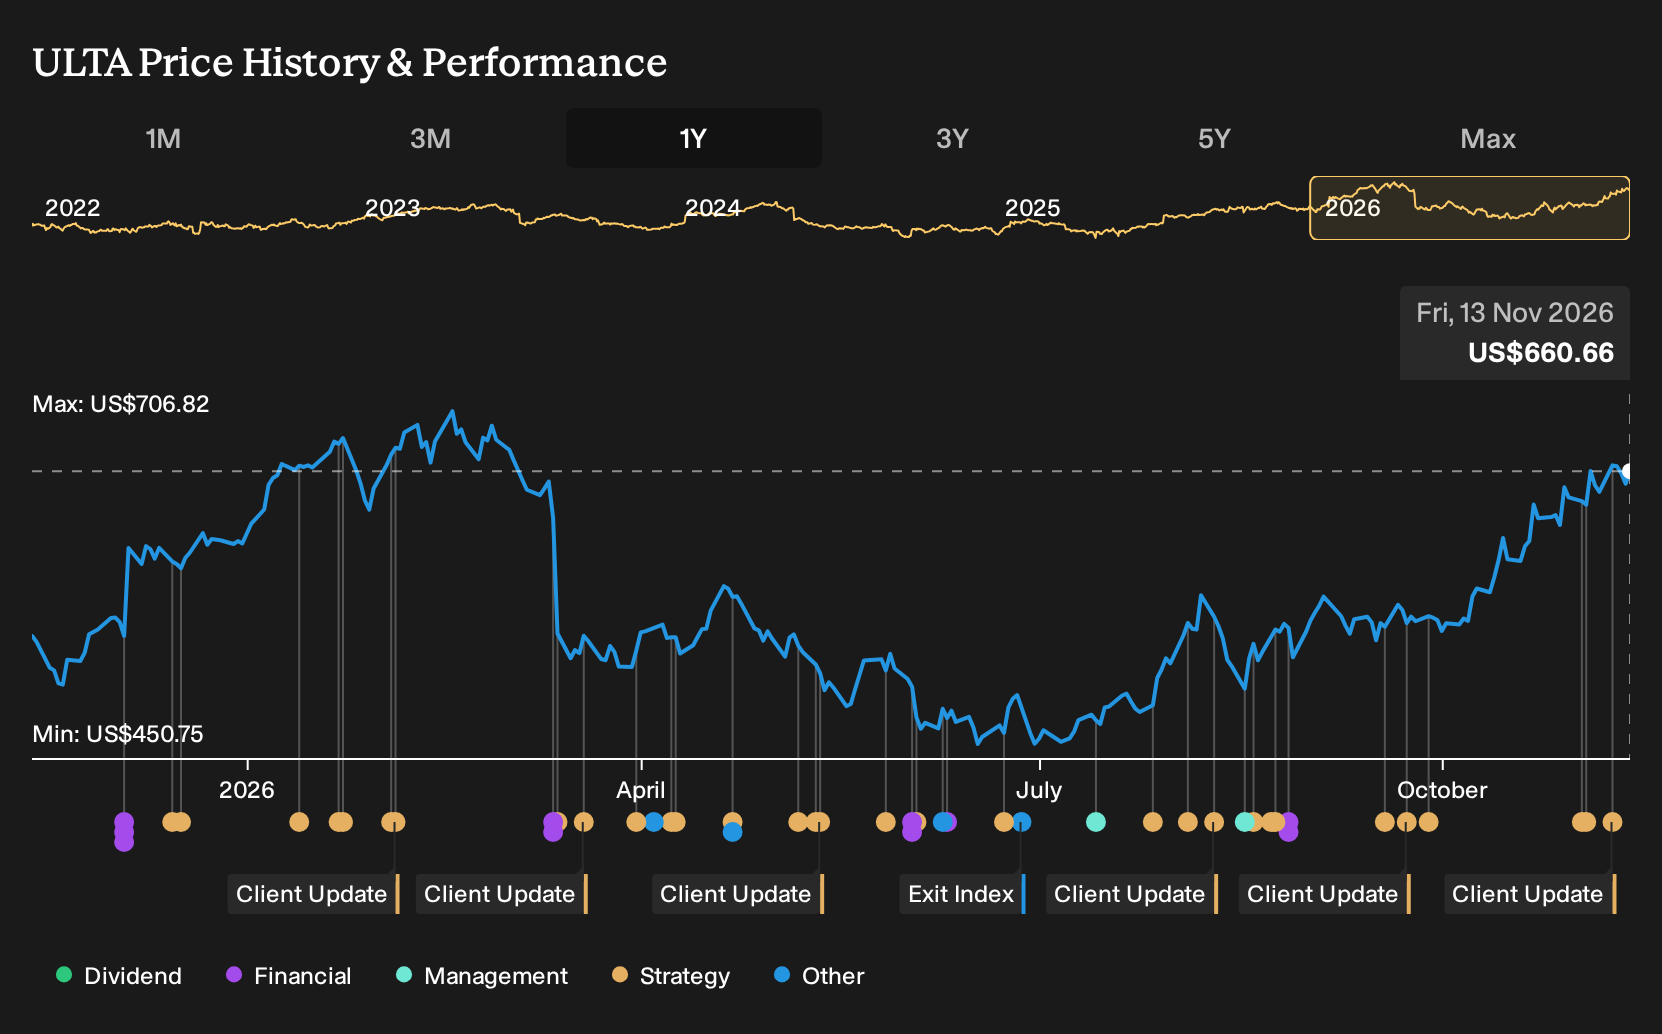
Exploring Other Perspectives
One alternate view on Ulta Beauty leans hard into risk. The most bearish analysts worry that wellness and K Beauty rely on periodic brand launches, not steady demand. They were only modeling about 4.3% yearly revenue growth to roughly US$14.7b and US$1.4b earnings by 2029. These Oura, WHOOP, PROYA and KSECRET deals could challenge that story. You may want to compare several narratives and see which now feels closer to your own expectations.
Explore 6 other Ulta Beauty fair value estimates, including one that suggests as much as 41% downside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Ulta Beauty research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Ulta Beauty. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ulta Beauty's overall financial health at a glance.
Looking for more investment ideas beyond Ulta Beauty?
Once you have a view on Ulta Beauty, it can help to compare the story with other opportunities that match your risk, income and quality preferences. The Simply Wall St Screener lets you quickly filter the market down to a handful of stocks that fit what you care about most.
- If you want income potential plus resilience, you could start with companies that combine higher yields with balance sheet strength by reviewing 6 dividend fortresses.
- If capital protection matters more than big swings, you can narrow your focus to businesses with stronger fundamentals and steadier risk profiles via the 31 resilient stocks with low risk scores.
- If you are hunting for mispriced quality, you can scan for stocks with solid cash generation and fundamentals that may not yet be widely followed using the 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com