


EN
Hinge Health (HNGE) Could Be 20% Undervalued As Profitability Reshapes The Narrative
Hinge Health (HNGE) moved into focus after fresh earnings on 2 November 2026. Third quarter revenue was US$234.97 million and net income was US$57.4 million, replacing a loss a year earlier.
Hinge Health shares trade at US$115.39 after a 1 day share price return that declined 4.63%, yet the 90 day share price return of 30.40% and year to date share price return of 153.27% point to strong momentum. The 1 year total shareholder return of 181.71% shows how recent earnings guidance, raised full year targets and leadership changes have reshaped expectations.
Scan how Hinge Health fits into the broader opportunity by comparing it with 36 healthcare AI stocks that also sit at the crossroads of software, data, and healthcare delivery.
After a 153% year to date surge and a sharp swing into profitability, the puzzle with Hinge Health is simple: Is most of the upside already in the price, or does the current valuation still leave headroom?
Most Popular Narrative: 20% Undervalued
The narrative fair value of $145.04 sits well above Hinge Health's last close at $115.39, which frames the current pricing debate. According to Ontological, an investor in the Simply Wall St Community who wrote the narrative, that gap rests on a specific view of growth, margins, and cash generation under a 7.236% discount rate.
Hinge Health has quickly distinguished itself as one of the most successful IPOs of 2025, combining rapid revenue growth, widening margins, and a scalable AI-driven care model. The company’s focus on musculoskeletal (MSK) health; covering prevention, acute injury, chronic pain, and post-surgical recovery, has resonated with employers and insurers, driving adoption across millions of contracted lives.
See why 4 investors see Hinge Health as 20% undervalued.
The fair value estimate of $145.04 implies around a 20.4% gap to the current share price, which the community view characterises as undervalued. That stance leans on the idea that rapid revenue expansion, strong margins, and high quality earnings can support future cash flows that the market price does not fully reflect based on the 7.236% discount rate used in the model.
Result: Fair Value of $145.04 (UNDERVALUED)
Still, the bullish Hinge Health narrative could be knocked off course if elevated valuation multiples meet slower MSK adoption, or if regulatory pressure hits employer demand.
Find out about the key risks to this Hinge Health narrative.
Another View: Hinge Health Through The P/E Lens
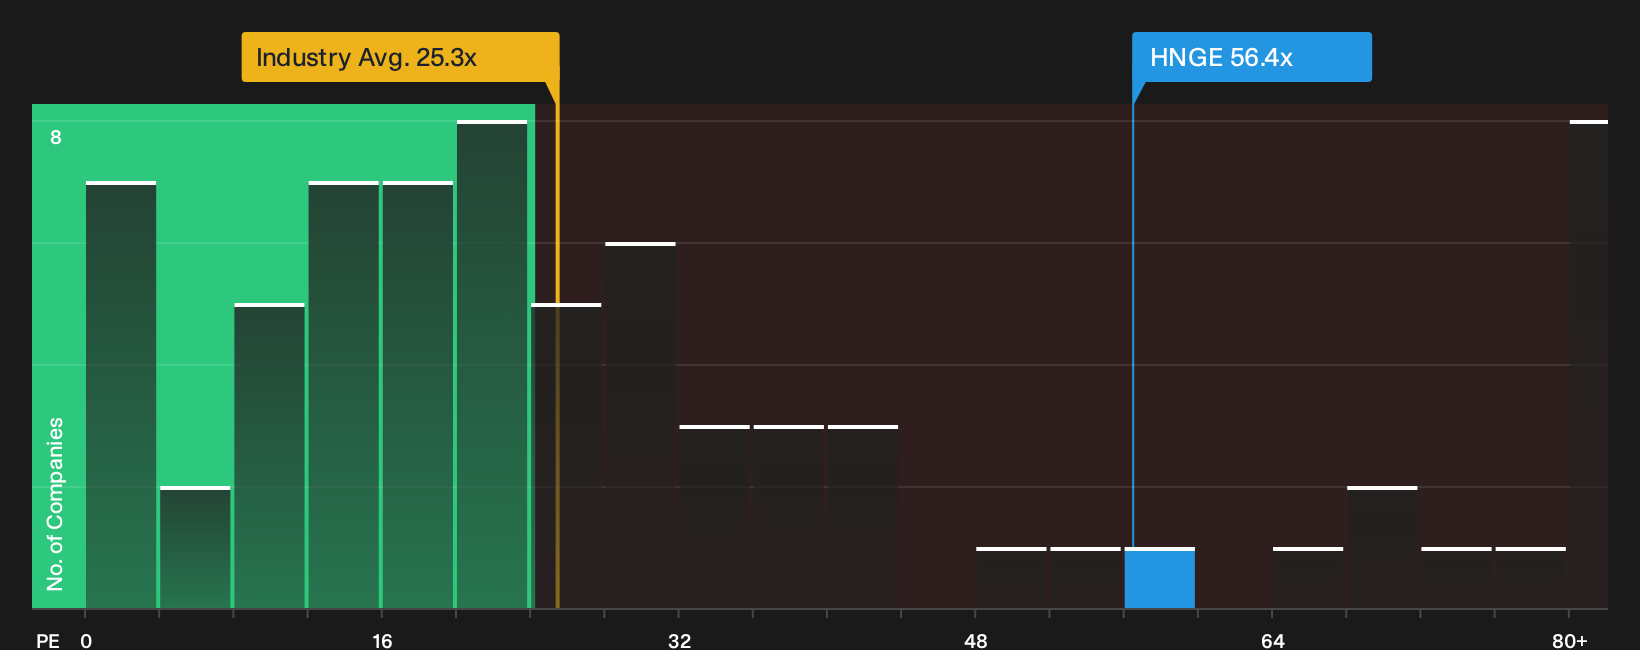
Another way to look at Hinge Health is through its P/E ratio. The stock trades at 56.4x earnings, compared with 48.6x for peers and 25.3x across the broader US Healthcare group. The fair ratio is 35.6x, which points to rich pricing and raises a simple question: How much growth are you really paying for?
For investors comparing valuation tools, this is where our ratio work helps. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Hinge Health is clearly upbeat, and the numbers give plenty to debate, so move fast and test the thesis against your own framework. A good place to start is by weighing the 3 key rewards
Looking for more Hinge Health style investment ideas?
Do not stop with Hinge Health alone when tools exist to help you spot fresh opportunities in minutes using the Simply Wall St Screener.
- Target quality at a discount and scan for companies that combine solid fundamentals with appealing valuations using the 32 high quality undervalued stocks.
- Protect your downside and narrow in on sturdier balance sheets by filtering for companies in the list of solid balance sheet and fundamentals (24 results).
- Hunt for potential future winners that the crowd has not focused on yet by checking the 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com