


EN
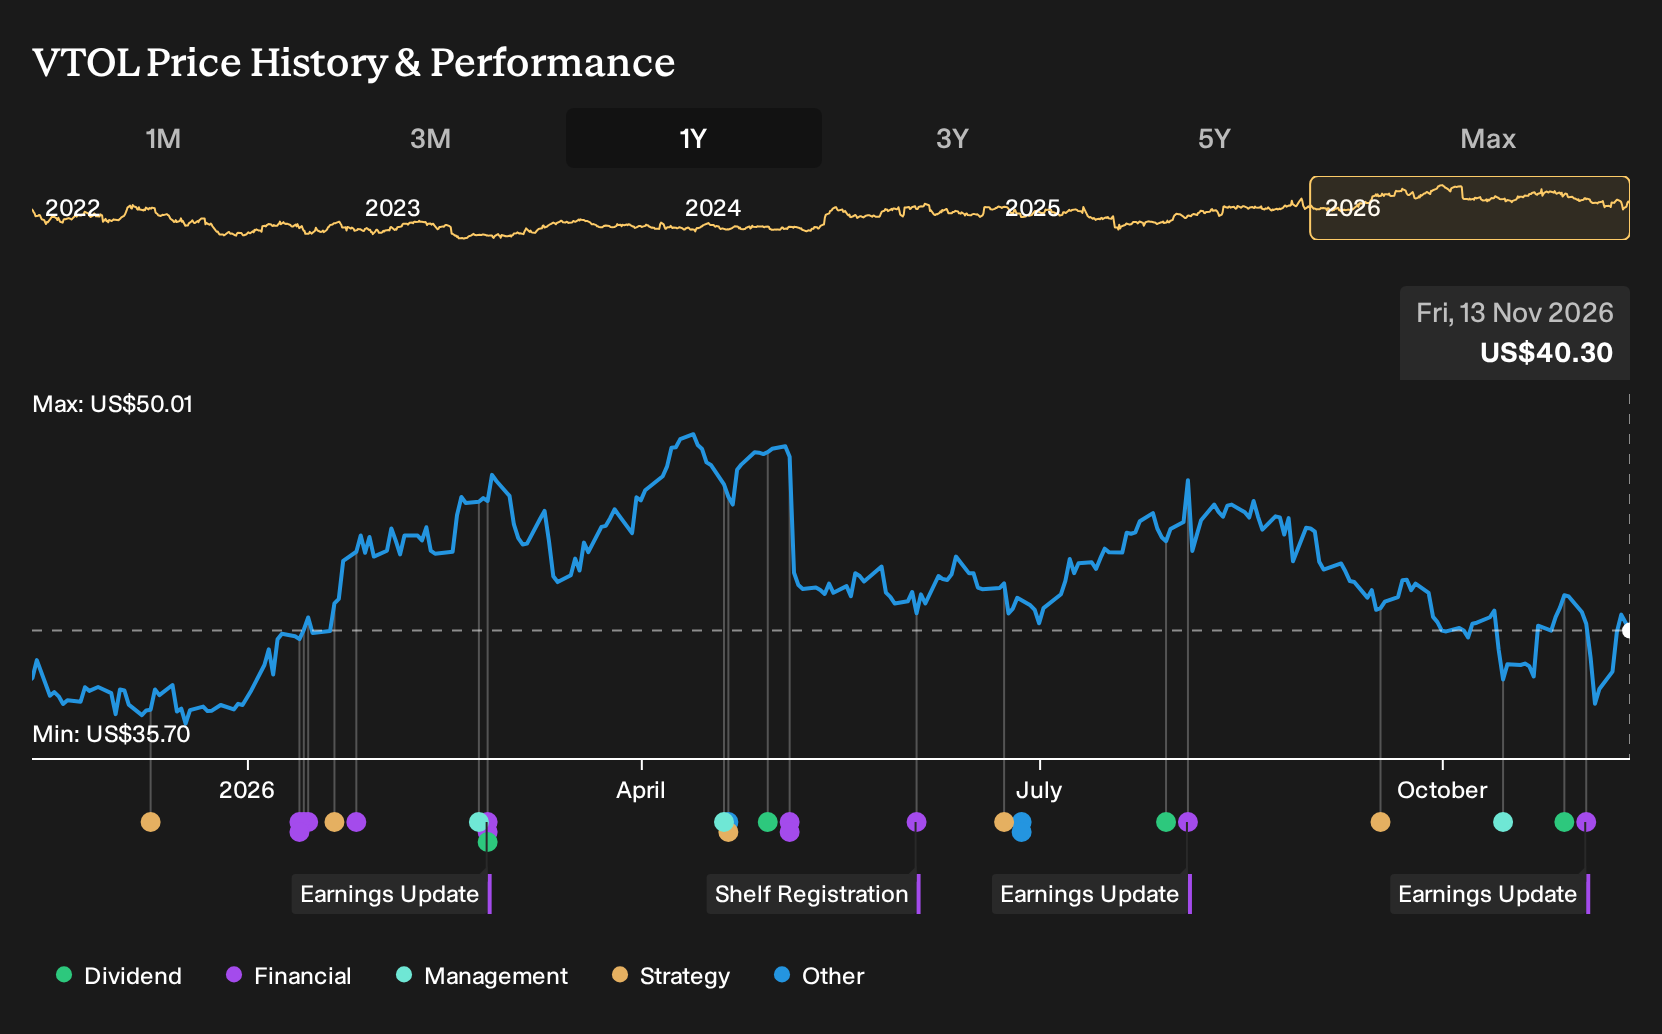
How Third Quarter Earnings Will Impact Bristow Group (VTOL) Investors
- Bristow Group reported third quarter 2026 sales of US$437.92 million, net income of US$27.73 million, and diluted EPS from continuing operations of US$0.93.
- The latest quarter highlights how Bristow Group’s earnings power is directly linked to contracted aviation services, where even modest profit levels can materially shape cash generation potential.
- We will now look at how Bristow Group’s US$27.73 million quarterly net income might reshape the investment narrative already in place.
Scan beyond Bristow Group and compare its contracted aviation earnings profile with list of solid balance sheet and fundamentals (24 results) to see how other operators with resilient finances are positioned after their latest results.
Bristow Group Investment Narrative Recap
For an investor to stay with Bristow Group, the core belief is that contracted aviation work for governments and offshore energy clients will keep supporting a more predictable earnings profile. The US$27.73 million third quarter net income fits that story, as it shows the business generating profit while those long term contracts continue to ramp.
The nearest swing factor is still execution on government and offshore transitions, particularly where aircraft availability and penalties have been pressure points in the analyst consensus Narrative on Simply Wall St. If the recent earnings do not signal a clear improvement in margins, the main risk around weaker profitability in the short term probably remains intact.
Among the earlier developments tied into this, the repricing of Offshore Energy Services contracts is the clearest companion to the latest quarter. Management has talked about average rates that are about 25% above legacy levels with most of the portfolio expected to reset by the end of 2026, so investors will likely watch how quickly that mix shows up in reported operating income.
That contract reset sits alongside the Government Services guidance for US$55 million to US$65 million of adjusted operating income on US$475 million to US$495 million of revenue in 2026. In light of the third quarter result, the key operational question is whether Bristow Group can convert that guidance into cleaner margins while still working through supply chain delays and higher operating costs in some of its search and rescue work.
Bristow Group's narrative projects US$2.0b revenue and US$241.1 million earnings by 2029. This projection is based on 7.9% yearly revenue growth and an earnings increase of about US$136.9 million from current earnings of US$104.2 million.
Uncover why Bristow Group's fair value indicates a 60% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One bullish twist on Bristow Group focuses on the tight supply of offshore helicopters. The most optimistic analysts were already penciling in about US$2.0b of revenue and US$224.0 million of earnings by 2029 before this quarter. That sets a far more upbeat story and invites you to compare these pre news expectations with your own view.
Explore 3 other Bristow Group fair value estimates, including one that suggests as much as 362% upside from the current price!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Bristow Group research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Bristow Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bristow Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Bristow Group?
Once you have formed a view on Bristow Group, it often helps to widen the lens and compare it with other companies that share similar financial strengths or income profiles. The Simply Wall St Screener can help you quickly filter the market down to a focused set of stocks that fit the kind of balance sheets, valuations, or dividend profiles you want to research next.
- For investors who care most about financial resilience, start with companies that pair sturdy balance sheets with reliable fundamentals by scanning our list of solid balance sheet and fundamentals (24 results).
- If you want to focus on opportunities where quality and valuation intersect, narrow your search using the 32 high quality undervalued stocks and see which businesses match your own risk and return goals.
- Income focused readers can look for payout strength by filtering for companies with higher yields and solid fundamentals through the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com