


EN
BorgWarner (BWA) Targets Data Center Power Growth, Is The Stock Still Cheap?
BorgWarner (BWA) has two fresh storylines for investors. Management outlined revenue expectations for its turbine generator and data center power products in 2027, and the firm affirmed a quarterly dividend of $0.17 per share.
Recent trading shows that BorgWarner’s share price has given back some ground, with a 30-day share price return down 13.01% and a 90-day share price return down 25.88%, even though the year-to-date share price return is up 9.11% and the 3-year total shareholder return is 53.77%. This points to longer term momentum even as sentiment reacts to new investments in turbine generators and data center power products.
Scan BorgWarner alongside a curated group of companies exposed to similar power and electrification themes by checking the 20 high quality undiscovered gems.
BorgWarner’s share price has pulled back even as its turbine generator and data center plans take shape. Is most of the easy upside already gone, or does the current valuation still leave meaningful room ahead?
Most Popular Narrative: 36% Undervalued
The analyst consensus Narrative on Simply Wall St puts BorgWarner’s fair value at $79.07, which sits well above the last close of $50.89, and frames the new power projects as a key part of that gap.
Expansion into data center power through the turbine generator program, supported by a 2 GW plant in North Carolina and expected revenue of about US$300 million in 2027 at mid teens incremental margins, adds a new earnings stream that is not fully tied to light vehicle cycles and could support operating margin and EPS resilience.
See why 24 investors see BorgWarner as 36% undervalued.
Result: Fair Value of $79.07 (UNDERVALUED)
Still, the BorgWarner narrative can crack if the combustion heavy portfolio loses demand faster than expected, or if the battery segment drag lingers longer than analysts model.
Find out about the key risks to this BorgWarner narrative.
Another View: Multiples Paint A Richer BorgWarner Picture
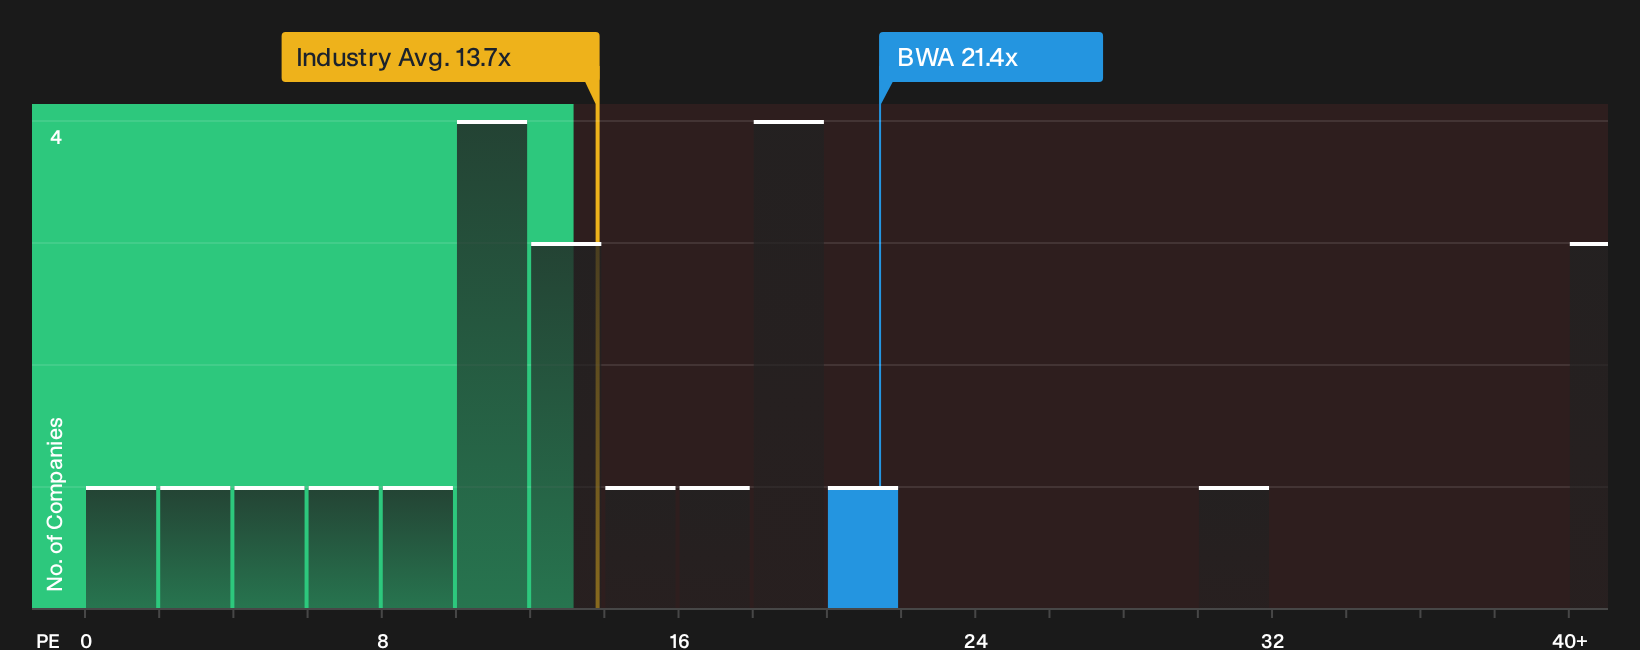
The story shifts when you swap fair value models for simple market ratios. BorgWarner trades on a P/E of 21.4x, while the North American Auto Components group sits near 13.7x and the fair ratio is 16.5x. That premium signals less margin for error. Is the market already paying up for this narrative?
Before leaning too hard on any one framework, it helps to see how all three P/E reference points hang together in one place, then decide what feels realistic for BorgWarner’s next few years. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this BorgWarner setup feels balanced between promise and pressure, consider moving quickly to test that intuition against the data and form your own stance. A good place to start is by weighing the 4 key rewards and 2 important warning signs.
Looking For More BorgWarner Sized Ideas?
If BorgWarner has your attention, do not stop here. Broaden your watchlist with a few focused screens that can surface your next high conviction idea.
- Hunt for mispriced opportunities that combine quality with attractive entry points by scanning the 32 high quality undervalued stocks.
- Target resilience first and protect the downside by working through the 31 resilient stocks with low risk scores.
- Aim for balance sheet strength and steadier fundamentals by filtering candidates with the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com